
 Tatiana Tantri Indah Sari
The landscape of online travel distribution is undergoing its most profound transformation in decades, driven by the rapid evolution of artificial intelligence, shifting search engine dynamics, and the increasing complexity of airline fare structures. At the forefront of this industry-wide pivot are travel metasearch giants Kayak and Skyscanner, both of which are recalibrating their business models to survive and thrive in an ecosystem where traditional search pathways are no longer guaranteed.
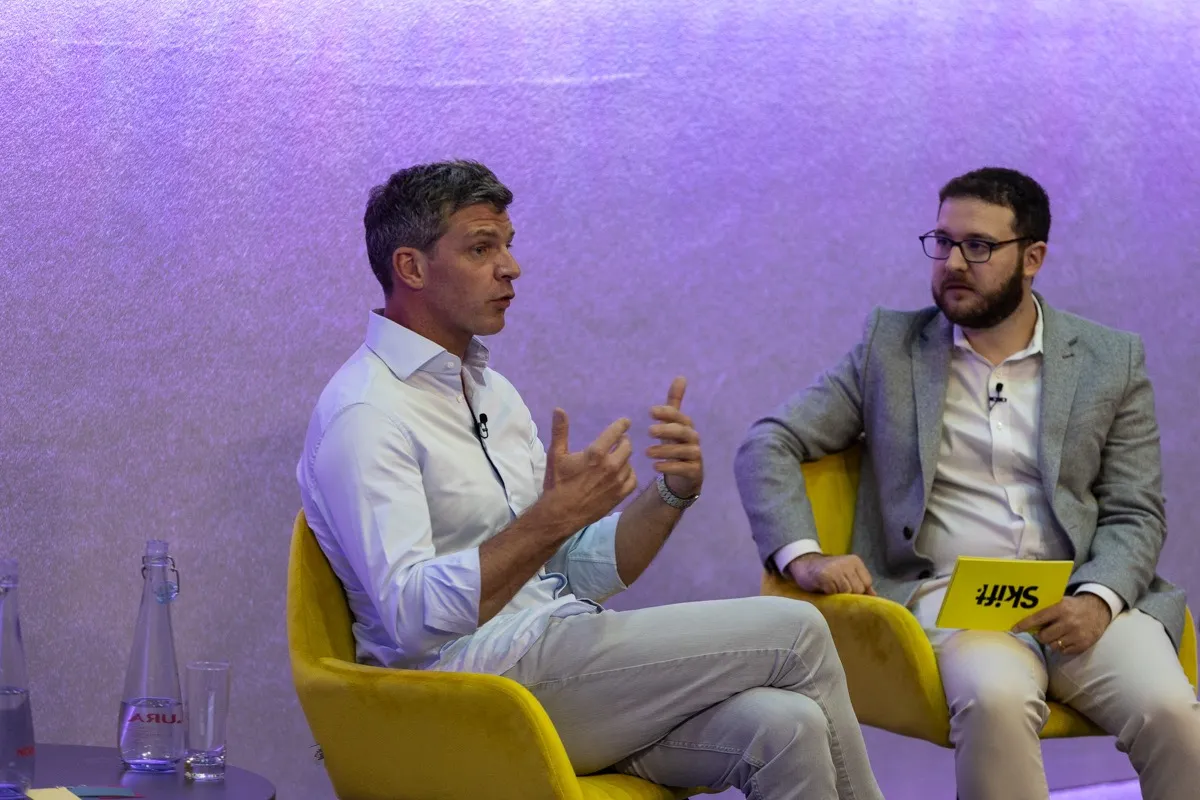
During recent industry discussions at major European travel and technology forums—including high-profile panels featuring Kayak leadership and Skift research analysts—executives laid bare the stark realities facing digital travel aggregation. The traditional playbook of driving organic traffic through search engines, aggregating comparative pricing, and handing off users to airline or hotel booking engines is facing unprecedented friction. As platforms like Google integrate generative artificial intelligence and proprietary travel carousels deeper into their core search experiences, metasearch providers are forced to rethink their value proposition entirely.
The Disruption of Traditional Distribution Channels
For over two decades, travel metasearch operated on a relatively straightforward premise: aggregate flight, hotel, and car rental data, display side-by-side comparisons, and monetize the referral traffic. However, the foundational mechanics of this distribution model have been fundamentally disrupted.
Peer Bueller, who stepped into the role of CEO at Kayak in February following a successful decade-long tenure as Chief Financial Officer, candidly addressed these structural headwinds. Bueller pointed to the aggressive expansion of generative artificial intelligence interfaces, such as Google’s Gemini, and the proliferation of native search result carousels. These features have systematically pushed traditional organic metasearch results further down the digital page.
In the current digital environment, visibility that was once earned organically now demands significant paid acquisition expenditures. Simultaneously, travel brands find themselves compelled to optimize their presence within Large Language Models (LLMs) to ensure they are cited when users prompt conversational AI agents for travel itineraries. This dual burden—paying for visibility on traditional search engines while engineering for algorithmic inclusion in AI models—has compressed profit margins and forced companies to diversify their monetization and acquisition strategies.
The Technical Complexity of Comparison
Despite the narrative that travel aggregation is a commoditized service easily replicated by emerging AI startups, industry veterans emphasize that the underlying infrastructure is immensely complex. Building a reliable, real-time comparison engine requires far more than basic web scraping.
Bueller emphasized that the data operations powering modern metasearch demand intricate technical integrations with hundreds of global suppliers. This includes establishing direct database access, navigating complex application programming interfaces (APIs), and executing strict commercial agreements that dictate how data can be processed, displayed, and monetized. Maintaining data freshness and pricing accuracy across thousands of dynamic airline routes, hotel chains, and car rental inventories is a resource-intensive endeavor that presents a significant barrier to entry for prospective market disruptors.
Furthermore, this operational complexity has compounded exponentially in recent years due to the airline industry’s widespread adoption of unbundled pricing models. Legacy and low-cost carriers alike now segment their fares into a dizzying array of attributes—separating seat selection, carry-on baggage, checked luggage, priority boarding, and change flexibility into distinct, modular fees.
Kayak has spent a quarter of a century refining side-by-side fare comparisons, yet leadership acknowledges that the task is becoming progressively more difficult. As airlines continue to obscure true baseline comparisons through hyper-personalized and highly fragmented fare attributes, presenting a clean, apples-to-apples comparison to the consumer requires sophisticated data normalization techniques.
Skyscanner’s Strategic Pivot: Packages, Multimodal, and Agents
While Kayak evaluates the core parameters of its search engine architecture, rival platform Skyscanner is charting a parallel yet distinct course through the shifting digital terrain. Rather than attempting to unseat the traditional metasearch model with an entirely unproven paradigm, Skyscanner is steadily expanding its operational footprint.
Industry insiders note that Skyscanner’s strategic roadmap involves leaning heavily into dynamic vacation packages, multimodal transportation integration, and the exploration of conversational agent capabilities. By broadening its inventory beyond simple point-to-point flight aggregation, Skyscanner aims to capture a larger share of the end-to-end travel planning lifecycle.
Multimodal travel—which seamlessly combines flights, trains, buses, and ferry services into a single unified itinerary—is rapidly transitioning from a niche preference to a core consumer demand, particularly across European markets where rail networks offer viable alternatives to short-haul aviation. By integrating these diverse transit modes into unified comparison interfaces, platforms like Skyscanner aim to insulate themselves against pure flight-search commoditization. Additionally, the potential integration of proprietary booking agents and conversational booking assistants within the platform signals a broader industry shift toward retaining the user within a closed-loop transactional environment, rather than merely acting as an initial referral funnel.
A Chronology of Transformation: From Web 1.0 Aggregators to AI Ecosystems
To understand the urgency driving current strategic shifts at Kayak and Skyscanner, it is helpful to trace the chronological evolution of the online travel booking ecosystem over the past twenty-five years:
- The Early 2000s (The Birth of Metasearch): Platforms like Kayak (founded in 2004) and Skyscanner (founded in 2003) emerge to solve consumer pain points by aggregating fragmented airline and hotel data onto single screens, challenging traditional online travel agencies (OTAs) that relied on proprietary inventory.
- The 2010s (Mobile Consolidation and Corporate M&A): The travel industry undergoes massive consolidation. Priceline Group (later renamed Booking Holdings) acquires Kayak in 2013 for $1.8 billion, while Ctrip (now Trip.com Group) acquires Skyscanner in 2016 for approximately $1.74 billion. Mobile applications become the primary battleground for consumer engagement.
- The Early 2020s (Post-Pandemic Recovery and Airline Unbundling): As global travel rebounds following pandemic-related disruptions, airlines aggressively accelerate ancillary revenue strategies. Fare unbundling complicates traditional database structures, making side-by-side price comparisons computationally challenging.
- 2023–2024 (The Generative AI Boom): The mainstream launch of OpenAI’s ChatGPT, Google Gemini, and various travel-specific LLMs initiates a profound shift in consumer search behavior. Travelers increasingly turn to conversational AI for preliminary itinerary planning rather than traditional search engines or standalone metasearch apps.
- 2025–2026 (Strategic Realignment): Industry leaders formally acknowledge the limits of legacy traffic acquisition. Metasearch platforms shift focus toward deep supplier integrations, multimodal inventory, and hybrid business models that incorporate AI-driven conversational agents and direct-booking capabilities.
Market Data and Economic Realities
The financial and operational pressures facing metasearch platforms are underscored by broader macroeconomic and digital marketing trends within the travel sector. According to recent digital marketing benchmarks, customer acquisition costs (CAC) for travel brands have risen steadily over the past five years. This inflation is driven by increased competition for high-intent keywords on traditional search engines and the displacement of organic search results by paid advertising placements and native AI features.
Simultaneously, consumer behavior data indicates a growing preference for frictionless, end-to-end user experiences. Modern travelers, particularly digital natives within Millennial and Gen Z demographics, increasingly expect platforms to not only compare prices but also facilitate instant checkout, multi-supplier itinerary management, and real-time customer service support within a single application interface.
This behavioral shift challenges the foundational business model of pure-play metasearch, which historically relied on monetizing outbound referral clicks to third-party suppliers. When users can complete complex, multi-modal travel bookings directly inside an AI-powered chat interface or a consolidated super-app, the incentive to visit a traditional comparison site diminishes unless that site offers distinct, high-value utility.
Industry Implications and Future Outlook
The strategic recalibration underway at Kayak, Skyscanner, and their parent conglomerates carries significant implications for the broader travel technology ecosystem.
For airline and hotel suppliers, the changing strategies of metasearch engines affect direct-to-consumer distribution economics. As aggregators push deeper into unbundled fare parsing and multimodal packaging, suppliers must decide whether to lean into these complex integrations or attempt to recapture consumer loyalty through proprietary direct-booking channels and loyalty programs. The ability of suppliers to maintain data parity and control over their brand attributes across an increasingly diverse array of AI interfaces will remain a critical commercial battleground.
For travel tech startups and emerging competitors, the high technical barriers highlighted by industry executives serve as a cautionary reality check. While generative AI has democratized the creation of consumer-facing user interfaces, the underlying plumbing of global travel distribution—requiring robust commercial partnerships, secure API connections, and real-time inventory synchronization—remains remarkably difficult to scale.
Ultimately, the future of travel metasearch will not be defined by the abandonment of price comparison, but by its reinvention. As Peer Bueller and fellow industry leaders navigate the intersection of artificial intelligence, complex fare unbundling, and shifting consumer habits, the winners of the next decade will be those platforms that successfully transition from simple price-comparison tools into indispensable, intelligent travel companions.




 Gabriela Annisa

 Lukman Taruna Persada Ramadan

 Anjar Salim

 Dwi Wanna
