
 Gabriela Annisa
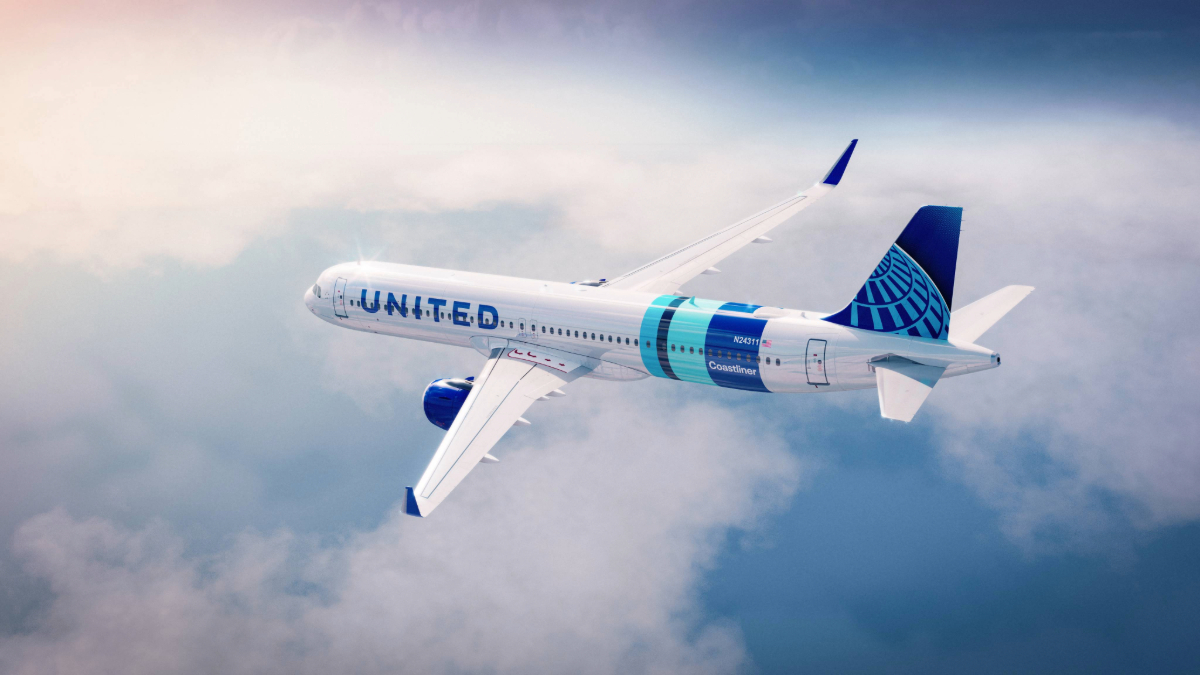
The transatlantic aviation landscape is undergoing a significant structural transformation as United Airlines and American Airlines pivot their international growth strategies toward secondary European markets facilitated by new narrow-body aircraft technology. This shift marks a departure from the traditional hub-to-hub model that has defined long-haul travel for decades, signaling a transition toward point-to-point operations that favor efficiency, premium configuration, and market agility. As both carriers announce expanded route networks, the industry is closely monitoring the economic implications of utilizing the Airbus A321XLR—a narrow-body aircraft with long-range capabilities—to capture high-yield premium demand in thinner markets.
Chronology of the Transatlantic Pivot
The current strategic expansion follows years of post-pandemic recovery characterized by unprecedented demand for international travel. In 2023, U.S. carriers saw transatlantic demand levels reach or exceed 2019 figures, prompting a reevaluation of fleet deployment.
Throughout the first half of 2024, United Airlines and American Airlines began filing regulatory requests and announcing new service additions for the 2025 summer season. United, maintaining its aggressive approach to network diversification, has targeted niche European hubs that allow for regional connectivity without the bottleneck of major mega-hubs like London Heathrow or Frankfurt. American Airlines, meanwhile, has focused on reinforcing its partnership-led strategy, utilizing its joint business agreements with British Airways, Iberia, and Finnair to optimize its transatlantic footprint.
The introduction of the Airbus A321XLR into these fleets serves as the technical catalyst for this shift. With a range of up to 4,700 nautical miles, the aircraft allows carriers to connect mid-sized U.S. cities to European destinations that were previously deemed unviable for wide-body operations due to the high cost of fuel and the difficulty of filling massive seat counts.
The Role of the Airbus A321XLR in Modern Fleet Strategy
The A321XLR represents a fundamental shift in how network carriers approach fleet composition. Historically, long-haul transatlantic routes required wide-body aircraft such as the Boeing 777 or the Airbus A350. While these aircraft offer significant cargo capacity and volume, they require high passenger load factors to reach profitability.
The A321XLR, by contrast, lowers the barrier to entry for new routes. By operating a single-aisle aircraft with fewer seats, carriers can achieve profitability with lower passenger volumes, enabling them to launch "thin" routes that cater specifically to high-paying business and premium leisure travelers. However, this shift introduces a new risk profile. Because the aircraft relies heavily on premium cabin configuration to offset the lower overall seat count, the business model is highly sensitive to fluctuations in premium demand. If corporate travel spending softens, the economic viability of these niche routes could be challenged, as the aircraft lacks the massive economy-class capacity of wide-body jets to buffer against downturns.
Market Performance and Financial Context
The performance of the airline sector remains a critical barometer for broader economic health. According to the Skift Travel 200 (ST200) index, which aggregates the financial performance of nearly 200 travel-related companies, the aviation sector has faced volatility throughout the year. The ST200, which monitors a trillion dollars in travel-related value, highlights that while network carriers are reporting strong yields, stock prices remain pressured by rising labor costs, engine maintenance issues, and the high capital expenditure required for fleet modernization.
Data from the first half of the year suggests that airlines are prioritizing margin expansion over rapid capacity growth. By utilizing the A321XLR, carriers are effectively "right-sizing" their capacity to match demand, a strategy aimed at protecting margins even if overall seat growth slows. Financial analysts note that the ability of carriers to maintain high revenue per available seat mile (RASM) is tied directly to this transition toward more efficient, premium-focused narrow-body operations.
Analysis of Operational Implications
The shift toward point-to-point transatlantic service carries significant implications for hub-and-spoke infrastructure. Traditional hubs—such as Chicago O’Hare, New York-JFK, and Newark Liberty—have long functioned as the primary gateways for international transit. By bypassing these hubs, carriers can reduce passenger congestion and streamline the connection process, but they also risk losing the "feed" traffic that makes larger wide-body flights profitable.
Furthermore, the operational reliance on the A321XLR necessitates a change in maintenance and training protocols. Flight crews must be cross-trained for long-haul operations on narrow-body equipment, and ground operations must adapt to faster turnaround times. From a passenger experience standpoint, the primary concern remains the comfort of narrow-body jets on flights exceeding seven hours. While carriers are equipping these aircraft with lie-flat business class seats and modernized interiors, the cabin environment inevitably differs from the spaciousness associated with wide-body aircraft.
Official Perspectives and Industry Response
While airline executives have remained optimistic regarding the A321XLR’s performance, there is a guarded consensus among industry experts. During recent earnings calls, leadership teams from both United and American emphasized the "flexibility" afforded by the new fleet. The consensus is that the A321XLR acts as a scalpel, allowing carriers to surgically target specific geographic markets without the risk associated with larger, more expensive assets.
Competitors and industry observers have noted that this strategy also acts as a defensive maneuver against low-cost, long-haul entrants. By dominating the premium segments of secondary markets, major carriers can insulate themselves from the price-sensitive, low-cost competition that often focuses on high-volume, economy-focused transatlantic routes.
Broader Economic and Global Impact
The transatlantic corridor remains the most profitable aviation market in the world. As U.S. carriers refine their strategies, the global aviation market is likely to see a period of increased competition for slots and landing rights in secondary European cities. This competitive tension is expected to benefit consumers, particularly those in secondary U.S. markets who previously had to connect through major hubs to reach Europe.
However, the strategy is not without its macroeconomic risks. The reliance on premium demand assumes that corporate travel, which has seen a resilient recovery post-pandemic, will continue to grow. Should there be a global economic slowdown, the high-cost, low-volume model of the A321XLR could become a liability. Additionally, the ongoing geopolitical climate in Europe—including airspace restrictions and fuel price volatility—adds a layer of complexity to the long-term planning of these routes.
Conclusion
The expansion efforts by United and American Airlines, centered on the strategic deployment of the A321XLR, underscore a broader trend of efficiency and precision in the aviation sector. By leveraging advanced narrow-body technology, these carriers are not merely expanding their route maps; they are redefining the fundamental mechanics of transatlantic travel. As the industry moves forward, the success of this strategy will depend on the continued appetite for premium travel and the operational reliability of the new fleet. Investors and stakeholders in the Skift Travel 200 will be watching closely to see if this shift toward agility translates into sustained profitability in an increasingly complex and cost-sensitive global marketplace. The coming quarters will likely provide the first empirical data on whether this narrow-body experiment can withstand the rigors of long-haul operations and shifting consumer preferences.




 Lukman Taruna Persada Ramadan

 Tatiana Tantri Indah Sari

 Anjar Salim


 Dwi Wanna
