Tatiana Tantri Indah Sari
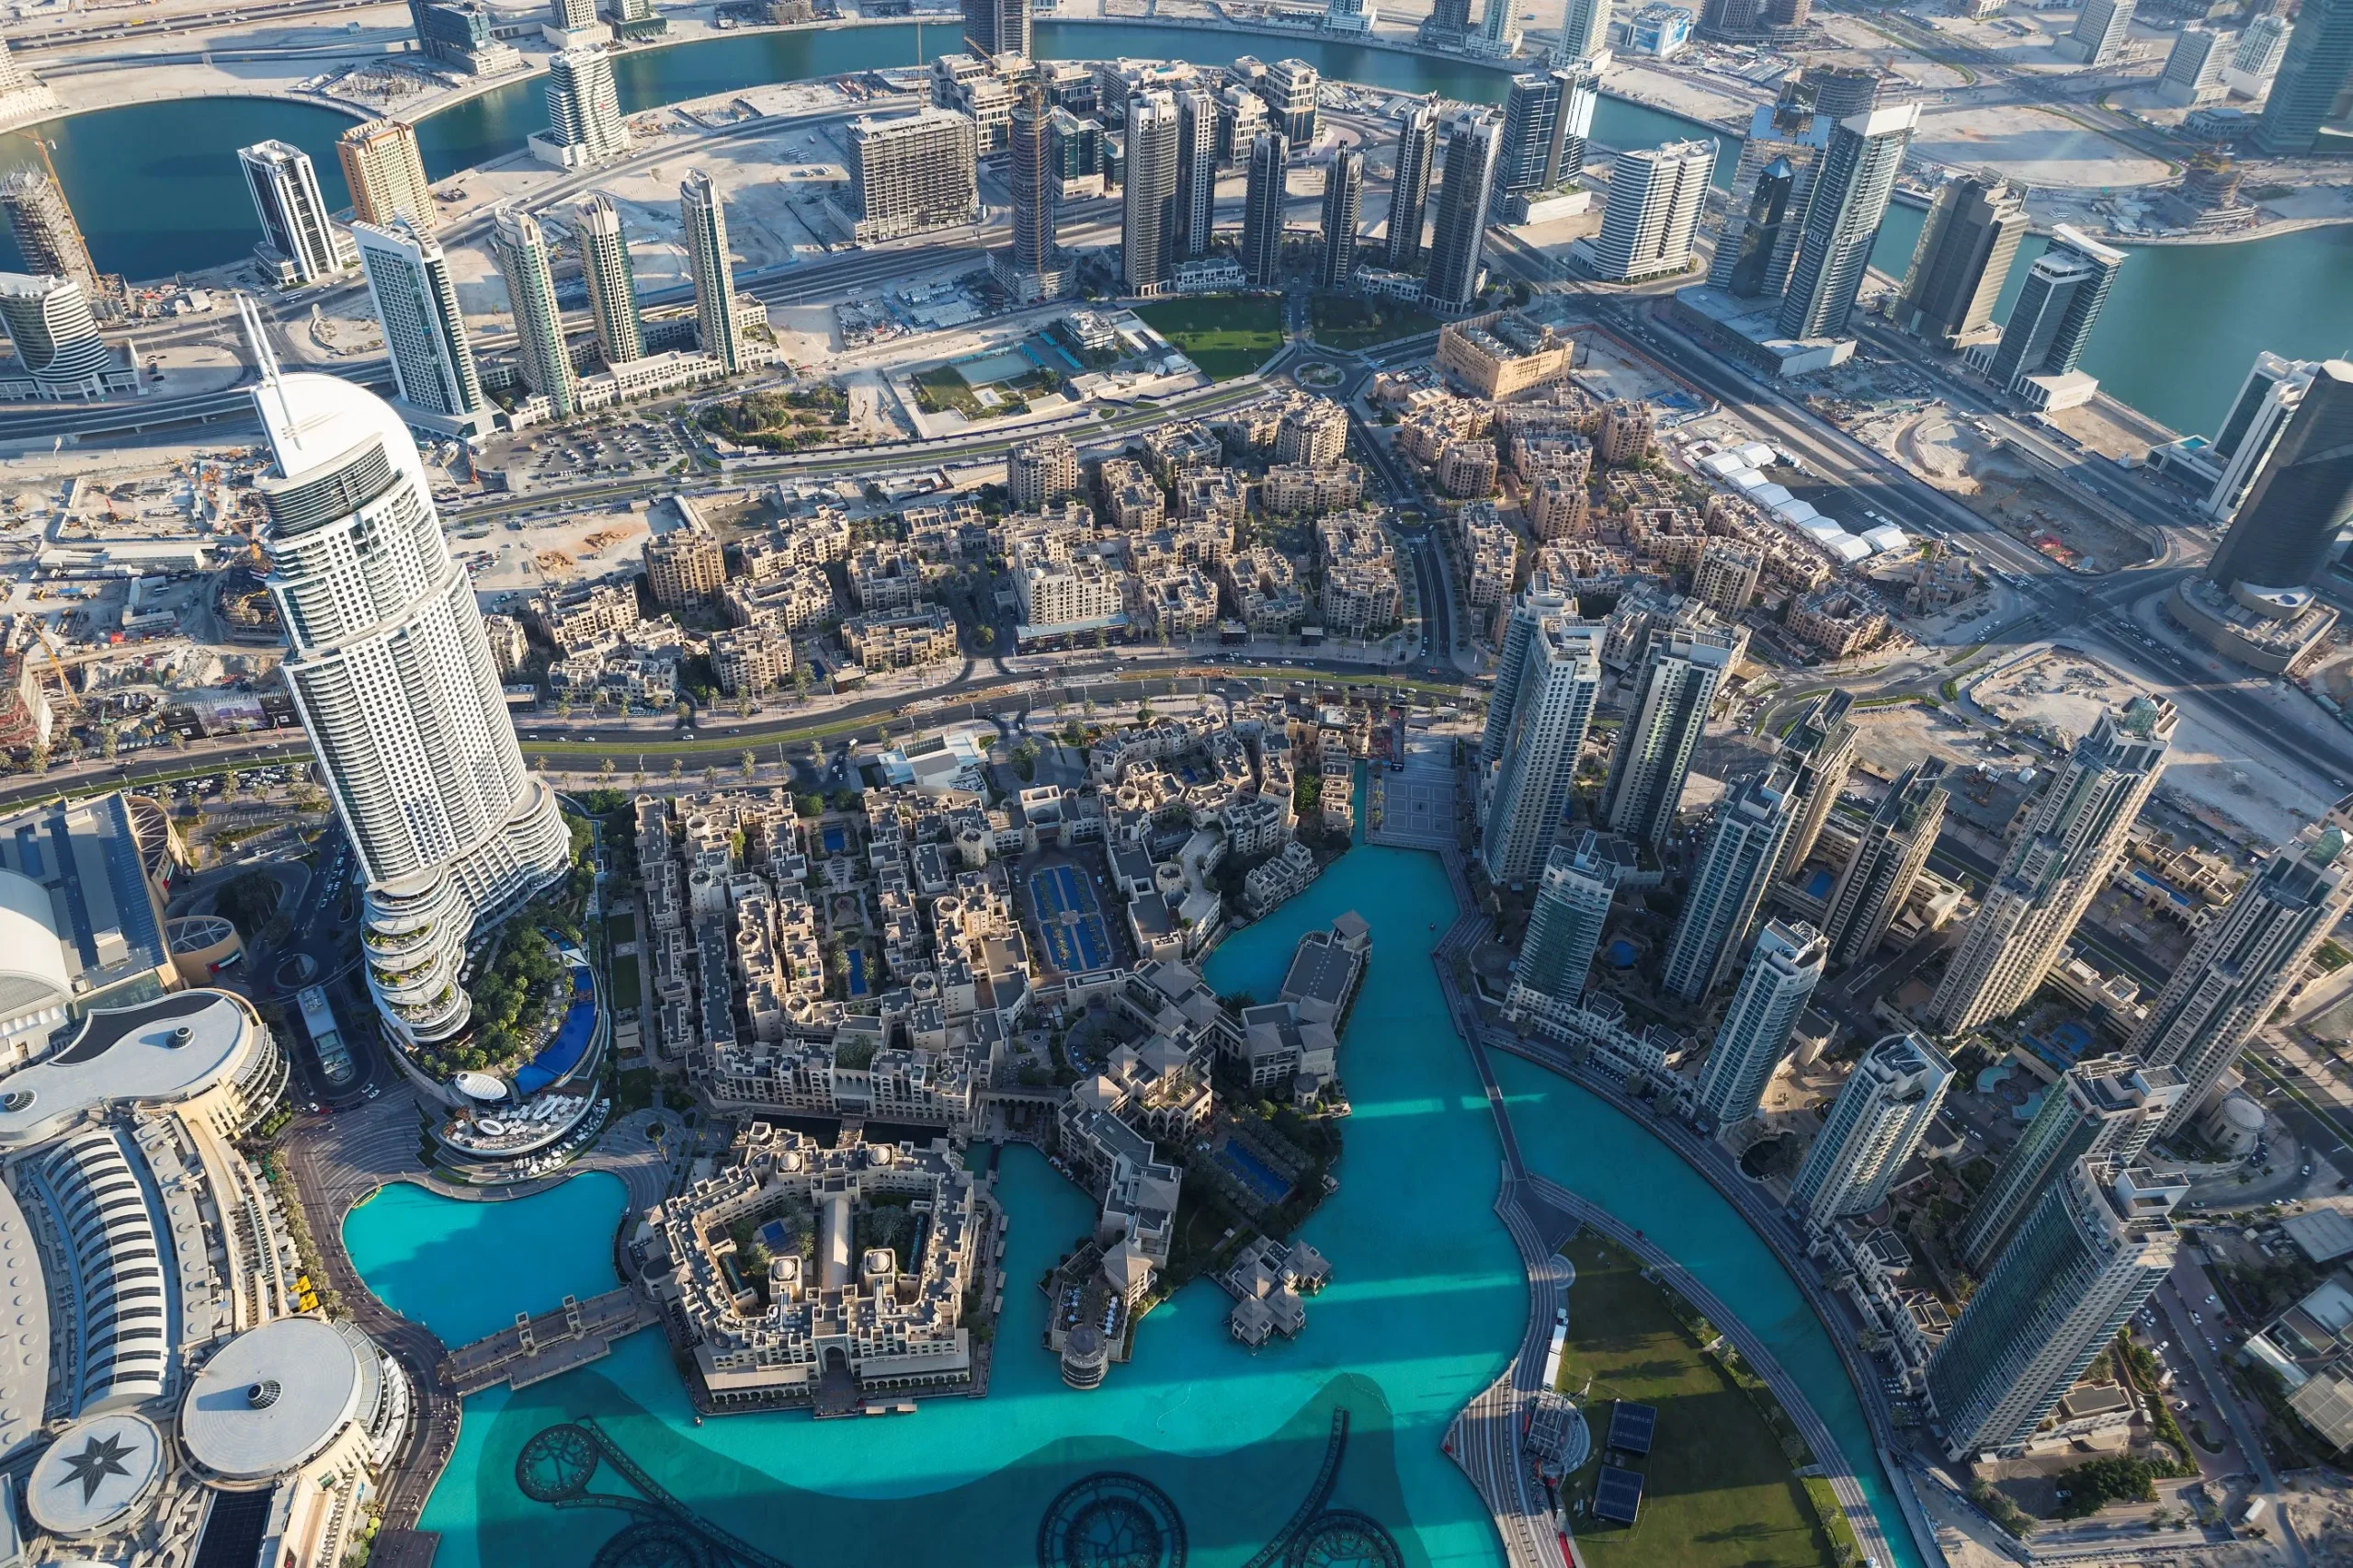
The international travel and tourism sector experienced a notable stabilization punctuated by regional volatility in the middle of the summer season, according to the latest figures released by the Skift Travel Health Index. In July, the global index registered at 99, marking a slight contraction of 1% year-on-year. While mature travel markets in Europe and the Americas maintained steady, albeit cautious, trajectories toward pre-pandemic norms, the global aggregate was dragged downward by sudden, localized disruptions. Most notably, the Middle East and Africa region suffered a severe reversal of fortune, dropping sharply from a complete post-pandemic recovery in June to a pronounced slump just a month later.
This unexpected downturn highlights the fragility of international tourism recovery in regions sensitive to geopolitical tensions, security developments, and regulatory interventions. Industry analysts note that while consumer demand for global travel remains fundamentally resilient, external shocks can instantaneously disrupt traveler confidence, transforming prospective interest into canceled itineraries and stagnant booking volumes.
The July Reversal: From Full Recovery to Sudden Decline
The trajectory of the Middle East and Africa travel market over the summer months serves as a case study in the rapid volatility that can affect regional tourism economies. In June, the region achieved a significant milestone by hitting the benchmark level of 100 on the Skift Travel Health Index, indicating a full recovery to pre-2019 baseline performance metrics. Stakeholders across the Gulf Cooperation Council (GCC) member states and major North African tourism hubs anticipated a lucrative summer season, fueled by aggressive destination marketing campaigns, large-scale entertainment events, and expanded aviation connectivity.
However, this optimism was short-lived. By July, the regional index tumbled six points to 94. The primary catalyst for this sudden contraction was a cascade of renewed security concerns that rippled across parts of the region. As geopolitical tensions flared, several key source markets issued updated travel advisories, warning citizens against non-essential travel to specific sub-regions. Compounding the situation, numerous international carriers enacted temporary flight suspensions or rerouted flight paths to avoid airspace deemed high-risk.
These developments exerted immediate pressure on a market that, upon closer inspection, had already been exhibiting underlying vulnerabilities and margin fatigue. The combination of negative media narratives, official governmental warnings, and logistical hurdles severely dented consumer confidence. Consequently, travel agencies and airline operators reported a significant drop-off in conversion rates; while web traffic and initial consumer interest in Middle Eastern and African destinations remained moderately stable, prospective travelers repeatedly hesitated at the final booking stage, opting instead for alternative, perceived safer destinations in Europe or Asia.
Sector Performance Divergence: The Resilience of Vacation Rentals
Beneath the headline-grabbing decline in overall regional tourism performance, sector-by-sector analysis reveals a highly fragmented market. Traditional hospitality segments, including luxury hotels, business resorts, and legacy airlines, bore the brunt of the July cancellations and reduced forward bookings. Corporate travel, in particular, experienced a delayed summer lull as enterprise clients exercised heightened caution regarding employee safety and regional stability.
In stark contrast, the alternative accommodation sector demonstrated remarkable immunity to the broader market downturn. Vacation rentals emerged as the sole sector in the Middle East and Africa to perform significantly above the benchmark during the month, recording an impressive 14% year-on-year growth compared to July of the previous year.
Industry experts attribute this divergence to evolving consumer preferences among regional and domestic travelers, as well as inbound visitors from neighboring stable economies. Vacation rentals often offer greater privacy, controlled environments, and flexible cancellation policies—all of which became highly prized attributes for travelers navigating an uncertain security landscape. Furthermore, the rise of domestic tourism within key regional hubs like the United Arab Emirates and Saudi Arabia bolstered short-term rental demand, as residents chose local staycations over complex international itineraries affected by flight disruptions.
The Broader Context: A Potential Lost Year for Gulf Tourism
The July slump comes on the heels of mounting concerns regarding the broader economic trajectory of tourism in the wider Gulf region for the current calendar year. Industry observers and economic forecasters have increasingly warned that persistent geopolitical friction could culminate in a "lost year" for Gulf tourism growth, potentially stalling multi-billion-dollar diversification projects tied to national economic transformation agendas, such as Saudi Arabia’s Vision 2030 and the UAE’s tourism-led economic strategies.
Over the past several years, Gulf nations have invested heavily in establishing themselves as premier global aviation hubs, cultural capitals, and entertainment destinations. Mega-projects, luxury real estate developments, and high-profile international sporting events have been deployed to attract millions of global visitors annually. However, the events of July demonstrate that these ambitious targets remain vulnerable to exogenous geopolitical shocks. When regional instability flares, the psychological distance for international long-haul travelers collapses, leading them to perceive the entire geographic expanse as volatile, regardless of whether a specific destination remains entirely safe and unaffected on the ground.
Official Responses and Stakeholder Reactions
In the wake of the July data release, tourism boards, airline executives, and hospitality leaders across the Middle East and Africa have mobilized to mitigate the reputational damage and restore consumer trust. Major regional carriers have emphasized their adherence to the highest safety and security standards, noting that flight suspensions were precautionary measures designed primarily to ensure passenger and crew welfare amid shifting airspace regulations.
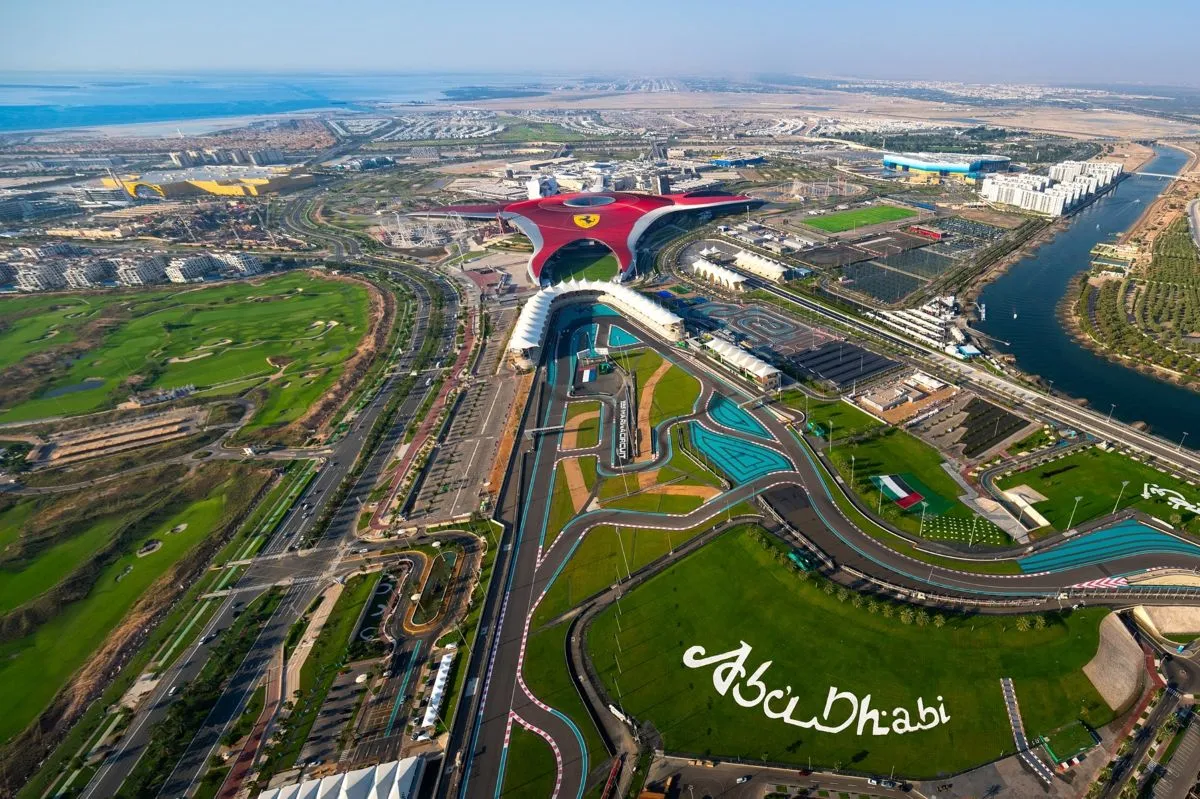
Tourism authorities in countries such as the United Arab Emirates, Qatar, and Oman have intensified their communication strategies, emphasizing local stability, robust infrastructure, and the physical distance between their primary tourism assets and active zones of conflict. Marketing campaigns are increasingly pivoting toward domestic markets and resilient source regions in Asia and parts of Europe that have proven less sensitive to regional travel advisories.
Hospitality operators, meanwhile, are introducing highly flexible booking terms, including zero-penalty cancellation policies and comprehensive travel insurance partnerships, in a bid to reassure hesitant bookers. Analysts suggest that these tactical maneuvers are necessary to bridge the confidence gap in the short term, though long-term recovery will ultimately depend on a de-escalation of regional tensions.
Economic Implications and Future Outlook
The broader economic implications of the July travel slowdown extend far beyond the hospitality sector. Tourism serves as a critical pillar of GDP growth, employment, and foreign exchange earnings for numerous economies across the Middle East and Africa. A sustained dip in visitor volumes threatens to impact retail revenues, food and beverage sectors, transportation networks, and the employment prospects of millions of hospitality workers.
Looking ahead, economists and travel industry analysts maintain a cautiously watchful stance as the industry navigates the remainder of the third and fourth quarters. Much will depend on the evolution of geopolitical dynamics in the coming months. If security advisories are lifted and normal aviation routes are fully restored, pent-up demand could trigger a rapid rebound, given the enduring appeal of the region’s world-class tourism infrastructure. Conversely, prolonged instability risks entrenching traveler hesitancy, forcing regional stakeholders to recalibrate their growth projections and rely more heavily on domestic and intra-regional travel demand to sustain the sector through the remainder of the year.

 Anjar Salim
 Chandra Hamzah
 Budi Mulyono
 Lukman Taruna Persada Ramadan