
 Tatiana Tantri Indah Sari
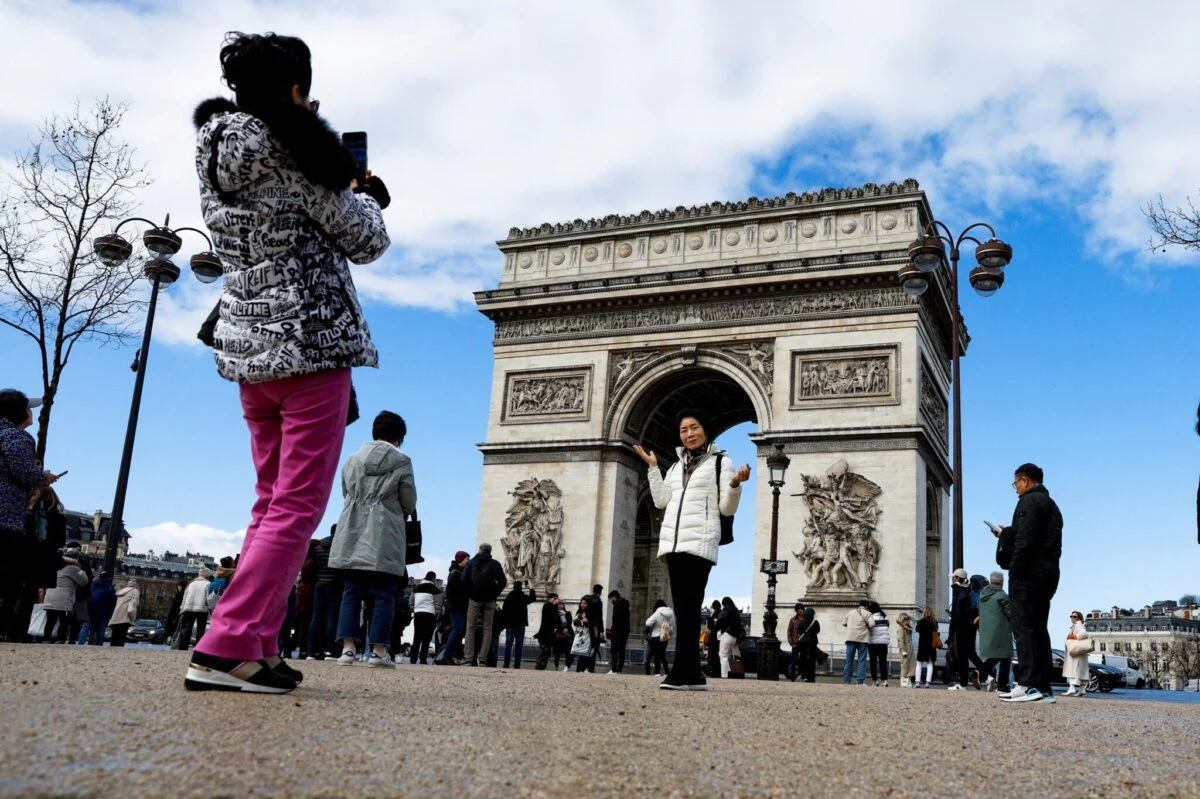
The landscape of Chinese outbound tourism is undergoing a significant structural transformation, highlighted by the arrival of the Golden Week and Mid-Autumn Festival holiday period. While calendar configurations have gifted travelers with an extended holiday window—sparking a surge in long-haul departures and prolonged itineraries—the economic windfall once anticipated by the global luxury hospitality sector is failing to materialize. According to the latest Chinese Traveler Sentiment Report published this week by market research firm Dragon Trail Research, an overwhelming majority of outbound travelers are bypassing high-end properties in favor of more economical accommodations.
The data reveals a stark disconnect between extended travel durations and luxury spending. Only 5 percent of Chinese citizens planning international trips during this Golden Week cycle intend to book luxury hotels. Instead, mid-range and economy properties have emerged as the clear favorites for the vast majority of holidaymakers. This shift underscores a broader trend of cautious consumer spending within China’s outbound tourism market, even as overall travel volumes demonstrate a resilient recovery.
Extended Itineraries and Shifting Booking Patterns
The mechanics of this year’s holiday calendar have uniquely shaped travel habits. China’s Mid-Autumn Festival preceded the official National Day Golden Week, creating a rare bridge of potential holiday days. According to comprehensive booking data released by Trip.com Group, the average duration of an outbound trip surrounding the holiday window has now surpassed nine days. Furthermore, pent-up demand for immersive, extended travel is reflected in long-term bookings; reservations for hotel stays spanning seven nights or more have skyrocketed by 123 percent compared to the same period last year.
Travelers are also capitalizing on strategic leave-taking to maximize their time away. By utilizing just three days of annual leave between September 28 and September 30, resourceful tourists have been able to construct a staggering 13-day holiday itinerary. This flexibility has prompted a noticeable shift in departure behaviors. Trip.com data indicates that more than half of all outbound flight bookings are scheduled for departures prior to October 1, the official start of the National Day holiday, allowing visitors to beat peak airport congestion and secure more favorable flight pricing.
However, the financial allocation of these travelers tells a vastly different story than in pre-pandemic years. The willingness to invest in extended travel days has not translated into a comparable willingness to splurge on five-star accommodations. Industry analysts note that contemporary Chinese tourists are exhibiting heightened price sensitivity, favoring value and utility over opulent resort experiences.
The Evolution of Chinese Outbound Tourism: A Chronology of Recovery
To understand the current sentiment of the Chinese outbound traveler, it is essential to examine the historical trajectory of the market over the past half-decade.
Prior to 2020, Chinese tourists represented the single most lucrative demographic for the global tourism and luxury retail industries. Accounting for nearly a quarter of global international tourism spending, the "Golden Week" holidays—spanning the Lunar New Year and October National Day periods—were synonymous with massive tour groups, heavy retail consumption in European capitals, and high occupancy rates at luxury hotels worldwide.
The onset of the global health crisis in early 2020 brought this multi-billion-dollar engine to an abrupt halt. China’s strict domestic containment measures and prolonged border closures effectively cut off outbound travel for nearly three years. During this period, the domestic tourism market experienced a forced boom, fostering the growth of localized boutique travel, regional camping trends, and a greater familiarity with domestic mid-range hospitality infrastructure.
When Beijing officially dismantled its zero-COVID policy and reopened its borders in January 2023, the global tourism ecosystem braced for an immediate tsunami of high-spending visitors. Hopes were high that outbound travel would instantly resume its pre-pandemic patterns. Yet, the initial months of 2023 proved that recovery would be a gradual, uneven process. International flight capacity faced severe bottlenecks, visa processing backlogs persisted across multiple consulates, and economic headwinds at home began to temper consumer confidence.
By the summer of 2023, while regional destinations in Southeast Asia and East Asia saw steady arrivals, long-haul travel to Europe and North America lagged behind expectations. Throughout late 2023 and early 2024, economic indicators within China—particularly challenges within the domestic real estate sector and youth employment market—began to visibly influence consumer spending behavior. By the time the current Golden Week holiday cycle approached, travelers were eager to venture abroad, but their financial calculus had fundamentally changed. The modern Chinese tourist is markedly more independent, digital-savvy, and budget-conscious than their 2019 counterpart.
Industry Responses and Strategic Adjustments
The revelation that only 5 percent of outbound travelers are opting for luxury hotels has sent ripples through the international hospitality industry. Hoteliers in major European, North American, and Asia-Pacific hubs are currently scrambling to recalibrate their marketing strategies to capture this shifting demographic.
Historically, luxury hotels relied heavily on direct partnerships with high-end Chinese travel agencies and dedicated Mandarin-speaking concierge services tailored to ultra-high-net-worth individuals. Today, industry stakeholders note that the focus must pivot toward mid-tier engagement, digital wallet compatibility, and culturally nuanced customer service that appeals to independent, younger travelers.
Hospitality groups operating three- and four-star properties are experiencing an unexpected windfall. Executives within major mid-range hotel chains have reported a surge in inquiries from Asian markets, prompting many to enhance their digital infrastructure, introduce localized breakfast options, and integrate preferred Chinese payment gateways such as WeChat Pay and Alipay directly into their booking systems.
Airlines and destination marketing organizations (DMOs) are also adjusting their promotional campaigns. Rather than marketing high-end shopping districts and exclusive luxury resorts, tourism boards across various global destinations are emphasizing cultural immersion, outdoor recreation, historical sightseeing, and affordable culinary experiences. This pivot acknowledges that while the volume of travelers is steadily returning to pre-pandemic baselines, the yield per tourist—particularly regarding accommodation and high-end retail—requires a completely different operational approach.
Economic Implications and Broader Market Impact
The preference for mid-range and economy accommodations during an extended Golden Week carries profound economic implications for the global travel and tourism sector.
First, it highlights a broader macroeconomic reality: consumer confidence in China is currently navigating a period of stabilization and cautious recalibration. While households are clearly willing to allocate disposable income toward experiential milestones like international travel—evidenced by the 123-percent surge in seven-night-plus hotel bookings—they are simultaneously exercising strict fiscal discipline. Discretionary spending on luxury lodging, high-end dining, and luxury retail is being re-evaluated.
Second, the dispersal of tourist spending will likely benefit a wider array of local businesses rather than concentrating wealth solely within elite luxury conglomerates. When travelers opt for mid-range hotels, they typically retain a higher percentage of their travel budget for experiences outside the hotel walls—such as public transportation, local independent dining, neighborhood markets, and cultural attractions. Local economies, small-to-medium enterprises (SMEs), and regional service providers may ultimately see a more democratic distribution of tourism revenue during this holiday cycle.
Finally, the trend forces a re-evaluation of key performance indicators (KPIs) for destination management organizations worldwide. For years, the success of the Chinese outbound market was measured primarily through aggregate spending volume and luxury retail receipts. As the market matures and evolves into a more independent, value-seeking demographic, success will increasingly be measured by length of stay, repeat visitation rates, geographical dispersion beyond major gateway cities, and engagement with sustainable local tourism initiatives.
As the Golden Week holidays progress and final arrival statistics are tallied, tourism ministers, airline executives, and hospitality leaders will be closely analyzing the data. The message from the modern Chinese traveler is unmistakable: the desire to explore the world remains as robust as ever, but the era of unbridled luxury spending has given way to a pragmatic, value-driven era of global exploration.




 Gabriela Annisa

 Lukman Taruna Persada Ramadan

 Anjar Salim

 Dwi Wanna
