
 Gabriela Annisa
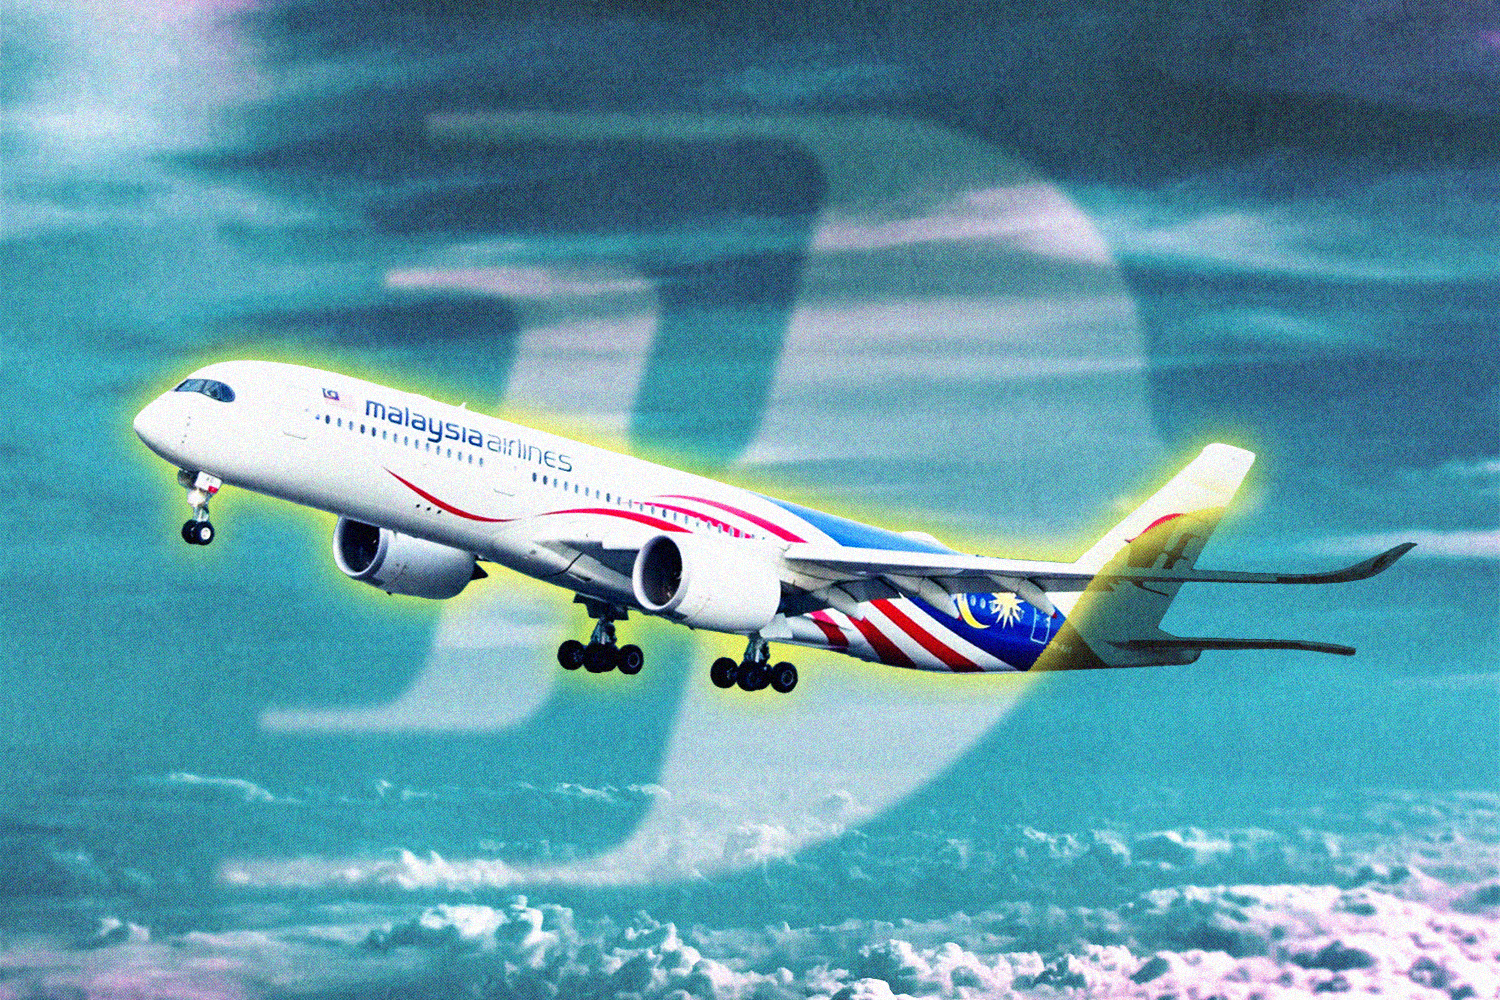
Malaysia Airlines has navigated a period of remarkable financial stabilization, stringing together four consecutive years of profitability in the post-pandemic era. However, this recovery remains fragile. With net margins currently hovering below 1%, the national carrier faces a precarious balancing act as it confronts a staggering 90% year-over-year increase in fuel expenses. While the airline has successfully emerged from its deep Covid-19 restructuring, the reliance on auxiliary revenue streams—specifically cargo operations and third-party maintenance services—rather than core passenger aviation operations, has raised questions about the long-term sustainability of its current business model.
The Anatomy of a Fragile Recovery
Since the implementation of its comprehensive restructuring program, Malaysia Airlines has sought to shed the legacy of its pre-pandemic financial woes. The transition from a state-subsidized carrier to a self-sustaining entity required a significant reduction in capacity, the renegotiation of aircraft leases, and a pivot toward higher-yield segments.
Data from the past four fiscal years indicate that the airline’s bottom line has been buoyed by the global cargo boom and the MRO (Maintenance, Repair, and Overhaul) sector. During the height of the pandemic, when passenger traffic plummeted, the carrier’s cargo division became a vital lifeline, capitalizing on the scarcity of belly-hold capacity globally. While this strategy prevented insolvency, it masked underlying inefficiencies in the passenger business. Now, as the global aviation market shifts back to competitive passenger demand, the airline is discovering that its core flying operations remain highly sensitive to macroeconomic volatility.
The Fuel Price Shock and Operating Constraints
The most pressing threat to Malaysia Airlines’ recent stability is the unprecedented surge in jet fuel prices. Industry analysts note that fuel typically accounts for 25% to 30% of an airline’s total operating costs. A 90% increase in this expenditure represents an existential pressure point for an organization with a net margin of less than 1%.
When margins are this thin, airlines lose the ability to absorb cost spikes through internal efficiencies alone. Consequently, Malaysia Airlines is forced into a difficult dilemma: either pass the entirety of these costs onto passengers—potentially dampening demand in a price-sensitive Southeast Asian market—or accept further margin erosion that could jeopardize its four-year streak of profitability. The airline is currently reviewing its hedging strategies, yet in a market defined by sustained geopolitical instability, the efficacy of such hedges remains limited.
Chronology of the Modern Malaysia Airlines
The current strategic environment is the culmination of a decade of institutional upheaval. To understand the carrier’s present challenges, one must examine the timeline of its transformation:
- 2014-2015: Following the twin tragedies of MH370 and MH17, the airline underwent a state-led privatization and a massive downsizing effort under the direction of Khazanah Nasional.
- 2020-2021: The Covid-19 pandemic necessitated a second, more aggressive restructuring. The airline secured the support of its creditors to reduce liabilities by billions of dollars, effectively resetting its balance sheet.
- 2022-2024: A period of "cautious expansion" characterized by the optimization of the route network and a focus on high-yield business class traffic.
- 2025-2026: The current phase, marked by intensified regional competition and the urgent requirement to modernize the widebody fleet to remain competitive against regional peers.
Competitive Pressures: The Rebirth of AirAsia
The landscape of the Southeast Asian aviation market has been fundamentally altered by the reorganization of the AirAsia Group. Having consolidated its various regional entities into a single, cohesive airline structure, AirAsia now presents a more formidable challenge than ever before. By streamlining its fleet and standardizing operations, AirAsia has achieved a level of cost efficiency that is difficult for a full-service legacy carrier like Malaysia Airlines to replicate.
The competitive tension is most visible in the short-to-medium-haul segments. As AirAsia aggressively expands its footprint, Malaysia Airlines finds itself defending its premium market share while struggling to keep its own unit costs down. The "single airline" approach adopted by its rival allows for greater agility in capacity deployment, putting Malaysia Airlines at a structural disadvantage if it cannot achieve similar economies of scale.
The Widebody Order and Fleet Modernization
Central to the airline’s future is the upcoming widebody fleet decision. The selection of new-generation, fuel-efficient aircraft is not merely a logistical necessity but a strategic mandate. The current fleet, which includes older A330 and A350 models, requires significant capital expenditure for maintenance. By transitioning to a more modern fleet, the airline aims to reduce fuel consumption by an estimated 15% to 20% per seat mile.
However, ordering new aircraft requires massive capital commitment. In the current interest rate environment, securing financing for these assets is expensive. The leadership team at Malaysia Airlines must decide whether to commit to a major capital expenditure program while its margins are under siege or to continue extending the life of its current fleet, which risks falling further behind in fuel efficiency and cabin comfort.
Analysis of Financial Implications
From an investor and stakeholder perspective, the current financial data suggests that Malaysia Airlines is in a "maintenance mode" rather than a "growth mode." A net margin below 1% implies that the company has almost no buffer for operational disruptions, such as engine technical issues, supply chain delays in spare parts, or further spikes in crude oil prices.
While the airline has successfully demonstrated that it can operate as a going concern, the lack of robust profitability suggests that the current network structure may still be carrying legacy inefficiencies. The reliance on cargo revenue—which is notoriously cyclical—poses a long-term risk. Should global trade volumes soften, the primary engine currently driving the airline’s profitability could stall, leaving the passenger business to carry the full weight of the company’s overhead.
Official Perspectives and Market Outlook
While specific executive commentary on the latest fuel figures remains guarded, industry observers note that the airline’s management has consistently signaled a commitment to "disciplined growth." In previous briefings, representatives have emphasized the importance of yield management over market share.
Market analysts suggest that the next 18 months will be decisive. If the airline can successfully integrate new, more efficient aircraft and if fuel prices stabilize at a level lower than the current peak, the company may be able to transition from survival to genuine wealth creation. However, if the current macroeconomic trends persist, the board may be forced to consider more radical cost-cutting measures, including the potential consolidation of routes or a further reduction in the size of the workforce.
Broader Implications for the Aviation Sector
The situation at Malaysia Airlines serves as a microcosm for the challenges faced by national flag carriers globally. Many such airlines are still emerging from the "Covid era" with weakened balance sheets, only to be met by a "high-cost era" defined by energy inflation and labor shortages. The ability of Malaysia Airlines to weather this storm will be a test case for whether state-owned carriers can truly compete in a deregulated, high-efficiency, and high-volatility market.
As the airline approaches its next fiscal reporting cycle, stakeholders will be looking for signs of margin expansion. Specifically, analysts will be tracking the "cost per available seat kilometer" (CASK) versus "revenue per available seat kilometer" (RASK) spread. If this spread does not widen in the coming quarters, the narrative surrounding the carrier may shift from one of "successful restructuring" to "structural stagnation."
In conclusion, Malaysia Airlines stands at a juncture where the successes of the past four years are no longer sufficient to guarantee the success of the next four. The combination of fuel price shocks, a consolidated and aggressive regional competitor, and the looming necessity of a capital-intensive fleet renewal represents a "perfect storm." Whether the airline can navigate these headwinds will depend on its ability to leverage its unique position as a national icon while simultaneously adopting the ruthless operational efficiency of its low-cost competitors. The path forward is narrow, and the margin for error has effectively vanished.




 Lukman Taruna Persada Ramadan

 Tatiana Tantri Indah Sari

 Anjar Salim


 Dwi Wanna
