Gabriela Annisa
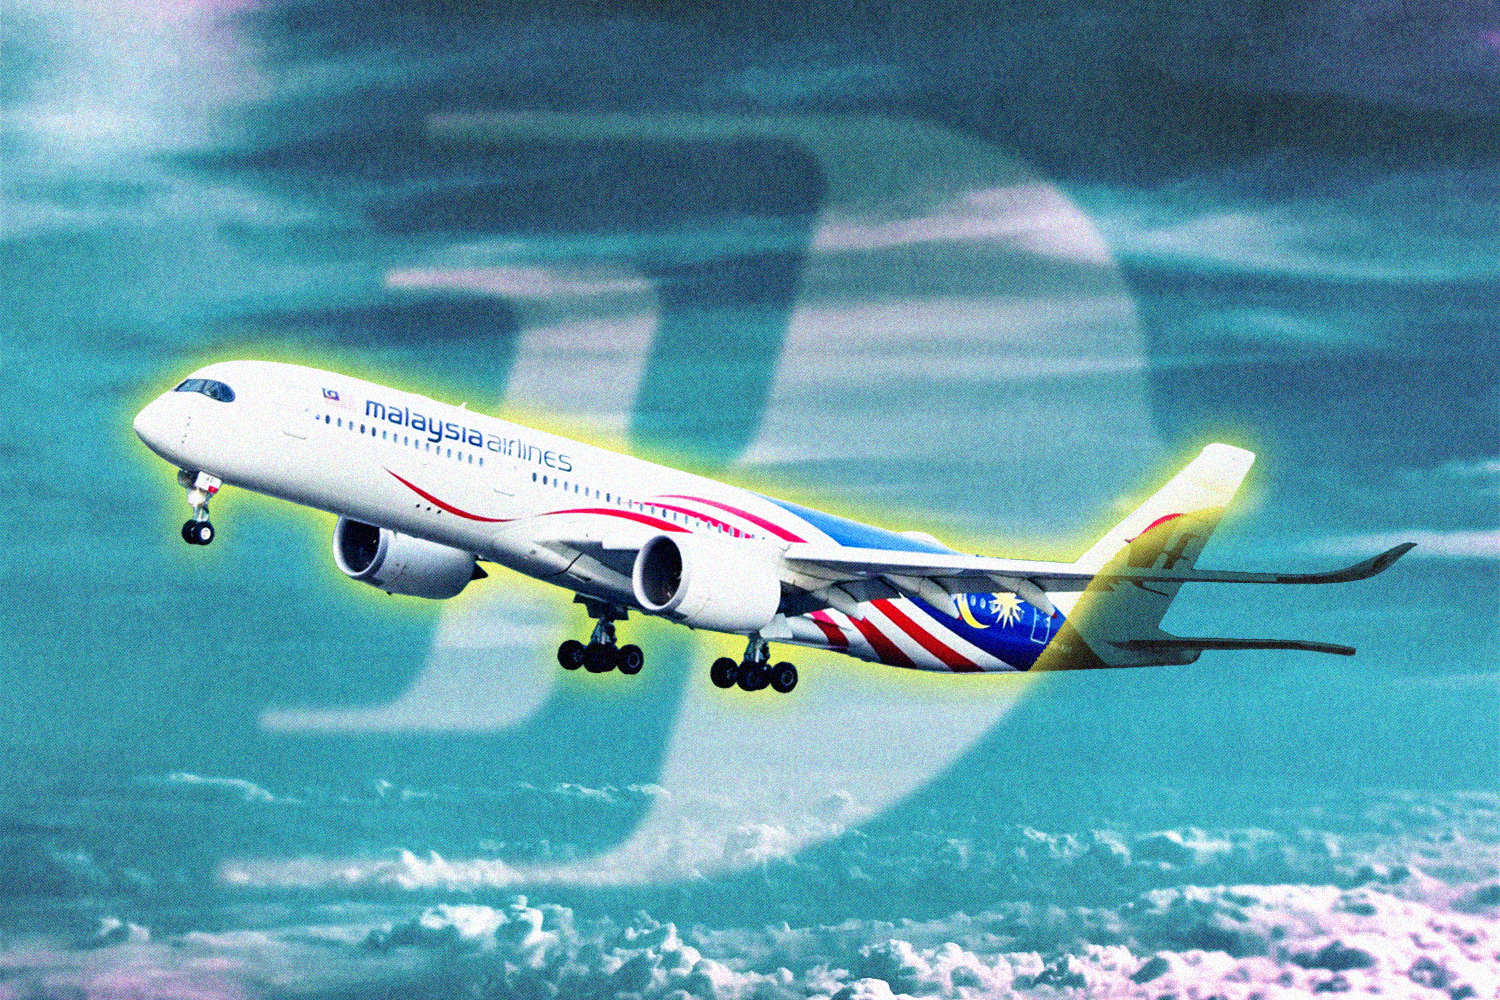
Malaysia Airlines has successfully navigated a four-year streak of profitability following its comprehensive post-pandemic restructuring, yet the carrier now finds itself at a precarious strategic juncture. Despite these consecutive years of positive earnings, the airline’s net profit margin remains razor-thin, hovering at less than 1%. This marginal performance leaves the national flag carrier with negligible financial buffers to absorb significant external shocks, most notably a staggering 90% year-over-year surge in fuel costs. As the airline attempts to balance these fiscal pressures, it must simultaneously contend with a reinvigorated AirAsia and finalize a critical widebody aircraft order that will dictate the trajectory of its long-haul network for the coming decade.
The Path to Recovery: A Chronology of Restructuring
The current state of Malaysia Airlines is the result of a deliberate, multi-year pivot following the global collapse of air travel in 2020. The carrier, which had already been under intense scrutiny regarding its financial viability for much of the previous decade, utilized the pandemic-induced hiatus to aggressively prune its balance sheet and streamline its operational model.
By early 2021, the airline initiated a comprehensive debt restructuring scheme that gained court approval, allowing it to reduce its total liabilities by over $3.5 billion. This period marked the beginning of a transformation led by the Malaysia Aviation Group (MAG). Throughout 2022 and 2023, the focus shifted toward capital discipline and a pivot toward higher-yield segments. During this time, the airline relied heavily on its auxiliary businesses, specifically cargo services—which thrived during the supply chain disruptions of the post-Covid era—and its internal maintenance, repair, and overhaul (MRO) divisions. These segments acted as the primary engines of profitability while passenger travel demand remained volatile and suppressed.
Financial Realities: The Efficiency Paradox
While the headline figure of four years of profitability is an achievement for an airline that has historically struggled with structural deficits, industry analysts point to the composition of these profits as a cause for concern. A net margin of under 1% indicates that the airline is operating with virtually no margin for error.
Data from the 2026 fiscal reports indicate that while passenger load factors have returned to pre-pandemic levels, the yield per available seat kilometer (ASK) has been offset by inflationary pressures. The 90% spike in fuel costs represents the most significant threat to the airline’s continued solvency. Jet fuel, which typically accounts for 25% to 35% of an airline’s total operating expenditure, has become a volatile variable that threatens to erode the modest gains made in the last 48 months. Without the diversification provided by its non-passenger business units, the airline would likely have remained in a deficit during the current fiscal year.
The Competitive Landscape: The AirAsia Factor
The external environment in the Southeast Asian aviation market has shifted significantly. AirAsia, long the dominant low-cost carrier in the region, has emerged from its own restructuring phase with a renewed focus on consolidation. By reorganizing its various regional entities into a single, cohesive airline group, AirAsia has gained significant leverage in procurement, labor management, and network planning.
For Malaysia Airlines, this creates a two-front war. On the domestic and short-haul international routes, it faces an increasingly lean and aggressive competitor that can undercut its pricing while maintaining lower unit costs. On the long-haul front, the airline must compete with global carriers that have larger fleets and greater economies of scale. The challenge for Malaysia Airlines is to differentiate its premium offering sufficiently to justify its price point, all while attempting to lower its own unit costs to compete with the sheer efficiency of the low-cost model.
The Strategic Widebody Dilemma
Perhaps the most consequential decision facing the airline’s leadership in late 2026 is the pending selection of a new widebody fleet. This acquisition is not merely a logistical upgrade; it is a fundamental statement of intent regarding the carrier’s network strategy.
The airline is currently evaluating options that will replace its aging fleet of A350s and A330s. The choice between the Airbus A350-1000, the Boeing 787-10, or potential additions of the 777X will dictate the airline’s fuel burn rates, maintenance costs, and cabin configurations for the next 15 years. Given the current narrow profit margins, the capital expenditure required for such a fleet renewal is immense.
Industry experts suggest that the airline’s choice will likely favor fuel efficiency and range over sheer capacity. By opting for aircraft that allow for lower per-seat trip costs, the airline hopes to improve its margins on high-density routes to Europe and North Asia. However, the financing of such a massive order in an environment of high interest rates and thin cash reserves remains a significant hurdle.
Stakeholder Perspectives and Market Reactions
While official commentary from Malaysia Aviation Group has remained cautious, insiders suggest that the board is prioritizing "sustainable growth over rapid expansion." In recent briefings, executive leadership emphasized the importance of the airline’s "Long Term Business Plan 2.0," which focuses on digital transformation, customer experience, and the strengthening of the airline’s MRO capabilities.
Investors and analysts remain mixed. While the achievement of four years of profitability is viewed as a testament to successful crisis management, the lack of a strong, consistent net margin makes the stock a difficult play. Credit rating agencies have maintained a "stable" outlook, acknowledging the government’s implicit support of the national carrier, yet they have cautioned that any sustained period of high fuel prices without a corresponding increase in ticket yields could lead to a downgrade.
Broader Implications for the Southeast Asian Aviation Sector
The situation at Malaysia Airlines serves as a microcosm for the broader Southeast Asian aviation sector. As the region recovers, the legacy carriers are finding that the old business models—high-cost structures and heavy reliance on traditional hub-and-spoke networks—are increasingly unsustainable in the face of persistent inflation and agile low-cost competition.
The success or failure of Malaysia Airlines over the next 24 months will likely set a precedent for how other state-owned airlines in the region manage their own transitions. If Malaysia Airlines can successfully leverage its cargo and maintenance arms to cross-subsidize its passenger operations while modernizing its fleet, it may offer a roadmap for other flag carriers. Conversely, if the fuel cost burden proves too great, the region may see a further push toward industry consolidation, potentially involving state-led mergers or deeper integration between regional players.
Looking Ahead: The Path to Sustainability
As the airline enters the final quarter of 2026, the focus will undoubtedly be on cost containment and yield management. The airline is expected to implement more sophisticated dynamic pricing models to capture higher revenues from premium travelers while attempting to stabilize its fuel hedging strategies.
The airline’s long-term sustainability hinges on two factors: the successful integration of its new fleet and the ability to maintain its position as a preferred premium carrier in a region that is increasingly dominated by cost-conscious travel. While the return to profitability was the first hurdle, the challenge of maintaining that profitability amidst global economic headwinds is far greater. The coming year will be defined by the airline’s ability to turn its precarious 1% margin into a robust buffer, ensuring that the next chapter of its history is written with more fiscal certainty than the last.

 Anjar Salim
 Chandra Hamzah
 Tatiana Tantri Indah Sari
 Budi Mulyono
 Lukman Taruna Persada Ramadan