
 Gabriela Annisa
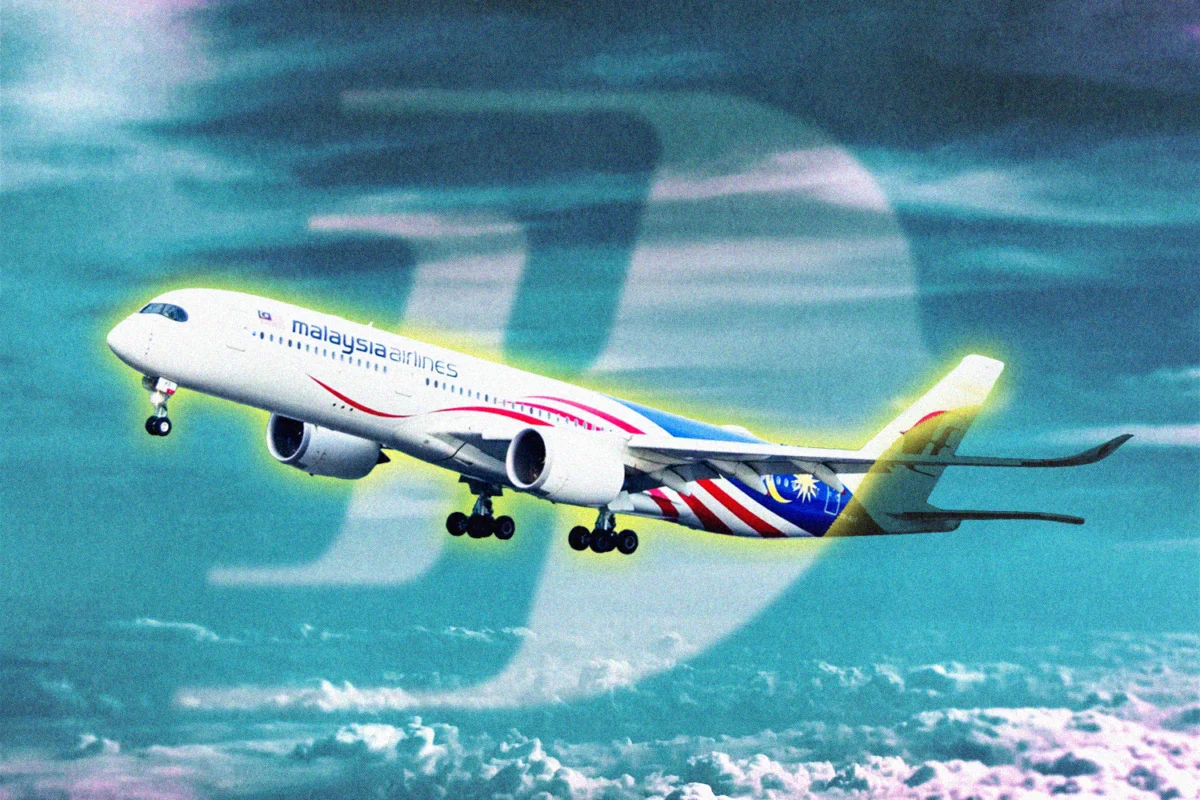
The financial trajectory of Malaysia Airlines has reached a critical inflection point in September 2026, as the flag carrier marks its fourth consecutive year of profitability following the extensive restructuring necessitated by the global pandemic. While this streak represents a significant turnaround from the carrier’s historical turbulence, the underlying metrics reveal a fragile foundation. With a net profit margin currently hovering below the 1% threshold, the airline finds itself in a precarious position, struggling to balance operational growth against an aggressive surge in global energy costs. Recent financial disclosures indicate that fuel expenditures have spiked by 90% year-over-year, effectively neutralizing the gains made through post-Covid recovery efforts.
A Decade of Transformation and Restructuring
The story of Malaysia Airlines in the 2020s is one of drastic recalibration. Following years of financial instability and the well-documented tragedies of 2014, the airline entered the decade facing the unprecedented systemic shock of the Covid-19 pandemic. The resulting restructuring process was not merely a survival tactic but a fundamental reassessment of the carrier’s business model.
By shedding unprofitable routes and renegotiating lease agreements, the airline managed to stabilize its balance sheet. However, the internal data suggests that the profitability achieved over the last four years was driven less by passenger load factors and more by the strength of the airline’s auxiliary business units, specifically its cargo division and its MRO (Maintenance, Repair, and Overhaul) arm. As global supply chains faced massive disruptions during the recovery period, Malaysia Airlines leveraged its existing infrastructure to capitalize on the high demand for air freight. This strategic diversification provided a vital buffer, but as cargo yields normalize and competition returns to pre-pandemic intensity, the core airline business must now stand on its own merits.
The Macroeconomic Challenge: The Fuel Shock
The most immediate threat to the carrier’s stability is the unprecedented volatility in jet fuel prices. A 90% increase in fuel costs year-over-year represents a catastrophic shift in the operating environment for a legacy carrier with thin margins. In the airline industry, fuel is typically the largest variable expense, and for a company operating with a net margin of less than 1%, such a massive escalation in costs leaves virtually no room for error.
To mitigate these pressures, the airline has been forced to implement aggressive fuel surcharges and streamline flight paths for greater efficiency. However, these measures carry the risk of suppressing demand in a price-sensitive market. Economists monitoring the Asia-Pacific region note that while travel appetite remains robust, the elasticity of demand is beginning to show signs of strain. If the carrier passes the full burden of fuel costs onto the consumer, it risks losing market share to low-cost competitors who operate with lower overheads and more modern, fuel-efficient fleets.
The Resurgence of AirAsia
Complicating the landscape for Malaysia Airlines is the emergence of a leaner, more formidable AirAsia. Having spent the mid-2020s consolidating its various regional entities into a single, cohesive airline brand, AirAsia is now positioned to exert significant pricing pressure on domestic and regional international routes. The "rebuilt" AirAsia has utilized its scale to command better pricing on fuel hedging and fleet maintenance, creating a cost-base advantage that is difficult for Malaysia Airlines to replicate.
The rivalry is no longer just about seat capacity; it is a battle for the "middle-market" traveler. Malaysia Airlines, which has historically occupied the premium segment, is finding that its traditional value proposition—offering full-service amenities—is increasingly being challenged by low-cost carriers offering "a la carte" premium upgrades. This convergence of service levels is forcing management to make difficult choices regarding fleet utilization and network connectivity.
Fleet Modernization: The Widebody Order
Central to the airline’s long-term strategy is a pending widebody aircraft order, a decision that will define its competitive positioning for the next decade. Industry analysts suggest that the choice between the latest-generation Airbus A350s or Boeing 787 Dreamliners is not merely a hardware decision, but a fundamental choice regarding the airline’s network footprint.
The current strategy appears to favor a "hub-and-spoke" model centered on Kuala Lumpur, leveraging the city’s geographic location to connect travelers between Europe and Australia. To maintain this, the airline requires widebody aircraft that can offer superior range and fuel efficiency. If the carrier chooses a fleet that is too small, it risks being unable to meet peak demand; if it over-orders, it risks being saddled with debt in an environment where interest rates remain elevated. The capital expenditure required for this renewal program will undoubtedly test the airline’s credit rating and its relationship with institutional lenders.
Financial Sustainability and Future Outlook
The reality of a net margin under 1% implies that the company is effectively "breaking even" on a massive scale. For the aviation industry, such thin margins are typical for legacy carriers, but they leave the airline vulnerable to even minor exogenous shocks—whether they be geopolitical tensions in the South China Sea, further spikes in oil prices, or a sudden downturn in the Malaysian economy.
Market observers have pointed out that the airline’s reliance on maintenance and cargo revenues is a double-edged sword. While these segments have provided stability, they also hide the underlying inefficiency of the passenger airline. For the organization to achieve long-term sustainability, it must demonstrate an ability to generate consistent profit through its core passenger business. This will likely require further consolidation of routes, deeper integration with the Oneworld alliance, and perhaps a more aggressive push into high-margin ancillary revenue streams such as loyalty program monetization and premium cabin upgrades.
Official Stance and Market Response
While official comments from Malaysia Airlines leadership have remained guarded, internal communications suggest a shift toward "fiscal discipline and operational agility." The company has signaled a commitment to maintaining its network integrity while simultaneously seeking partnerships that reduce the cost of distribution. Investors, however, remain cautious. The stock performance of the airline’s parent entity has mirrored the broader uncertainty in the Southeast Asian transport sector, with institutional holders waiting for clear evidence that the carrier can decouple its profitability from the volatile cargo market.
The challenge ahead for the management team is clear: they must successfully navigate the transition from a post-pandemic recovery phase to a new era of high-cost, high-competition operations. The next 18 months will be critical, particularly as the new widebody fleet begins to arrive and the airline faces the full brunt of a consolidated AirAsia.
Conclusion: A Critical Juncture
The story of Malaysia Airlines is reflective of a broader struggle faced by many flag carriers in the Asia-Pacific region. As they transition out of the era of government-subsidized survival, they must prove their viability in a market that is increasingly dominated by efficiency-driven business models. The airline has succeeded in avoiding the collapse that many predicted four years ago, but survival is not synonymous with success. To reach the next stage of its evolution, Malaysia Airlines must expand its margins, modernize its fleet, and find a way to thrive in a landscape where fuel costs are no longer a temporary hurdle, but a permanent feature of the business environment. The path forward requires a delicate balance of aggressive innovation and conservative financial management—a tightrope walk that will determine whether the carrier remains a significant player on the world stage or fades into a regional footnote.



 Diana Nuri Rohmawati

 Lukman Taruna Persada Ramadan

 Tatiana Tantri Indah Sari

 Anjar Salim

