
 Gabriela Annisa
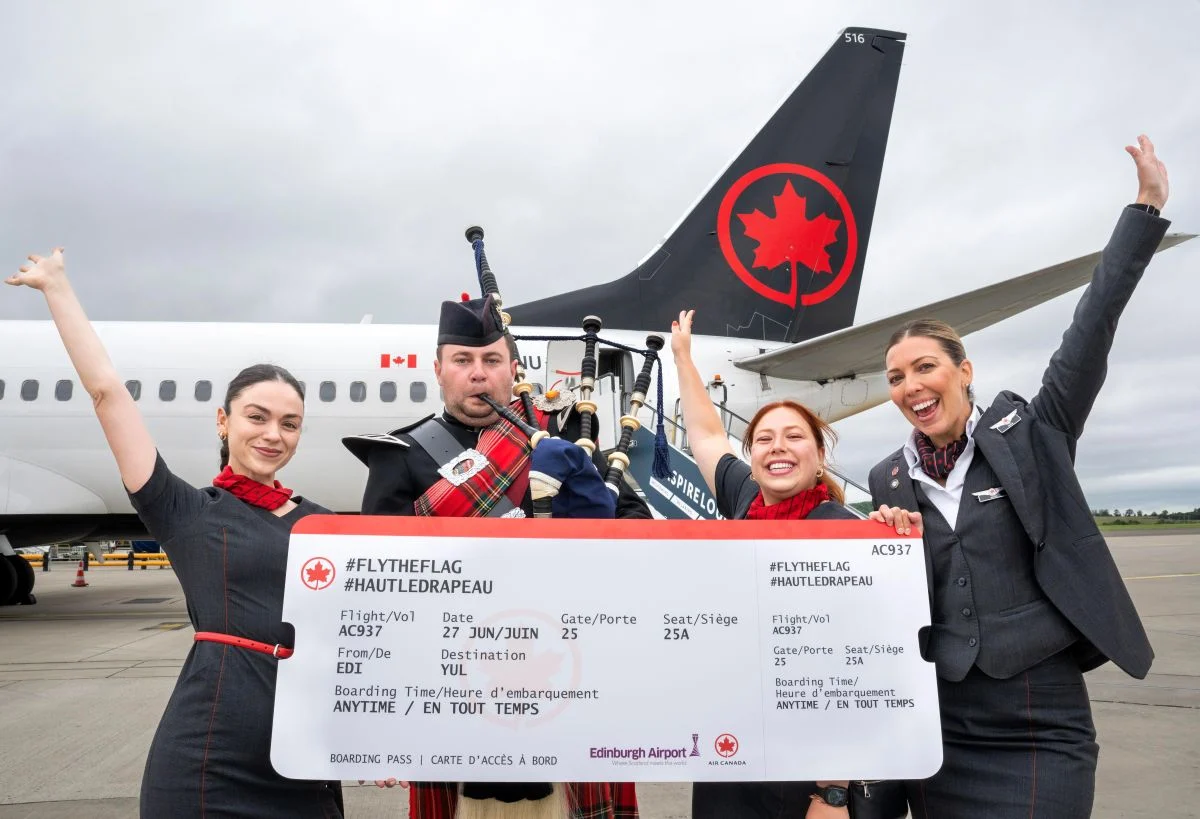
Air Canada stands at a critical juncture as Michael Rousseau’s leadership team navigates a complex transition involving the integration of new operational strategies under the guidance of executive leadership, including the influence of strategic appointments like Anko van der Werff. Simultaneously, the global aviation landscape is shifting, with China’s "Big Three" carriers—Air China, China Southern Airlines, and China Eastern Airlines—reporting significant financial headwinds in the second quarter of 2024. This analysis explores the dual pressures of regional growth opportunities and macroeconomic volatility facing the airline industry.
The Strategic Evolution of Air Canada
Air Canada’s current operational strategy is defined by a delicate balance between aggressive expansion and the necessity of maintaining margins in a high-cost environment. The appointment of seasoned leadership figures within the airline’s broader ecosystem has signaled a pivot toward optimizing long-haul connectivity while bolstering the domestic footprint.
Historically, Air Canada has relied on its robust Star Alliance network and the strategic advantage of its Toronto, Vancouver, and Montreal hubs to capture trans-Pacific and trans-Atlantic traffic. However, the post-pandemic recovery has been uneven. While demand for international premium travel remains resilient, the airline faces inflationary pressures, specifically regarding labor costs and fuel volatility.
The internal focus under the current management regime centers on fleet modernization. By replacing older, less fuel-efficient aircraft with newer, long-range models like the Airbus A321XLR and the Boeing 787 Dreamliner, the carrier is attempting to lower its unit costs. The integration of these assets is not merely a logistical challenge; it is a fundamental shift in how the airline manages capacity on thinner, long-haul routes that were previously deemed too costly to operate. Analysts note that this strategy is designed to provide Air Canada with the flexibility to pivot between markets as demand fluctuates, a necessity in a volatile global economy.
Financial Performance and Market Realities
The Skift Travel 200 (ST200) index, which tracks the performance of nearly 200 travel companies with a combined market capitalization exceeding $1 trillion, provides a sobering look at the airline sector’s year-to-date performance. While the broader travel industry has seen growth in the cruises and tours segments, network carriers have experienced compressed valuations due to increased debt loads and the tapering of the post-pandemic "revenge travel" boom.
For Air Canada, the data suggests that investors are closely monitoring the company’s debt-to-equity ratio. Having taken on significant liabilities to survive the 2020-2021 period, the airline’s primary objective has been deleveraging. Every strategic move, from the expansion of loyalty programs to the adjustment of trans-border capacity, is filtered through the lens of balance sheet health.
China’s Aviation Sector: A Second Quarter Slump
While Western carriers grapple with labor and supply chain issues, the Chinese aviation market is contending with a different set of macroeconomic challenges. The second quarter of 2024 proved particularly difficult for the country’s "Big Three"—Air China, China Southern, and China Eastern—as they struggled to translate increased passenger volumes into bottom-line profitability.
Several factors have contributed to this decline. First, the domestic Chinese market, which historically served as the bedrock of these carriers’ financial stability, has seen a saturation of capacity. Airlines responded to the reopening of borders by dumping capacity into the domestic market, leading to a "yield war" that drove average ticket prices down. Despite high load factors, the revenue per available seat mile (RASM) has struggled to return to 2019 levels.
Second, the slow rebound of international business travel has hampered the recovery of the high-margin corporate segment. While leisure travel to neighboring Asian destinations has picked up, the long-haul business routes that typically generate significant revenue for the Big Three have remained subdued. Geopolitical tensions and the slow issuance of visas have further restricted the flow of international travelers into China, limiting the recovery of inbound tourism.
Third, the persistent weakness in the Chinese yuan against the U.S. dollar has exacerbated the financial burden for these carriers. Because a significant portion of aviation expenses—such as jet fuel, aircraft leasing costs, and engine maintenance—is denominated in U.S. dollars, the currency depreciation has effectively increased operating costs while domestic revenues remained stagnant.
A Chronology of Industry Volatility
The current state of the aviation industry is best understood through the timeline of the last four years:
- 2020-2021 (The Preservation Phase): Global aviation effectively ground to a halt. Carriers, including Air Canada and the Chinese Big Three, received varying levels of government assistance to prevent systemic collapse.
- 2022 (The Rebound Phase): The lifting of travel restrictions triggered a surge in demand that outpaced the industry’s ability to scale operations, leading to mass cancellations and operational chaos.
- 2023 (The Price Correction Phase): Airlines benefited from high demand and limited supply, leading to record-breaking yields. Investors grew optimistic, driving the ST200 index upward.
- 2024 (The Normalization Phase): As capacity returned to pre-pandemic levels, supply began to outstrip demand in specific markets. Operational costs rose, and the "easy gains" of the post-pandemic era began to fade, leading to the current market caution.
Official Perspectives and Market Implications
Industry observers, including analysts at major financial firms, have noted that the divergence between the North American and Chinese aviation markets is emblematic of broader regional trends. In North America, the focus is on "premiumization"—the effort to monetize business and premium-economy classes to offset rising labor costs. In contrast, the Chinese market is currently focused on "volume stabilization," where carriers are attempting to rationalize their networks to prevent further erosion of ticket prices.
According to statements from industry trade groups, the global aviation sector is expected to remain in a state of flux through the remainder of the fiscal year. Airlines that prioritize agility in their network planning are expected to outperform those that remain tied to legacy routes that are no longer supported by current passenger demographics.
The implications for investors are clear: the era of broad-based airline sector growth is giving way to a period of stock picking, where individual airline strategy, fleet age, and geographical exposure are the primary drivers of performance. For Air Canada, the challenge remains the successful execution of its long-haul strategy without overextending its capital resources. For the Chinese carriers, the challenge is structural; they must wait for a broader macroeconomic recovery in the Chinese economy to provide the necessary support for international premium travel.
Conclusion
The state of global aviation today is defined by the tension between resilience and restriction. Air Canada’s strategic maneuvers represent an effort to capitalize on the strengths of the North American market, even as it faces global headwinds. Meanwhile, the performance of the Chinese Big Three serves as a warning that even with high passenger volumes, the absence of pricing power and the pressure of a weak currency can erode financial gains. As the industry moves into the latter half of the year, the performance of the ST200 will likely continue to reflect these diverging realities, with investors favoring airlines that demonstrate fiscal discipline and the capacity to adapt to a shifting global landscape. The aviation sector, having weathered the storm of the pandemic, now finds itself in a race to adapt to the new, more demanding requirements of a globalized, yet increasingly fragmented, economy.



 Diana Nuri Rohmawati

 Lukman Taruna Persada Ramadan

 Tatiana Tantri Indah Sari

 Anjar Salim

