
 Tatiana Tantri Indah Sari
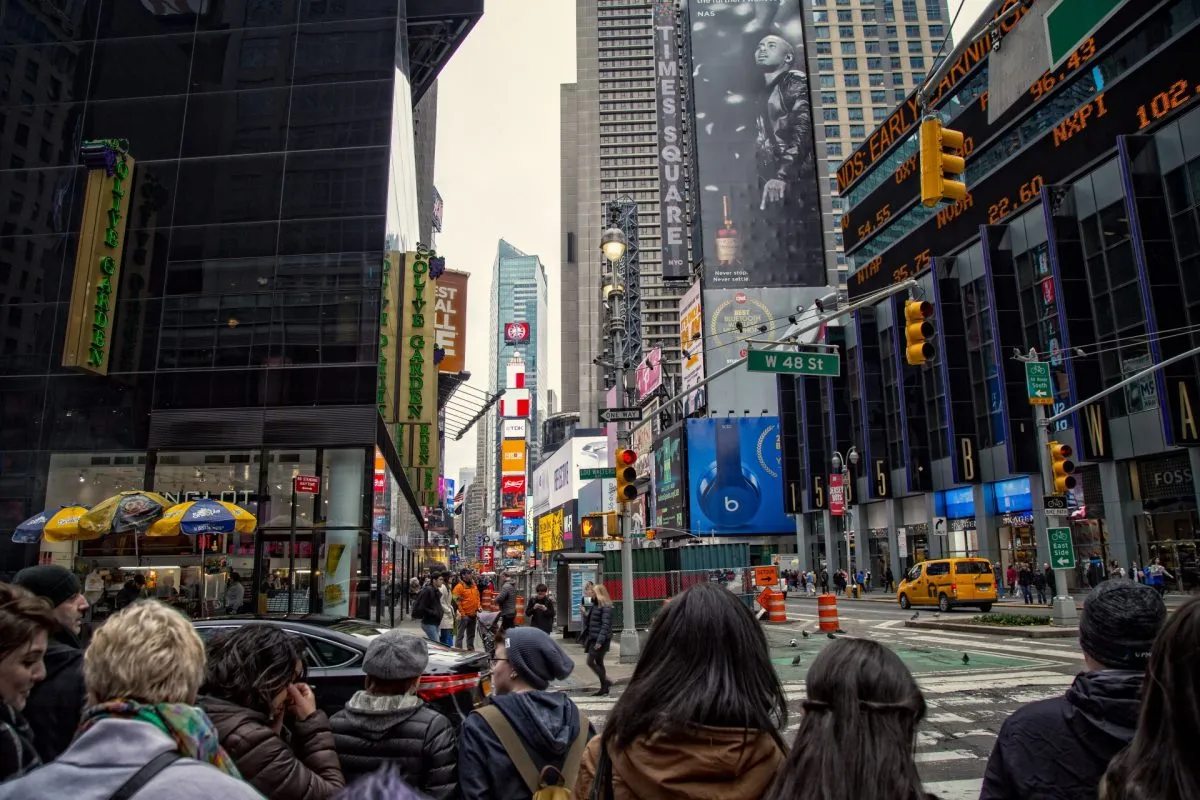
The United States travel and tourism sector is facing an unprecedented and deeply concerning downturn following a summer season that significantly underperformed compared to optimistic projections. According to data released on Thursday by the National Travel and Tourism Office (NTTO), the U.S. received close to 3.1 million international visitors in August, marking a sharp 11.8 percent year-over-year decline. This alarming contraction follows a troubling 7 percent decrease in inbound tourism recorded just a month prior in July. What the industry had initially anticipated would be a banner season characterized by robust post-pandemic international travel recovery has instead materialized into a prolonged slump, compounding economic pressures on hospitality, aviation, retail, and entertainment sectors nationwide.
The disappointing performance of the summer tourism calendar underscores structural and macroeconomic headwinds facing the American travel market. Hopes for a lucrative tourism surge were particularly high given major global events scheduled across North America, including high-profile athletic competitions. However, visitor numbers for the FIFA World Cup preliminary events and related summer sports tourism fell noticeably short of expectations. Rather than fueling an economic windfall, the peak summer months revealed a deepening weariness among international travelers, driven by persistent inflationary pressures, unfavorable exchange rates, stringent visa processing backlogs, and intensifying global competition for tourist dollars.
Chronology of a Disappointing Summer Season
The trajectory of the summer 2024 tourism season began with high expectations among travel industry stakeholders, hoteliers, and destination marketing organizations. As the spring shoulder season transitioned into June, initial forecasts from various trade associations predicted double-digit growth in international arrivals, fueled by pent-up travel demand and the gradual reopening of long-haul flight routes. However, early indicators in June already pointed toward softening momentum, as flight capacity adjustments and rising ground-handling costs began to price out budget-conscious international tourists.
By July, the slowdown transformed into a clear downward trend. NTTO figures released at the end of the summer’s second month confirmed a 7 percent year-over-year drop in inbound visitors. Industry analysts initially attributed the July dip to seasonal travel shifts and the timing of school holidays in core European and Asian markets. Nevertheless, the severity of the August decline—surging to an 11.8 percent contraction—shattered any lingering hopes that the summer slump was a temporary aberration. The consecutive monthly declines have forced travel executives and economic forecasters to recalibrate their outlooks for the remainder of the year, raising urgent questions about the competitiveness of the United States as a premier global destination.
Comprehensive Regional Breakdown of the Decline
The NTTO dataset highlights that the contraction in inbound tourism was not isolated to a single geographic region or market segment, but rather represented a broad-based retreat across all major international points of origin. Arrivals to the United States declined across every global region, signaling a systemic shift in international travel patterns.
The most severe drops were registered in long-haul markets, which typically generate the highest per-visitor economic impact through extended stays and higher spending on lodging, dining, and retail. Africa experienced the steepest decline, with visitor numbers plummeting by 25.5 percent compared to the same period in the previous year. Central America followed closely behind, recording a 20.6 percent reduction in arrivals. Western Europe, traditionally one of the most reliable and lucrative source markets for American tourism, saw a dramatic 14.8 percent decrease in visitors.
Asia, which has experienced a slower and more complex post-pandemic recovery due to delayed flight capacity restorations and lingering visa appointment backlogs, also contributed significantly to the overall downward trend. Even neighboring Canada and Mexico, which historically anchor U.S. cross-border travel volume, reported softening numbers as economic uncertainties prompted regional travelers to rein in discretionary spending. The uniformity of the decline across diverse economic and geographic landscapes indicates that domestic U.S. travel barriers are superseding regional economic idiosyncrasies.
Official Responses and Stakeholder Reactions
In the wake of the NTTO report, travel industry leaders, trade associations, and municipal tourism boards have expressed growing alarm, calling for coordinated federal action to address the underlying causes of the slump. Representatives from the U.S. Travel Association have emphasized the urgent need to streamline the visa application process, citing excessively long wait times for interviews at U.S. embassies and consulates in key growth markets such as Latin America and parts of Asia. Industry advocates argue that prospective travelers are increasingly opting for alternative destinations—such as European Union member states, Japan, and the United Kingdom—where entry procedures are perceived as more welcoming and efficient.
Hospitality executives during recent earnings calls have also pointed to the strength of the U.S. dollar as a formidable deterrent for international visitors. A strong dollar makes American hotels, restaurants, and attractions comparatively expensive for foreign nationals, stretching travel budgets and discouraging extended itineraries. Furthermore, commercial aviation stakeholders have noted that transatlantic and transpacific airfares remain elevated due to constrained aircraft deliveries, high jet fuel costs, and ongoing labor negotiations, further dampening long-haul travel demand.
Destination marketing organizations in major metropolitan hubs—including New York City, Los Angeles, Orlando, and Chicago—are currently pivoting their promotional strategies. Rather than relying on broad, traditional advertising campaigns, these organizations are intensifying targeted digital marketing efforts, partnering with international tour operators, and offering specialized incentive packages to entice travelers from resilient market niches. However, local tourism boards acknowledge that regional marketing interventions can only do so much to counter macroeconomic headwinds and federal policy bottlenecks.
Economic Implications and Broader Market Impact
The ongoing contraction in inbound international tourism carries significant economic implications for the broader United States economy. International visitors are among the highest-spending consumers in the American economy, injecting billions of dollars annually into local communities, supporting millions of jobs in retail, hospitality, transportation, and entertainment, and generating critical tax revenues for state and local governments.
When international arrivals decline precipitously, the ripple effects are felt far beyond hotels and airlines. Independent restaurants, museums, tour operators, rideshare drivers, and small retail boutiques dependent on tourist foot traffic face squeezed profit margins and reduced revenue streams. In secondary and tertiary markets that have increasingly relied on international tourism diversification to spur local economic development, the downturn threatens employment stability and wage growth within the service sector.
Furthermore, the widening trade deficit in travel services could impact the broader macroeconomic picture. International travel spending in the U.S. is traditionally classified as an export service, helping to offset trade imbalances in manufactured goods. A sustained reduction in visitor spending weakens this vital export pillar, adding to the structural economic challenges facing the nation.
Fact-Based Analysis and Future Outlook
Analyzing the trajectory of inbound tourism heading into the autumn and winter seasons, economists and travel industry analysts suggest that a rapid rebound is unlikely without targeted structural interventions. The convergence of high travel costs, persistent foreign exchange disparities, and cumbersome bureaucratic hurdles continues to erode the U.S. share of the global travel market.
To reverse these trends, travel sector stakeholders are increasingly pressing federal policymakers to prioritize tourism as a critical component of national economic strategy. Key recommendations include expanding the Visa Waiver Program to additional qualified countries, deploying temporary staffing resources to clear consular interview backlogs, and funding national marketing campaigns coordinated through bodies like Brand USA to reassure international audiences that the United States remains an accessible, welcoming, and competitive destination.
As the industry prepares for the upcoming holiday travel period, the disappointing data from August serves as a stark wake-up call. Without concerted policy reform, strategic promotional investments, and a concerted effort to mitigate the cost barriers facing international travelers, the U.S. travel sector risks forfeiting its preeminent position in the global tourism landscape, leaving businesses dependent on foreign visitors to navigate an extended period of financial vulnerability.

 Anjar Salim
 Dwi Wanna
 Chandra Hamzah
 Walid Sujud Trenggono
 Cholid Fahmi Thalib
