Gabriela Annisa
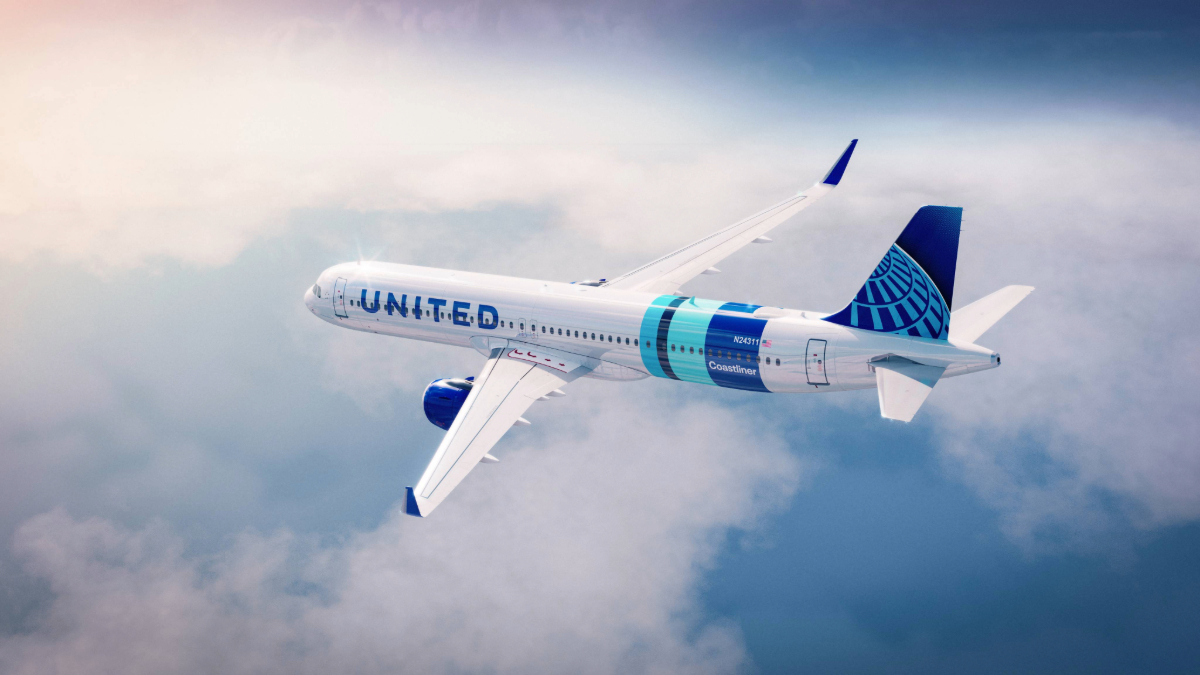
The recent announcement of expanded transatlantic service by United Airlines and American Airlines marks a significant pivot in the long-haul strategy of major U.S. carriers. By leveraging the technological capabilities of the Airbus A321XLR, these airlines are shifting away from the traditional reliance on high-capacity, wide-body aircraft to connect major hubs, opting instead for point-to-point routes that target niche demand and high-yield premium passengers. This strategic recalibration, discussed extensively in the latest edition of The Airline Weekly Lounge, reflects a broader evolution in how network carriers approach international capacity management in an era of shifting corporate travel patterns and increased leisure demand.
The Strategic Shift: From Hub-and-Spoke to Point-to-Point
For decades, the transatlantic market was defined by the hub-and-spoke model. Large aircraft, such as the Boeing 777 or Airbus A350, were deployed from central "super-hubs"—such as New York (JFK/EWR), Chicago (ORD), and London (LHR)—to ensure high load factors. However, the post-pandemic recovery has introduced volatility in business travel, forcing airlines to reconsider the efficiency of operating massive, 300-seat jets on secondary routes.
United Airlines and American Airlines are now increasingly utilizing the Airbus A321XLR, a narrow-body aircraft with an extended range, to bridge the gap between regional demand and global connectivity. By deploying a smaller airframe on routes that previously lacked sufficient volume for wide-body economics, airlines can maintain daily frequencies that are attractive to business travelers while minimizing the risk of flying empty seats. This allows carriers to test new markets—such as mid-sized European cities or secondary U.S. gateways—without the massive overhead associated with larger fleets.
Chronology of the Narrow-Body Revolution
The integration of narrow-body aircraft into long-haul service is not a sudden development but the culmination of a decade of aerospace innovation.
- 2014-2015: Boeing introduces the 737 MAX and Airbus responds with the A320neo family, signaling a shift toward more fuel-efficient engines.
- 2019: Airbus officially launches the A321XLR at the Paris Air Show, promising a range of up to 4,700 nautical miles, effectively allowing "transatlantic range" for a single-aisle jet.
- 2022-2023: As global travel demand rebounds, major carriers confirm massive orders for the A321XLR, viewing it as the primary tool to replace aging Boeing 757 fleets that previously operated long-thin routes.
- 2024: United and American announce specific service expansions utilizing these aircraft, marking the formal deployment of the XLR into their core transatlantic portfolios.
The A321XLR’s arrival comes at a time when airlines are desperate for operational flexibility. The aircraft burns significantly less fuel per trip than a wide-body, offering a lower "trip cost" that makes secondary routes profitable even if they do not fill a massive cabin.
Supporting Data: Performance of the Airline Sector
The financial health of these airlines remains closely tied to their ability to navigate these fleet transitions. According to the Skift Travel 200 (ST200), which aggregates the performance of nearly 200 travel companies, the airline sector has faced a complex year-to-date trajectory. While network carriers have seen robust demand in premium cabins, the sector as a whole is navigating headwinds including fluctuating jet fuel prices, labor costs, and a tightening regulatory environment.
The ST200 data indicates that while the cruise and tour sectors have seen rapid acceleration, network carriers are currently focused on margin protection. The decision to invest in the A321XLR is a direct hedge against this volatility. By reducing the size of the aircraft on specific routes, airlines are essentially "right-sizing" their capacity to match the current demand environment, a practice that has historically led to more stable stock performance for those companies that execute it effectively.
Premium Demand: The Foundation of Profitability
A central question regarding the A321XLR strategy is whether the aircraft’s economic viability is overly dependent on premium-cabin demand. Because narrow-body aircraft offer fewer total seats, the revenue per seat must be higher to cover the fixed costs of international operations. Consequently, airlines have configured these jets with a heavy emphasis on lie-flat business class seats and premium economy.
Analysts suggest this is a calculated risk. If corporate travel fully recovers to pre-2019 levels, the A321XLR will be a goldmine for airlines, as it allows them to offer premium products on routes where a 777 would be too expensive to fly. However, if premium demand softens—perhaps due to a macroeconomic downturn or a permanent shift toward virtual conferencing—the lack of an "economy-heavy" cushion could pose a threat to the route’s profitability. Despite these concerns, airline executives have largely signaled confidence, noting that the "premium leisure" segment has shown remarkable resilience even when business travel lags.
Official Perspectives and Market Reactions
While official press releases from United and American emphasize the "customer experience" and "new destination opportunities," industry insiders point to the underlying financial logic. A spokesperson for a major aviation consultancy noted that the A321XLR represents a "de-risking" of international expansion. By lowering the entry cost for a new route, the airline can iterate its network more rapidly. If a route fails, the airline can redeploy the narrow-body asset elsewhere with significantly less impact on its overall financial position than it would face with an underutilized wide-body.
Furthermore, aircraft manufacturers are highlighting the fuel efficiency gains. The A321XLR’s reduced emissions profile is becoming an increasingly important metric for investors who are tracking ESG (Environmental, Social, and Governance) targets. By operating these smaller, more efficient jets, airlines can claim a lower carbon footprint per passenger, which is becoming a vital component of modern investor relations.
Broader Impact and Industry Implications
The ripple effects of this transatlantic shift are expected to be felt across the aviation ecosystem. Firstly, airport authorities in secondary cities are seeing renewed interest from U.S. carriers, as these airports are now viable candidates for non-stop U.S. service. This could lead to a decentralization of transatlantic traffic, moving away from the dominance of hubs like Heathrow or Frankfurt.
Secondly, the competitive landscape is shifting. Low-cost carriers (LCCs) have historically dominated the "long-thin" market using older or less-efficient narrow-bodies. The entry of network carriers into this space with the A321XLR creates a direct, high-end competitor to the LCC model. Unlike the budget airlines, United and American can offer a full loyalty program, global lounge access, and seamless connections, potentially squeezing the market share of low-cost international operators.
Thirdly, the maintenance and supply chain implications are significant. Transitioning a fleet to include a new type of narrow-body for long-haul operations requires retraining pilots, adjusting maintenance schedules, and reconfiguring gate operations. As carriers like American and United scale their XLR fleets, we will likely see a period of operational adjustment as the industry adapts to the unique maintenance requirements of these extended-range jets.
Future Outlook: Sustainability and Scale
Looking ahead, the success of the A321XLR strategy will hinge on three factors: sustained premium pricing power, the reliability of new-generation engine technology, and the ability of airlines to manage complex, point-to-point flight schedules.
The industry is moving toward a future where "long-haul" no longer automatically implies a "wide-body" experience. For the consumer, this may result in more non-stop options to diverse destinations, though perhaps with a more condensed cabin environment. For the airlines, it represents the most significant shift in network strategy since the deregulation era. By betting on the flexibility of the A321XLR, United and American are attempting to insulate themselves against the unpredictability of modern global travel while simultaneously optimizing for the high-margin travelers who remain the backbone of the legacy airline business model.
In conclusion, the strategic pivot toward narrow-body transatlantic expansion is a clear indicator that the industry is moving toward a more agile, demand-responsive future. While the reliance on premium demand introduces a specific set of risks, the potential for enhanced profitability and network efficiency makes this one of the most critical developments in modern aviation finance and operations. As the ST200 continues to track the sector’s performance, the ability of these carriers to successfully integrate these aircraft will likely be a primary driver of shareholder value in the coming fiscal years. The transatlantic market is no longer just about volume; it is about precision, and the A321XLR is the precision tool chosen to define the next chapter of international flight.

 Anjar Salim
 Chandra Hamzah
 Tatiana Tantri Indah Sari
 Budi Mulyono
 Lukman Taruna Persada Ramadan