Gabriela Annisa
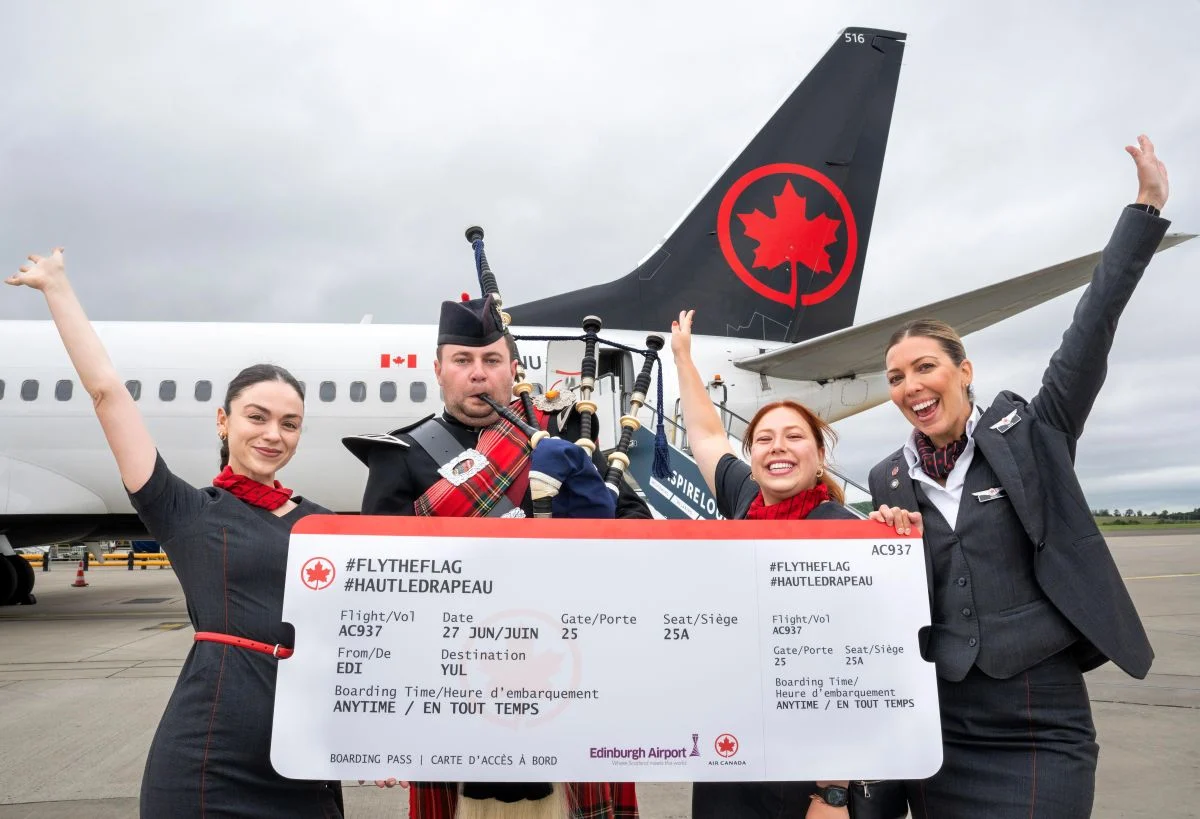
The leadership transition at Air Canada, marked by the stewardship of incoming executive leadership under Michael Rousseau and the broader management team, arrives at a critical juncture for the North American flag carrier. Simultaneously, the global aviation market is recalibrating as the "Big Three" Chinese carriers—Air China, China Southern, and China Eastern—grapple with a volatile second-quarter financial performance that underscores the complexities of a post-pandemic recovery. These two narratives, while geographically distinct, highlight the divergent pressures of labor costs, geopolitical headwinds, and shifting consumer demand patterns that define the current era of commercial aviation.
Air Canada: Navigating the Post-Pandemic Horizon
Air Canada has long positioned itself as a premier global network carrier, leveraging its geographic advantage to facilitate trans-Atlantic and trans-Pacific traffic. However, the current landscape is fraught with operational challenges that test the resiliency of the airline’s business model. Following the retirement of long-time stalwarts and the evolution of the carrier’s executive suite, the focus has shifted toward fleet modernization, labor relations, and the optimization of the international network.
The airline’s recent strategy centers on the integration of more fuel-efficient widebody aircraft, specifically the Airbus A321XLR and the continued expansion of its Boeing 787 Dreamliner fleet. These assets are vital for maintaining margins in an environment where fuel prices remain unpredictable and the demand for premium travel—business and "premium leisure"—has become the primary driver of profitability.
However, the "Anko" inheritance—a reference to the strategic foundation laid by outgoing leadership—is not without its burdens. Air Canada faces a competitive domestic market, with low-cost carriers continuing to chip away at market share. Furthermore, the carrier has been engaged in high-stakes negotiations with its pilot unions, a situation that reflects a broader industry trend where labor groups are seeking significant wage increases to compensate for inflation and the increased operational intensity of the post-COVID period.
The Chinese Aviation Sector: A Second-Quarter Reality Check
While North American carriers have largely enjoyed a sustained rebound in passenger yields, the situation for China’s Big Three—Air China, China Southern, and China Eastern—has proven more complex. The second quarter of the current fiscal year saw these carriers struggling to maintain profitability despite a resumption of international flight capacity.
Several structural factors explain this divergence. First, the recovery of international business travel to and from China has been slower than anticipated. While domestic travel within China has reached or exceeded 2019 levels, the lucrative international routes—historically the backbone of the Big Three’s profitability—have been hampered by visa processing delays, geopolitical tensions, and a tepid global economic recovery.
Second, the supply-demand imbalance has been exacerbated by the aggressive reactivation of widebody aircraft. As these carriers flooded the market with capacity in hopes of capturing pent-up demand, yields began to soften. The result was a classic "yield dilution" scenario, where increased supply outpaced the growth in high-yield passenger bookings, leading to compressed margins that disappointed investors.
Chronology of Recovery: A Comparative Analysis
To understand the current state of these aviation giants, one must look at the timeline of their respective recovery phases:
- Q1 2022: Global aviation begins to emerge from the Omicron variant wave. Air Canada focuses on capacity restoration, while Chinese carriers remain constrained by the "Zero-COVID" policy.
- Q4 2022: China announces the end of its restrictive health policies. The industry prepares for a massive, albeit disorganized, surge in travel.
- Q2 2023: North American carriers report record-breaking revenue as premium cabin demand peaks. Chinese carriers begin the slow process of re-staffing and re-certifying long-haul crews.
- Q2 2024: Air Canada continues its pivot toward a more agile, high-margin model. Simultaneously, the Big Three Chinese carriers face a "capacity trap," where the cost of operating global networks significantly outweighs the current yield environment.
Supporting Data and Market Performance
The Skift Travel 200 (ST200) index provides a comprehensive view of how these dynamics impact shareholder value. The index, which tracks nearly 200 travel companies globally, reveals a stark performance gap between carriers that have successfully leveraged premium demand and those still wrestling with domestic capacity saturation.
As of mid-2024, the airline sector has seen a bifurcation in stock performance. Carriers that successfully managed the balance between operational expenditure (OPEX) and capacity growth have seen a steady climb in equity value. Conversely, those weighed down by high debt loads—a common vestige of the pandemic era—have struggled to break out of stagnant trading ranges. For the Chinese Big Three, the challenge is not debt-servicing in the traditional sense, as they are largely state-backed, but rather the operational efficiency required to justify their massive scale.
Official Perspectives and Industry Implications
Industry analysts observe that the issues facing these carriers are symptomatic of a "new normal" in aviation. According to recent briefings from international aviation bodies, the industry is entering a phase where the "low-hanging fruit" of post-pandemic recovery has been harvested. What remains is a structural battle for efficiency.
"The carriers that will win in the next five years are those that can effectively segment their revenue streams," notes an aviation consultant familiar with the ST200 methodology. "Air Canada’s move toward a more diversified premium offering is a blueprint for network carriers globally. For the Chinese carriers, the path forward involves a delicate balance of state mandate for connectivity and the harsh realities of commercial viability."
Official responses from the involved parties have remained cautious. Air Canada has emphasized its commitment to long-term fleet flexibility, while the Chinese carriers have largely pivoted their messaging toward "high-quality development," a state-aligned focus on improving operational safety and service standards rather than pure volume growth.
Broader Impact and Global Aviation Trends
The implications of these developments extend beyond individual balance sheets. The aviation industry is currently navigating a period of capital-intensive transition. As airlines phase out older, less efficient aircraft, the demand for new production slots from Boeing and Airbus has created a supply-chain bottleneck. This, in turn, has limited the ability of airlines to expand capacity, effectively keeping ticket prices high for the consumer.
For Air Canada, the immediate task is maintaining labor peace while navigating the transition to a younger, more efficient fleet. For the Chinese Big Three, the imperative is to adapt their vast networks to a world where the speed of recovery in international trade and tourism has not matched the speed at which their domestic capacity was restored.
Ultimately, both narratives point to the same conclusion: the era of "growth at any cost" is over. The current environment rewards discipline, strategic differentiation, and the ability to pivot in the face of shifting macroeconomic winds. As the second half of the year progresses, investors and passengers alike will be watching closely to see if Air Canada can leverage its structural advantages and if the Chinese aviation giants can find the equilibrium necessary to return to sustainable profitability.
The convergence of these events serves as a reminder that the global airline industry is a singular, interconnected ecosystem. Whether it is a flag carrier in North America or a state-owned giant in Asia, the pressures of labor, fuel, and global demand are universal. The winners of this cycle will not be those with the largest fleets, but those with the most resilient operational foundations.

 Anjar Salim
 Chandra Hamzah
 Tatiana Tantri Indah Sari
 Budi Mulyono
 Lukman Taruna Persada Ramadan