
 Gabriela Annisa
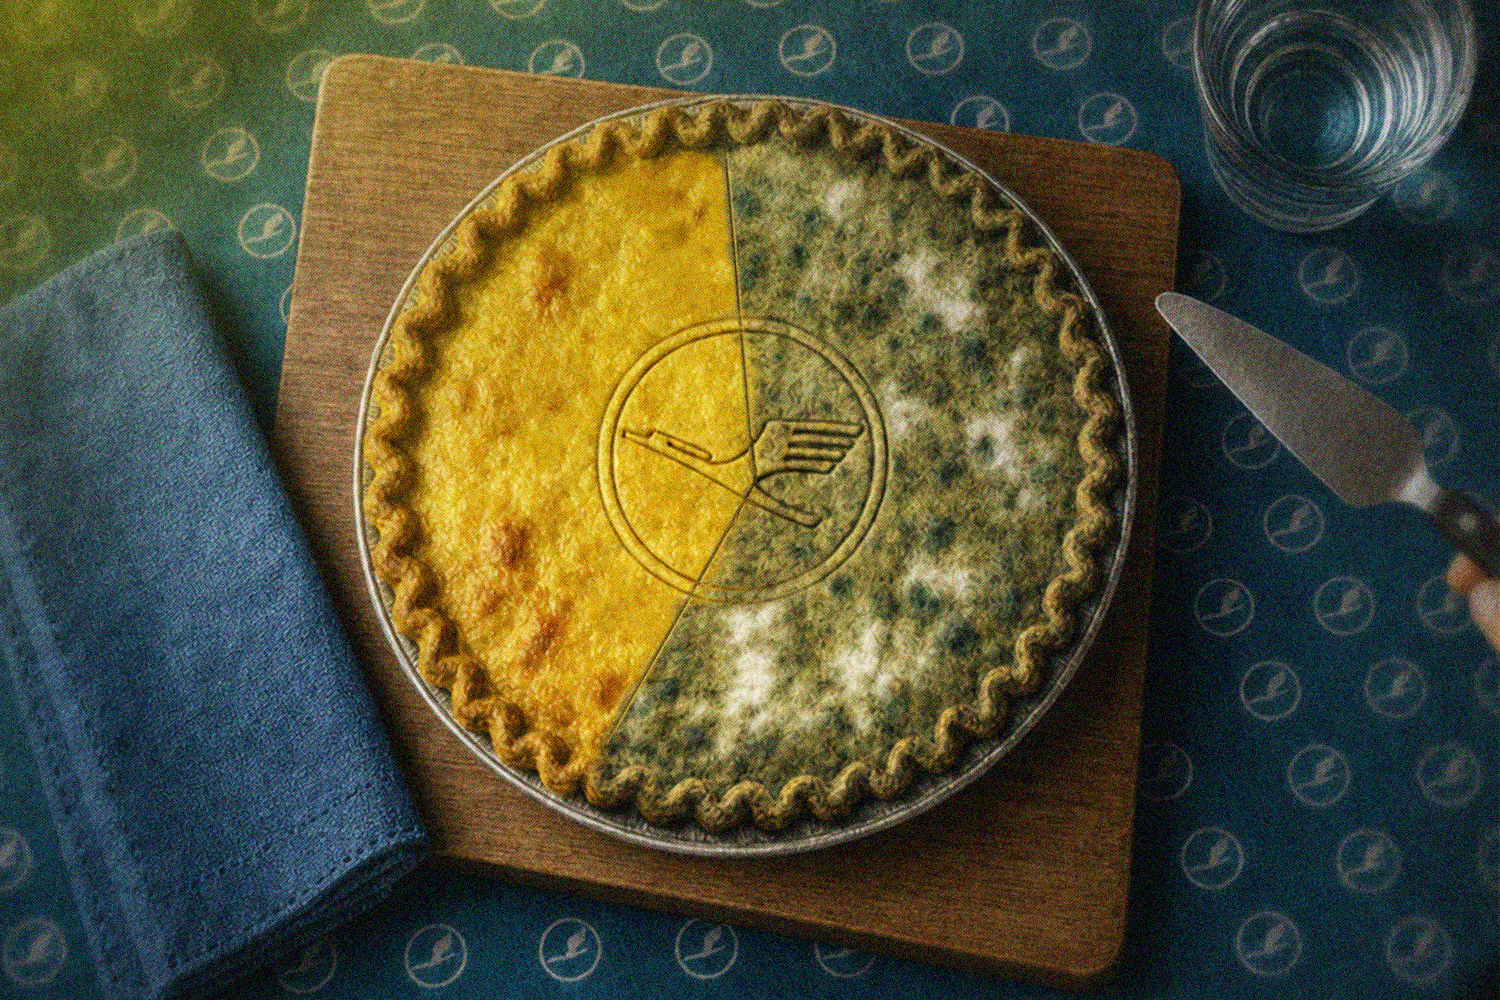
The Lufthansa Group currently finds itself at a critical strategic crossroads, defined by a stark bifurcation in performance that threatens to undermine its position as a global aviation powerhouse. While specific subsidiaries are delivering robust financial results, a significant majority of the group’s operations are currently struggling to navigate a complex landscape of labor disputes, systemic operational inefficiencies, and persistent supply chain bottlenecks. The fundamental challenge, often described by industry analysts as the 60-40 dilemma, reveals that approximately 40% of the group’s revenue streams—primarily anchored by Swiss International Air Lines, Lufthansa Cargo, and the maintenance giant Lufthansa Technik—are operating with high efficiency and profitability. Conversely, the remaining 60% of the business, most notably the flagship Lufthansa mainline brand, is facing structural headwinds that have forced the executive board to re-evaluate their long-term recovery strategies.
A Tale of Two Companies
The dichotomy within the Lufthansa Group is not merely a matter of regional performance but a reflection of disparate business models and operational maturity. Swiss International Air Lines has consistently acted as the group’s premium engine, benefiting from a high-yield market and a lean, disciplined operating structure. Simultaneously, Lufthansa Technik has leveraged the post-pandemic surge in aviation demand to dominate the global MRO (Maintenance, Repair, and Overhaul) market, providing a stable, high-margin revenue stream that serves as a hedge against the cyclical volatility of passenger air travel.
However, the "Lufthansa Classic" brand—the group’s primary passenger carrier—is grappling with the legacy of a rigid cost structure and a fleet modernization program that has been severely hampered by external supply chain failures. The inability to integrate new aircraft on schedule has forced the airline to rely on older, less fuel-efficient, and more maintenance-heavy aircraft, further inflating operational costs at a time when competitive pressures from low-cost carriers and Gulf-based airlines are intensifying.
Chronology of the Operational Crisis
The current malaise facing the Lufthansa Group did not emerge overnight; it is the culmination of years of pandemic-era restructuring, followed by an aggressive but perhaps overly optimistic post-COVID recovery phase.
- 2020-2021: The Stabilization Phase: Lufthansa Group received a €9 billion state-backed stabilization package from the German Economic Stabilization Fund (WSF). The focus was on survival, debt reduction, and workforce consolidation.
- 2022: The Rebound and Friction: As global travel demand surged, Lufthansa struggled to ramp up operations. Widespread labor shortages at German airports led to a chaotic summer, resulting in mass cancellations and the first signs of long-term reputational damage.
- 2023: The Cost-Push Reality: Inflationary pressures and escalating energy prices began to bite. Collective bargaining agreements became increasingly contentious, with major unions—including the pilots’ union Vereinigung Cockpit and the ground staff union Verdi—initiating a series of strikes that crippled network reliability.
- 2024: The Strategic Pivot: Facing mounting pressure from shareholders, the board signaled a shift toward "Turnaround 2024," a program aimed at decoupling the flagship airline’s performance from the rest of the group.
- 2025-2026: The Current Reality: Persistent delays in Boeing and Airbus delivery schedules have forced the airline to extend the service life of aging, fuel-inefficient aircraft, creating a drag on the bottom line that has persisted through the current fiscal year.
Supporting Data and Financial Context
To understand the gravity of the situation, one must examine the revenue distribution and the margin disparity across the group. In the most recent fiscal filings, Lufthansa Technik reported operating margins in the double digits, reflecting a sector-wide trend of high demand for technical services as airlines worldwide scramble to keep older aircraft flying longer.
In contrast, the Lufthansa mainline airline has reported operating margins that frequently dip into the low single digits. The cost of labor has become the most significant variable. According to industry reports, Lufthansa’s labor cost per available seat kilometer (CASK) remains among the highest in Europe. When combined with the high operational costs associated with maintaining a diverse, aging fleet, the flagship brand is left with little room for maneuver.
The fleet issue is particularly acute. Lufthansa currently operates a complex mix of aircraft, necessitating higher expenditures on spare parts and specialized pilot training. The group had anticipated that the introduction of the Boeing 777X and newer Airbus A350 variants would streamline operations and reduce fuel consumption by up to 20%. With the delivery of these aircraft delayed by years due to manufacturing issues at the OEMs, Lufthansa is essentially paying for the inefficiency of its current fleet twice: once in fuel costs and again in maintenance outlays.
Official Responses and Internal Perspectives
The Lufthansa Group’s executive board has acknowledged the necessity of a "comprehensive transformation" for the core brand. In recent investor briefings, leadership has emphasized that the group is no longer a monolith. The strategy moving forward involves granting more autonomy to individual units, allowing them to optimize their cost structures without being tethered to the legacy constraints of the Frankfurt-based mainline carrier.
"Our goal is to ensure that every part of the group contributes to our profitability targets," a company spokesperson recently noted. "While we are proud of the performance of our subsidiaries, we recognize that the mainline operation requires a fundamental change in how we manage labor, fleet, and ground operations."
Analysts from major investment banks have largely supported this shift in rhetoric, noting that the group is effectively moving toward a holding company structure where the "Lufthansa" brand is merely one of several competitors in a portfolio. However, labor representatives remain skeptical. Unions have argued that the pressure to improve margins is being disproportionately applied to the workforce, warning that any further attempts to reduce costs through structural changes will be met with industrial action.
Broader Implications for the European Aviation Sector
The situation at Lufthansa serves as a bellwether for the European aviation industry at large. The "legacy carrier" model is under existential pressure. Airlines that cannot achieve the agility of low-cost carriers while maintaining the premium service levels of network carriers are finding themselves trapped in the middle.
Lufthansa’s dilemma also highlights the fragility of the global supply chain. When an airline group as large as Lufthansa is held hostage by the delivery timelines of major aircraft manufacturers, it underscores the systemic risks inherent in the industry’s reliance on a duopolistic supply market. The downstream effect of these delays is felt not just in the balance sheet, but in the customer experience, as flight cancellations and schedule changes become more frequent.
Furthermore, the tension between the high-performing 40% and the struggling 60% poses a question of corporate identity. If the group successfully fixes its mainline brand, it will likely look very different than it does today—potentially with a smaller footprint, more automated processes, and a more modular workforce. If it fails, the risk of a permanent decline in the airline’s competitiveness becomes a reality, potentially leading to further consolidation or a fundamental restructuring of the group’s ownership model.
Looking Ahead
The path to recovery for the Lufthansa Group is narrow and fraught with external variables. While the management has set clear KPIs for the upcoming fiscal quarters, the ultimate success of the turnaround will depend on three factors: the stabilization of labor relations, the resolution of fleet delivery bottlenecks, and the successful execution of the new, decentralized management structure.
Investors remain cautious. The market is waiting for tangible evidence that the cost-cutting measures are not just temporary fixes, but are driving long-term structural improvement. For the passengers, the hope is that the current operational volatility will eventually yield to a more reliable, albeit potentially more expensive, flying experience.
As the industry watches, the Lufthansa Group stands as a study in the challenges of managing scale in a post-pandemic world. Whether the company can effectively rebalance its 60-40 split will likely determine its standing in the global aviation hierarchy for the next decade. The "Lufthansa Classic" brand, long the symbol of German industrial precision and service, must now prove it can adapt to a leaner, faster, and more volatile global landscape, or risk becoming an obsolete relic of a bygone era of aviation.

 Susilo Edi Turonggo
 Tatiana Tantri Indah Sari
 Walid Sujud Trenggono
 Cholid Fahmi Thalib
 Budi Mulyono
