Budi Mulyono
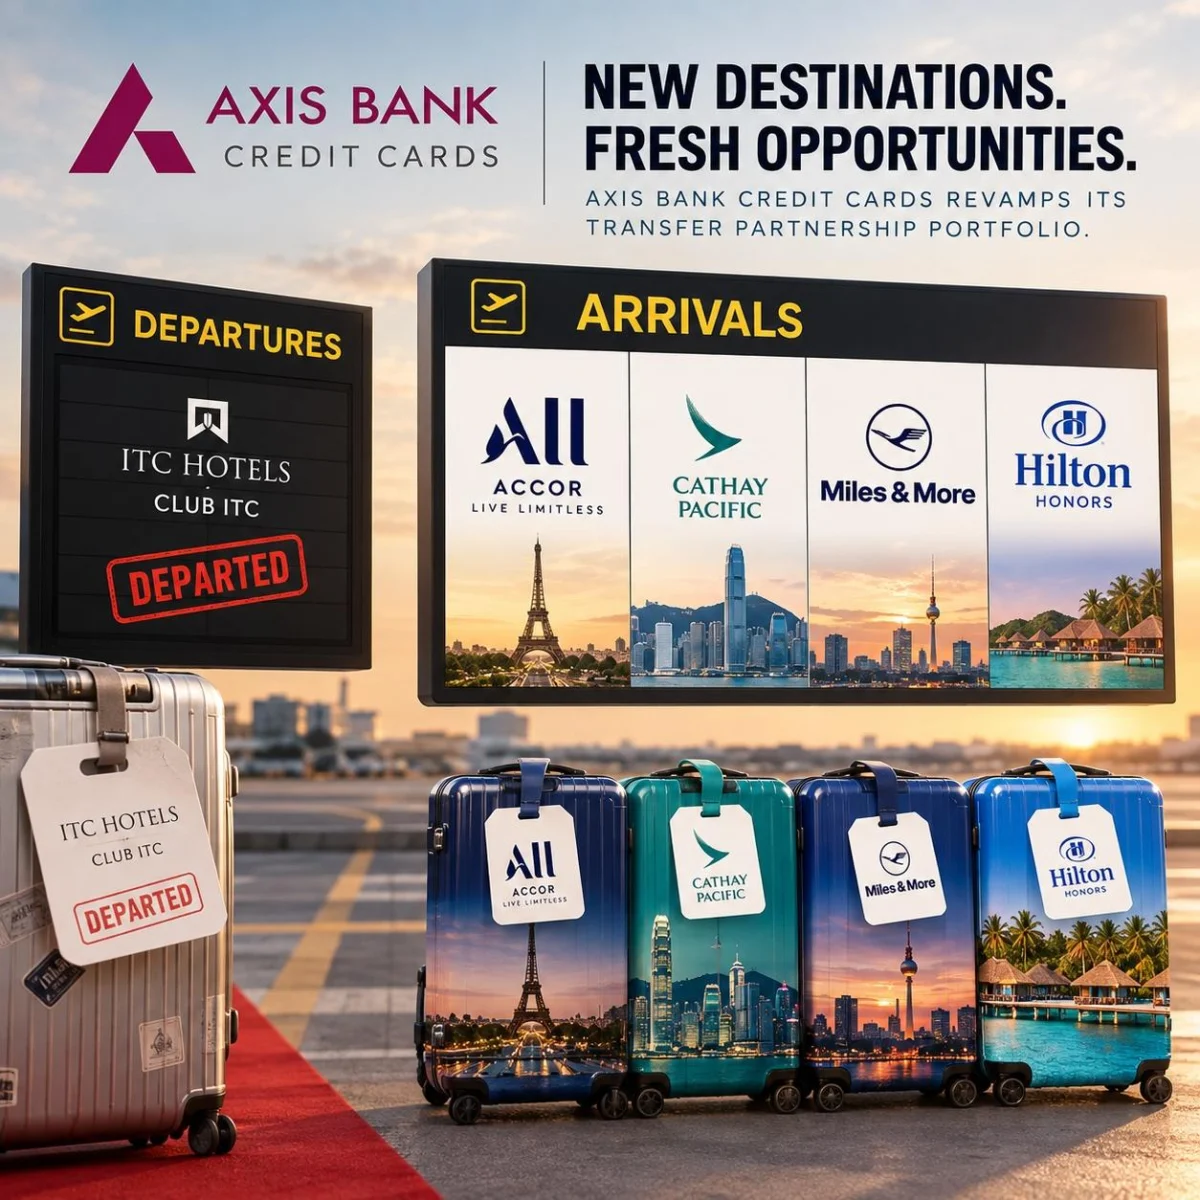
Axis Bank has implemented a sweeping and unexpected restructuring of its credit card transfer partner ecosystem, introducing significant updates that reshape the rewards landscape for cardholders across India. Effective September 23, 2026, the sweeping changes arrive just months after an earlier round of controversial devaluations and removals in April 2026. While the overnight update brings back several highly coveted programs—most notably Accor Live Limitless (ALL) and Qatar Airways—it also imposes strict annual quotas, alters transfer ratios, removes ITC Hotels, and shifts key airline and hotel partners into restrictive categories that dilute the long-term value proposition for high-tier cardholders.
The latest policy revision highlights the ongoing balancing act that financial institutions face as they attempt to curb the massive liabilities associated with high-volume reward redemptions. For years, Axis Bank established itself as an industry leader in travel rewards, attracting a massive customer base during the peak of the Magnus credit card era. However, shifting macroeconomic conditions, currency fluctuations, and soaring redemption volumes have forced a systematic tightening of its rewards framework.
Chronology of the Overhaul: From the Magnus Era to the 2026 Reshuffle
The evolution of Axis Bank’s reward structure tells a story of exponential growth followed by aggressive risk mitigation. During the height of the Axis Bank Magnus Credit Card popularity, the direct currency value assigned to Accor points—hovering at approximately INR 2 per point—made the program an unmatched favorite among Indian travelers. Axis Bank quickly emerged as one of the largest corporate buyers of ALL points globally.
However, as the Indian Rupee depreciated and the sheer volume of points transferred threatened profitability, the bank began trimming its offerings. Earlier in 2026, Axis Bank abruptly severed ties with Accor ALL and Marriott Bonvoy, while simultaneously devaluing conversion rates for partners such as Vietnam Airlines, British Airways, and Finnair.

The September 23, 2026 update represents the second major chapter in this year’s rewards restructuring. Rather than maintaining a static policy, the bank has reintroduced sidelined programs under a completely revised architecture characterized by tiered restrictions, diminished conversion ratios, and tighter annual caps.
Restructuring Partner Tiers: The Group A and Group B Divide
At the core of Axis Bank’s reward mechanics is a classification system that sorts transfer partners into distinct groups. Under this system, cost-effective or preferred partners occupy Group B, while more expensive or heavily utilized partners are assigned to Group A.
In the latest update, three major partners have been moved from Group B to Group A. This reclassification carries substantial implications for cardholders, as Group A partners are subject to much more restrictive annual quotas. For example, cardholders utilizing the Axis Atlas credit card now face a stringent annual transfer limit capped at just 30,000 points for partners categorized under Group A. This effectively forces users into difficult compromises, compelling them to choose between domestic and international redemptions within a tightly rationed pool.
Furthermore, popular programs such as Air India (Maharaja Club), Qantas, and Flying Blue have been shifted into Group A. For premium cardholders—particularly those holding the Magnus for Burgundy variant—the cumulative transfer limit for these restricted partners has been capped at an aggregate of 200,000 points per annum. Industry analysts note that these severe limitations effectively neutralize the card’s utility for luxury travelers aiming for extended multi-week stays at high-end properties like Raffles or long-haul business class itineraries.
Return of Key Partners and Altered Conversion Ratios
The September 2026 update is not entirely defined by restrictions; it also marks the reinstatement of several major loyalty programs alongside the introduction of new options.

The most anticipated return is Accor ALL, which rejoins the Axis Travel Edge rewards catalog alongside Qatar Airways. Additionally, the bank has expanded its network by onboarding new partners, including Lufthansa’s Miles & More, Cathay Pacific, and Hilton Honors. Conversely, ITC Hotels has been entirely removed from the transfer partner roster.
Despite the welcome return of Accor ALL, the underlying economics of the transfer have changed drastically. The new transfer ratio for Magnus for Burgundy cardholders has been set at 5:2—precisely half of the historical conversion rate. Financial experts point out that this steep reduction severely compromises the value proposition of the points, transforming what was once a lucrative transfer channel into an inefficient mechanism for booking luxury hospitality.
Similar ratio adjustments have been applied across other newly added and reinstated partners, including Cathay Pacific, ensuring that the cost of acquiring miles and points remains firmly under the bank’s control.
Legal Grounding and Terms & Conditions
The sudden nature of the modifications has sparked widespread discussion across financial forums and consumer circles. However, credit card issuers retain the unilateral right to alter reward program structures, as loyalty benefits are categorized as non-core product features rather than legally binding contractual obligations.
Under the terms and conditions outlined in the Axis Bank Travel Edge rewards portal, the issuer reserves the absolute discretion to modify, suspend, or terminate transfer partnerships, ratios, and caps at any time without prior individual consent. The complete and updated terms remain accessible via the official Axis Bank Travel Edge portal, outlining the precise legal boundaries governing the cardholder agreement.

Broader Market Implications and Competitive Landscape
The tightening of Axis Bank’s reward metrics has created a vacuum in the Indian credit card market, immediately benefiting competing financial products. Observers note that cards such as the HSBC Travel One credit card are well-positioned to capture market share from disillusioned Axis Bank loyalists who are reevaluating their wallet composition.
As credit card issuers globally grapple with the financial sustainability of aggressive reward programs, the Axis Bank overhaul signals a broader industry trend. The era of uninhibited, high-value point transfers appears to be giving way to a more conservative era defined by strict caps, dynamic pricing, and protective quotas.
For the everyday consumer, navigating these bi-annual adjustments requires a strategic reassessment of spending and redemption habits. Whether Axis Bank’s newly structured ecosystem will retain enough appeal to keep its premium customer base engaged remains to be seen as cardholders weigh the diminished conversion ratios against the convenience of a consolidated rewards platform.


 Tatiana Tantri Indah Sari

 Dwi Wanna
 Anjar Salim
 Lukman Taruna Persada Ramadan