Gabriela Annisa
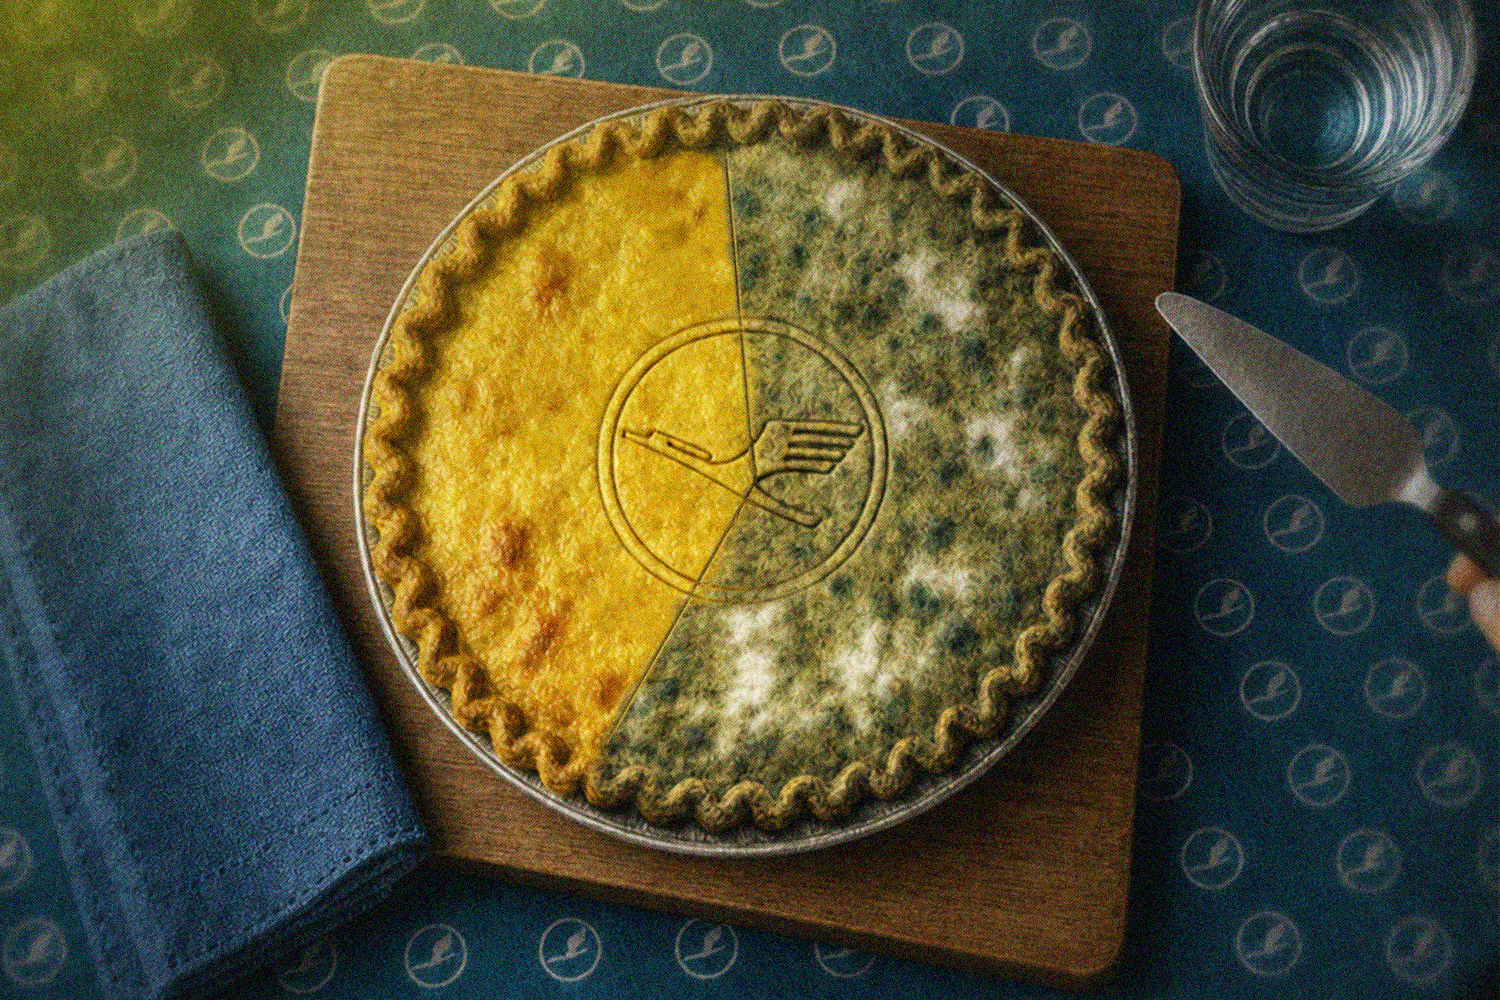
The Lufthansa Group, one of the world’s most storied aviation conglomerates, currently finds itself navigating a precarious structural bifurcation that threatens its long-term market dominance. While the group’s diversified portfolio includes high-performing segments that continue to exceed expectations, the core engine of the enterprise—the mainline Lufthansa brand—is mired in a cycle of operational inefficiency, labor unrest, and fiscal strain. This divide, which analysts have come to describe as the "60-40 dilemma," highlights a stark contrast between the high-margin, stable subsidiaries and the struggling legacy carrier that remains the face of the group.
The Anatomy of the 60-40 Split
At the heart of this internal tension is a breakdown of revenue generation that tells two very different stories. On one side of the ledger sit Swiss International Air Lines, Lufthansa Cargo, and Lufthansa Technik. These three entities have consistently demonstrated resilience, boasting robust profit margins and strong market positioning. Swiss continues to benefit from its premium brand image and high-yield traffic, while Lufthansa Technik remains the global leader in the maintenance, repair, and overhaul (MRO) sector, bolstered by a post-pandemic surge in aviation activity.
However, these crown jewels represent roughly 40% of the group’s total revenue. The remaining 60%—composed primarily of the mainline Lufthansa brand, along with other subsidiaries like Brussels Airlines, Austrian Airlines, and the newly integrated ITA Airways—is underperforming. The core "Lufthansa Classic" brand is currently grappling with a trifecta of systemic issues: spiraling labor costs, chronic delays in aircraft deliveries from original equipment manufacturers (OEMs), and an aging, inefficient cost structure that makes it difficult to compete with low-cost carriers (LCCs) on short-haul routes and aggressive global competitors on long-haul segments.
Chronology of the Operational Struggle
The current challenges did not emerge in a vacuum. The trajectory of the group’s struggles can be traced back to the onset of the global pandemic, which forced the airline to seek a state-backed bailout to survive the grounding of its fleet.
- 2020–2021: The Stabilization Phase: Lufthansa Group received a €9 billion government stabilization package. The focus during this period was purely on liquidity and survival.
- 2022: The Rebound and Bottlenecks: As travel demand surged, the airline struggled to restaff its operations. The resulting chaotic summer travel season led to widespread flight cancellations and significant reputational damage.
- 2023: The Inflationary Squeeze: Rising fuel prices and aggressive inflationary pressure on wages began to erode the margins of the mainline brand, even as the MRO and cargo divisions flourished.
- 2024–Present: The Integration and Restructuring Phase: The group moved forward with the acquisition of a stake in Italy’s ITA Airways, a strategic move aimed at capturing the lucrative southern European market. However, the integration process has highlighted the stark differences in operational efficiency between the group’s leanest subsidiaries and its most bloated legacy assets.
The Burden of the Mainline Brand
Lufthansa Classic is currently facing a "perfect storm." Labor relations have been particularly fraught, with the group navigating a series of strikes from both pilots’ unions and ground staff. These disputes have not only disrupted operations but have also resulted in significant wage increases, further inflating the cost base. Management has argued that these increases must be met with corresponding improvements in productivity, a stance that has been met with resistance from organized labor groups.
Furthermore, the brand is suffering from the global supply chain crisis. The airline has been forced to keep older, less fuel-efficient aircraft in service longer than anticipated because of delays in delivery schedules from both Boeing and Airbus. These aging aircraft are not only more expensive to maintain but also fail to provide the fuel economy required to maintain profitability in an era of high energy costs.
Analytical Perspective on Financial Implications
Financial analysts have noted that the divergence in performance creates a "valuation trap." If the group were valued solely on its high-performing assets—Technik and Swiss—it would be seen as a premier global aviation player. However, when those assets are weighed down by the heavy fixed costs and operational volatility of the legacy passenger airline, the overall stock performance reflects the uncertainty surrounding the turnaround effort.
Data from the group’s recent earnings reports suggest that while group-wide revenue is growing, the operating margins for the passenger airlines are significantly thinner than those of the MRO and cargo divisions. This disparity puts immense pressure on management to demonstrate a clear roadmap for the "turnaround" of the mainline brand. The success of this strategy is contingent upon fleet modernization and the successful digitalization of passenger services, both of which require significant capital expenditure at a time when cash flow is already under duress.
Official Responses and Strategic Pivot
In response to the growing criticism, Lufthansa Group leadership has emphasized a shift toward "Turnaround 2.0," a strategic plan designed to harmonize operational standards across the various airlines in the group. In a recent investor briefing, the executive board indicated that the group intends to centralize certain back-office functions to reduce duplication and overhead costs, which have historically been high due to the decentralized nature of the group’s airline holdings.
"Our goal is to ensure that every part of our group contributes to the bottom line with the same rigor that we see in our Technik and Cargo divisions," a spokesperson for the group stated. "We acknowledge the challenges within the mainline brand, and we are working toward a multi-year plan that addresses the structural inefficiencies while maintaining the high service standards our customers expect."
However, industry experts remain cautious. The complexity of integrating ITA Airways while simultaneously restructuring the legacy Lufthansa brand is a monumental task. The risk, according to some analysts, is that the group may be spreading its resources too thin, trying to fix its core operations while also navigating the complexities of an international merger.
The Path Forward: Implications for the Industry
The "60-40 dilemma" serves as a microcosm of the challenges facing legacy carriers globally. As the aviation industry pivots toward greater consolidation, the ability to manage diverse, multi-brand portfolios is becoming the primary differentiator between success and stagnation. For Lufthansa, the path to resolving this dilemma involves more than just cost-cutting; it requires a fundamental shift in how the airline manages its labor force, its fleet, and its digital infrastructure.
The implications for the broader European market are significant. If Lufthansa succeeds in streamlining its operations, it will solidify its position as the preeminent force in European aviation, capable of competing with the growing dominance of Middle Eastern carriers on long-haul routes and low-cost giants on short-haul routes. If it fails, the group may face further calls for divestment or a more radical restructuring that could see its fragmented subsidiaries broken off into independent entities.
Ultimately, the next eighteen months will be critical. The group must prove that the "60%" can be brought up to the standards of the "40%." For shareholders, employees, and passengers alike, the question is whether Lufthansa can modernize its legacy heart without losing the operational excellence that has kept it afloat during these turbulent years. The reliance on Technik and Swiss to carry the financial burden is not a sustainable long-term strategy; the mainline brand must once again become a driver of value, rather than a drain on it. The mold on the pie, to use the visual metaphor of the moment, must be scraped away, and the recipe for profitability updated for a new, more competitive era of global aviation.

 Anjar Salim
 Chandra Hamzah
 Tatiana Tantri Indah Sari
 Budi Mulyono
 Lukman Taruna Persada Ramadan