 Gabriela Annisa
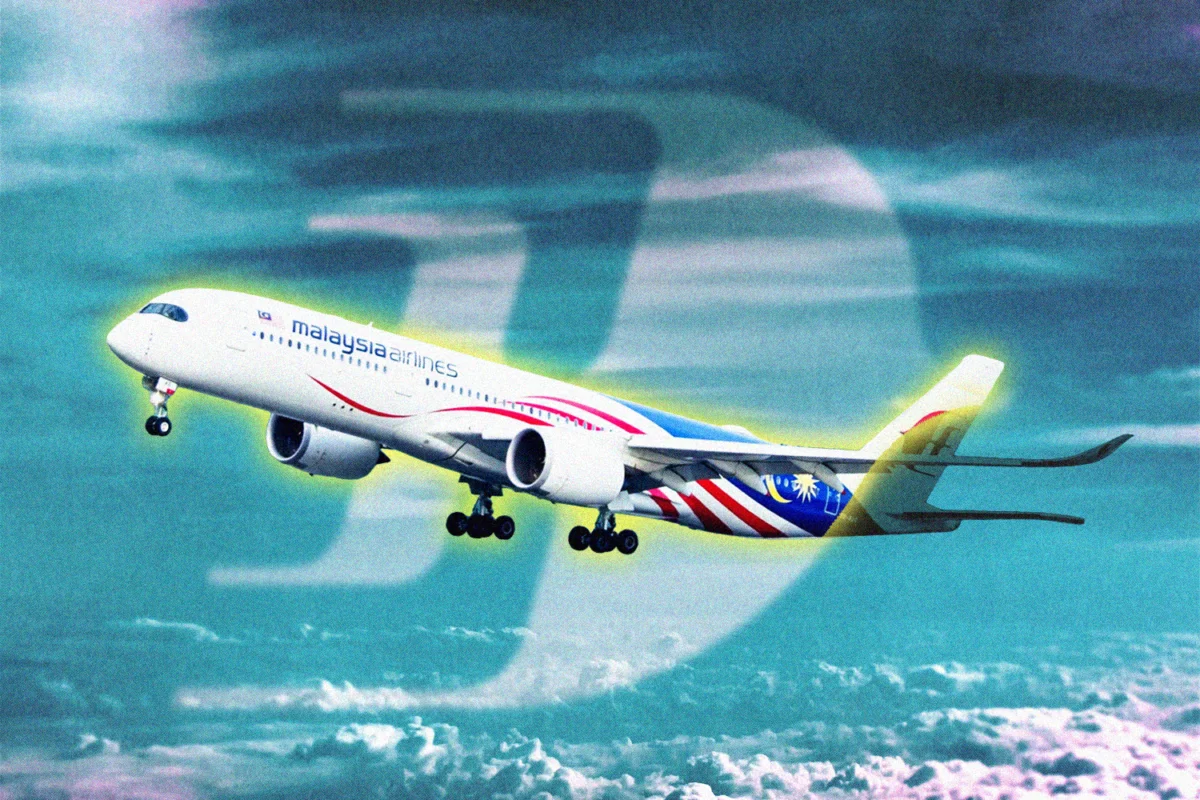
The post-pandemic recovery of Malaysia Airlines has been a narrative of resilience, defined by four consecutive years of profitability following a sweeping restructuring program necessitated by the global health crisis. However, as of September 2026, the national carrier finds itself at a precarious juncture. Despite the headline-grabbing streak of black ink, the airline’s net margin—hovering persistently below the 1% threshold—reveals a structural vulnerability. While the company has managed to stabilize its balance sheet, the underlying economics of its passenger operations remain fragile, leaving the carrier with virtually no financial cushion to absorb the dramatic 90% year-over-year surge in fuel costs.
The Mirage of Profitability: A Deep Dive into Financials
For stakeholders and industry observers, the Malaysia Airlines recovery story has been a complex one to interpret. On the surface, the return to profitability is a clear success for management, marking a turnaround from the deep losses incurred during the 2020–2021 period. Yet, a forensic analysis of these earnings suggests that the airline’s bottom line has been heavily subsidized by non-passenger segments.
Data indicates that the carrier’s MRO (Maintenance, Repair, and Overhaul) division and its cargo operations have been the primary drivers of recent financial stability. By leveraging these ancillary business units, Malaysia Airlines has offset the thinning yields of its passenger network. This reliance on non-passenger revenue streams highlights a broader industry trend where legacy carriers are increasingly diversifying to survive volatile fuel prices and fluctuating passenger demand. However, with fuel costs nearly doubling compared to the previous year, the margin for error has effectively evaporated. The airline is now forced to confront the reality that its core business—commercial aviation—must become significantly more efficient to remain viable in an increasingly competitive Asia-Pacific market.
A Chronology of Recovery and Rebirth
The current state of Malaysia Airlines is the result of a multi-year effort to modernize its fleet and operational structure. Following the onset of the pandemic, the airline initiated a comprehensive restructuring plan that focused on debt reduction and fleet optimization.
- 2021: The airline successfully negotiated with creditors to reduce its debt burden by billions of ringgit, effectively clearing the path for a leaner operation.
- 2022–2023: As global travel restrictions eased, Malaysia Airlines focused on rebuilding its network, prioritizing high-yield routes and establishing strategic partnerships to capture the rebound in international tourism.
- 2024: The airline achieved its third consecutive year of profitability, signaling that the restructuring efforts had yielded tangible operational improvements.
- 2025: The focus shifted toward long-term sustainability, with management emphasizing the need for fleet renewal and digitalization.
- 2026: The current year has been defined by extreme external shocks. The 90% fuel price hike has forced a re-evaluation of the carrier’s long-term network strategy and capital expenditure plans.
The Competitive Landscape: The AirAsia Factor
The challenges facing Malaysia Airlines are not merely internal or macroeconomic; they are also intensely competitive. The recent reorganization of AirAsia into a unified, consolidated entity has reshaped the regional landscape. AirAsia, long known for its aggressive pricing and operational efficiency, has emerged from the post-pandemic era with a simplified corporate structure that allows for faster decision-making and better economies of scale.
For Malaysia Airlines, this presents a "pincer movement" scenario. On one side, it faces the operational pressure of record-high fuel prices. On the other, it faces a formidable, reorganized low-cost rival that is better positioned to capture price-sensitive travelers. This competitive pressure limits the ability of Malaysia Airlines to pass on increased fuel costs to consumers through higher ticket prices, thereby squeezing margins even further. Analysts suggest that the carrier’s premium positioning is being tested as it attempts to balance the need for revenue growth with the necessity of maintaining market share against an emboldened low-cost sector.
Fleet Strategy and the Widebody Decision
At the heart of the airline’s future prospects lies a critical, yet-to-be-fully-realized, widebody order. The selection of its next-generation long-haul fleet will effectively define the airline’s network capabilities for the next decade. Choosing the right aircraft is a high-stakes gamble; the carrier must balance range, fuel efficiency, and passenger capacity.
Industry experts note that while the current fleet has served the airline well during its recovery phase, it is becoming increasingly mismatched with the demands of modern, fuel-efficient operations. A transition to newer, more efficient twin-engine widebodies is essential to lowering the unit cost of operation. However, the timing of such an order is fraught with difficulty. Financing new aircraft in a high-interest-rate environment, coupled with the immediate liquidity drain caused by soaring fuel expenses, makes the decision a tightrope walk for the board. The selection is expected to serve as a bellwether for the airline’s confidence in its long-term growth strategy.
Official Stance and Market Reaction
While formal statements from the airline’s leadership have remained cautiously optimistic, the underlying message is one of urgent adaptation. Management has signaled a move toward greater digital transformation and an intensification of its loyalty program to drive direct bookings—a move designed to reduce reliance on third-party distribution channels that command significant commissions.
Market analysts, however, remain divided. Some suggest that the airline’s current path is sustainable, provided that it continues to integrate its cargo and MRO divisions into the broader group strategy. Others argue that without a fundamental reduction in operational costs—particularly in labor and fuel hedging—the thin net margins will inevitably lead to future volatility. "The airline has successfully navigated the crisis, but it has yet to solve the problem of profitability in the passenger business," noted one aviation consultant based in Singapore. "The next twelve months will be the true test of whether the restructuring was a temporary fix or a permanent evolution."
Broader Implications for the Asia-Pacific Aviation Sector
The plight of Malaysia Airlines is reflective of a wider trend across the Asia-Pacific region. Carriers that were once "too big to fail" are now finding that state support is no longer a guaranteed safety net. The shift toward market-driven profitability requires airlines to move away from legacy operational models.
If Malaysia Airlines succeeds in balancing its books despite the current fuel crisis, it could serve as a blueprint for other national carriers struggling with the transition to a modern, high-efficiency environment. Conversely, if the airline continues to struggle with margins, it may face pressure to consider further consolidation or deeper strategic alliances with larger regional players.
Strategic Analysis: The Path Forward
To secure its future, Malaysia Airlines must prioritize three key areas:
- Aggressive Fuel Hedging and Efficiency: Beyond simple hedging, the airline must adopt AI-driven flight planning and weight-reduction strategies to mitigate the impact of the fuel crisis on its bottom line.
- Network Rationalization: The carrier needs to be ruthless in cutting underperforming routes. In an era of expensive fuel, the focus must shift from network breadth to network depth, ensuring that every seat flown is contributing to a positive margin.
- Enhancing Ancillary Revenue: While MRO and cargo have been pillars of the recovery, the airline must find ways to increase passenger-related ancillary revenue—such as premium seating upgrades and personalized travel services—to ensure that its core product is profitable.
The next year will be defined by how effectively Malaysia Airlines manages its cash flow while navigating the complexities of its fleet renewal. The airline is currently at a turning point; it has successfully survived the turbulence of the pandemic, but the horizon remains clouded by economic instability and fierce competition. Whether it can transform its modest recovery into long-term dominance will depend on its ability to turn its operational strengths into a consistent, sustainable profit engine. As the industry watches, the carrier’s upcoming decisions on its widebody fleet and its ability to defend its market share will be the final verdict on the success of its post-pandemic strategy.

 Tatiana Tantri Indah Sari
 Budi Mulyono
 Chandra Hamzah