 Budi Mulyono
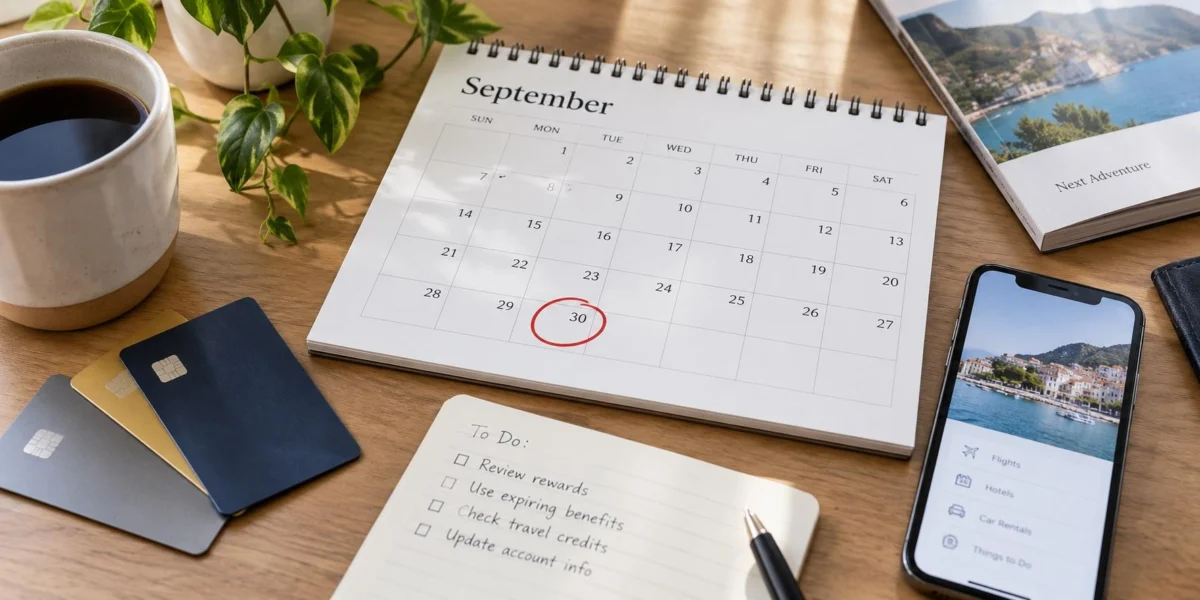
As the calendar turns toward the final hours of September, credit card holders across the United States face a quiet yet financially significant deadline. September 30 marks not only the end of the ninth month of the year but also the definitive close of the third quarter (Q3). For millions of consumers carrying premium rewards cards, travel cards, and cash-back products, this date triggers the expiration of lucrative monthly statement credits and the simultaneous reset of several valuable quarterly benefits. While financial institutions routinely structure these perks to encourage consistent card engagement, the failure to utilize them before the midnight deadline results in the permanent forfeiture of hundreds of dollars in potential savings.
Financial analysts emphasize that this period serves as a critical checkpoint for savvy consumers. Rewards ecosystems have evolved significantly over the past decade, shifting away from simple annual bonuses toward fragmented, recurring allotments of monthly and quarterly credits. Major issuers, including American Express and Chase, utilize these schedules to manage issuer liability while incentivizing cardholders to keep premium accounts active despite rising annual fees. However, the complexity of tracking dozens of disparate expiration dates often leads to unclaimed value. As the Q3 window closes, cardholders are urged to audit their active benefits portfolios to ensure that earned perks are not left on the table.
Chronology of the Q3 Reset and Deadlines
The mechanics of credit card billing cycles and benefit allotments operate on strict temporal boundaries. Understanding the timeline of these expirations helps contextualize why September 30 is such a pivotal date for rewards maximization:
- September 14: For cardholders of products like the Chase Freedom Flex, this date often serves as the final cutoff to activate quarterly bonus spending categories, a prerequisite for earning elevated rewards.
- September 30 (11:59 PM Local Time): The absolute deadline for utilizing Q3 quarterly statement credits across various premium cards, including specific airline, hotel, and lifestyle allocations. It is also the final day to accumulate 5X points on expiring Q3 rotating categories.
- October 1: The commencement of the fourth quarter (Q4). All quarterly counters reset to zero, unused Q3 credits vanish permanently, and new Q4 bonus categories and credit allotments take effect.
This rigid calendar leaves no grace period. Transactions must typically post to the account before the stroke of midnight on September 30 to qualify against the Q3 allocation, meaning pending charges that clear on October 1 will be applied to the new quarter’s limits.
Detailed Breakdown of Expiring Quarterly Credits
Several high-profile credit cards feature specific quarterly allotments that demand immediate attention from their holders. Among the most prominent are offerings from American Express and its co-branded hotel partners.
The American Express Platinum Card and The Business Platinum Card from American Express feature various structured statement credits that operate on quarterly or semi-annual intervals, requiring cardholders to carefully match their remaining Q3 allowances with upcoming purchases. Similarly, co-branded hotel products such as the Hilton Honors American Express Aspire Card include up to $50 in statement credits each quarter for eligible airfare purchases made directly with airlines, through AmexTravel.com, or via the Amex Travel App.
Concurrently, the Hilton Honors American Express Surpass Card provides up to $50 in statement credits each quarter for eligible transactions executed directly with properties within the Hilton portfolio. Because these benefits do not roll over into subsequent quarters, failing to complete an eligible hotel stay or airfare purchase by September 30 means forfeiting the $50 allotment entirely.
In addition to quarterly thresholds, the end of September wipes the slate clean for monthly recurring credits. Cardholders must evaluate whether they have maximized their current month’s allocations for dining, streaming services, wireless communications, and rideshare applications. Industry data indicates that millions of dollars in monthly credits go unclaimed simply because consumers lose track of overlapping expiration dates across multiple issuer portals.
The Shift in Chase Freedom Rotating Categories
Beyond statement credits, the conclusion of September marks a major transition for cash-back enthusiasts utilizing the Chase Freedom Flex and legacy Chase Freedom cards.
For the third quarter of the year, active cardholders have been earning an elevated 5X cash back on up to $1,500 in combined eligible purchases within specific categories, including gas stations, electric vehicle (EV) charging stations, public transit, select live entertainment, and United Way donations. September 30 is the final day to accumulate rewards under this specific multi-industry umbrella.
Looking ahead, the transition to Q4—spanning from October 1 through December 31—introduces an entirely new earning structure. Cardholders who activate the upcoming quarterly promotion will unlock 7X total points on eligible dining, alongside 5X points at grocery stores (excluding wholesale clubs and supercenters like Walmart and Target) and on eligible American Red Cross donations. The abrupt shift underscores the necessity of monitoring activation windows, as failure to enroll prior to deadlines can permanently invalidate retroactive earnings for the quarter.
Industry Perspective and Consumer Strategy
Financial consumer advocates and rewards experts consistently advise a measured approach to these impending deadlines. The golden rule of credit card optimization remains constant: use the credit, but do not chase the credit.
Market researchers note that credit card issuers design reward structures with behavioral economics in mind. The psychological aversion to losing a benefit—often framed as loss aversion—frequently compels consumers to make unnecessary purchases just to capture a $20 or $50 credit. From a purely financial standpoint, spending $50 on an item or service that holds no genuine utility solely to claim a matching statement credit results in zero net savings.
Conversely, when cardholders can organically align their pre-planned, necessary expenditures with active issuer credits or elevated bonus categories, the financial return can be substantial. For instance, booking a pre-scheduled flight through Amex Travel to trigger a Hilton Aspire credit, or timing a routine grocery run to coincide with a Q4 rewards category, maximizes the card’s value proposition without altering household budgets.
Broader Financial Implications and Future Outlook
The reliance on digital ecosystems, mobile applications, and online portals to track rewards has transformed how consumers interact with financial institutions. Issuers increasingly rely on proprietary apps to notify users of expiring benefits, yet the onus remains squarely on the cardholder to navigate complex terms and conditions.
As annual fees for premium travel and rewards cards continue to climb—frequently surpassing the $600 to $700 threshold—the financial burden of recouping these costs through statement credits has intensified. Industry observers suggest that failure to utilize quarterly and monthly credits effectively diminishes the net value of holding premium cards, potentially leading to increased card churn or cancellations as consumers reassess wallet composition.
Ultimately, the September 30 deadline serves as a micro-test of consumer financial hygiene. By conducting a swift audit of active wallets, verifying pending statement credits, and noting upcoming quarterly transitions, cardholders can ensure they capture the full value of their financial products before the window closes and the calendar turns to a new quarter.

 Chandra Hamzah
 Gabriela Annisa
 Susilo Edi Turonggo
