
 Budi Mulyono
The landscape of consumer finance and travel rewards has undergone a dramatic transformation over the past decade, shifting from simple cash-back incentives to complex ecosystems of high-fee, high-reward premium credit cards. Today, consumers evaluating their wallet contents face an increasingly diverse market segmented by price points: no-annual-fee cards designed for straightforward utility, mid-range cards commanding annual fees under $200, and a rapidly expanding tier of luxury premium cards charging $300 to upwards of $800 annually.
Historically dominated by general-purpose travel cards, the premium market now features an array of co-branded airline and hotel instruments targeting loyalists. As issuers continuously raise annual fees to offset mounting perk costs, financial analysts, frequent flyers, and travel industry observers are increasingly scrutinizing whether these luxury cards genuinely deliver value or if they have morphed into elaborate budgeting chores for consumers.
Understanding the Core Value Proposition
The foundational economic model of premium credit cards relies on a delicate balance between steep upfront costs and offsetting benefits. Issuers market these products with the premise that annual fees can be completely neutralized—and often surpassed—by combining statement credits, airport lounge access, elite status tiers, and accelerated reward point earnings.
From a structural standpoint, nearly every premium card relies heavily on statement credits for travel, dining, ride-sharing, and retail purchases. These credits often carry a combined retail face value that exceeds the card’s annual fee. However, this structure is intentionally designed around consumer habits and "breakage"—the financial industry term for unused or forgotten credits. Because many of these credits are distributed on monthly, quarterly, or semi-annual cycles rather than a single lump sum, cardholders must navigate a complex calendar of expiration dates to realize their full value.
From the issuing banks’ perspective, these perks rarely cost their full retail value. Merchant-funded partnerships allow platforms to subsidize statement credits in exchange for guaranteed consumer traffic, while proprietary travel booking portals generate lucrative commissions. Consequently, the true value calculation for any consumer requires subtracting only the credits they will realistically and organically use from the annual fee, followed by a subjective assessment of intangible perks like lounge access and automated elite tier statuses.
The Case for Premium Cards: Maximizing Strategic Value

Despite the cognitive load required to manage them, premium credit cards offer substantial financial upside for consumers who align their lifestyle and spending habits with the card’s specific architecture. Industry data indicates that frequent travelers can routinely capture thousands of dollars in annual value, provided they approach card management with strategic intent.
Maximizing Statement Credits Through Diligence
The primary gateway to breaking even on a luxury credit card is a disciplined approach to statement credits. Cardholders who organically utilize services such as pre-paid hotel portals, airport lounge networks, premium dining reservations, and specialized transit apps find that the annual fee effectively disappears. Successful cardholders typically maintain a digital calendar or tracking system to ensure monthly and quarterly disbursements are fully captured before expiration, transforming standard expenditures into discounted travel currency.
Unlocking Comprehensive Airport Lounge Access
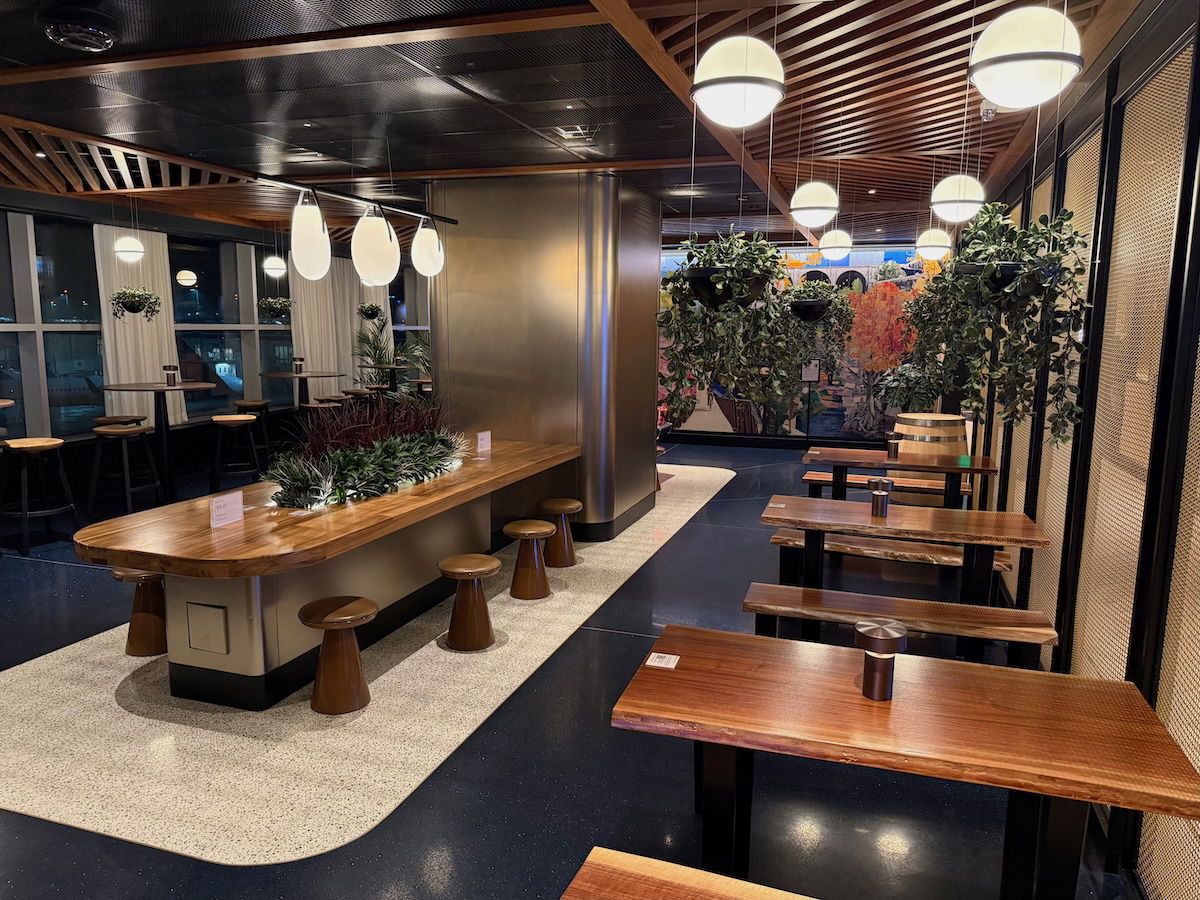
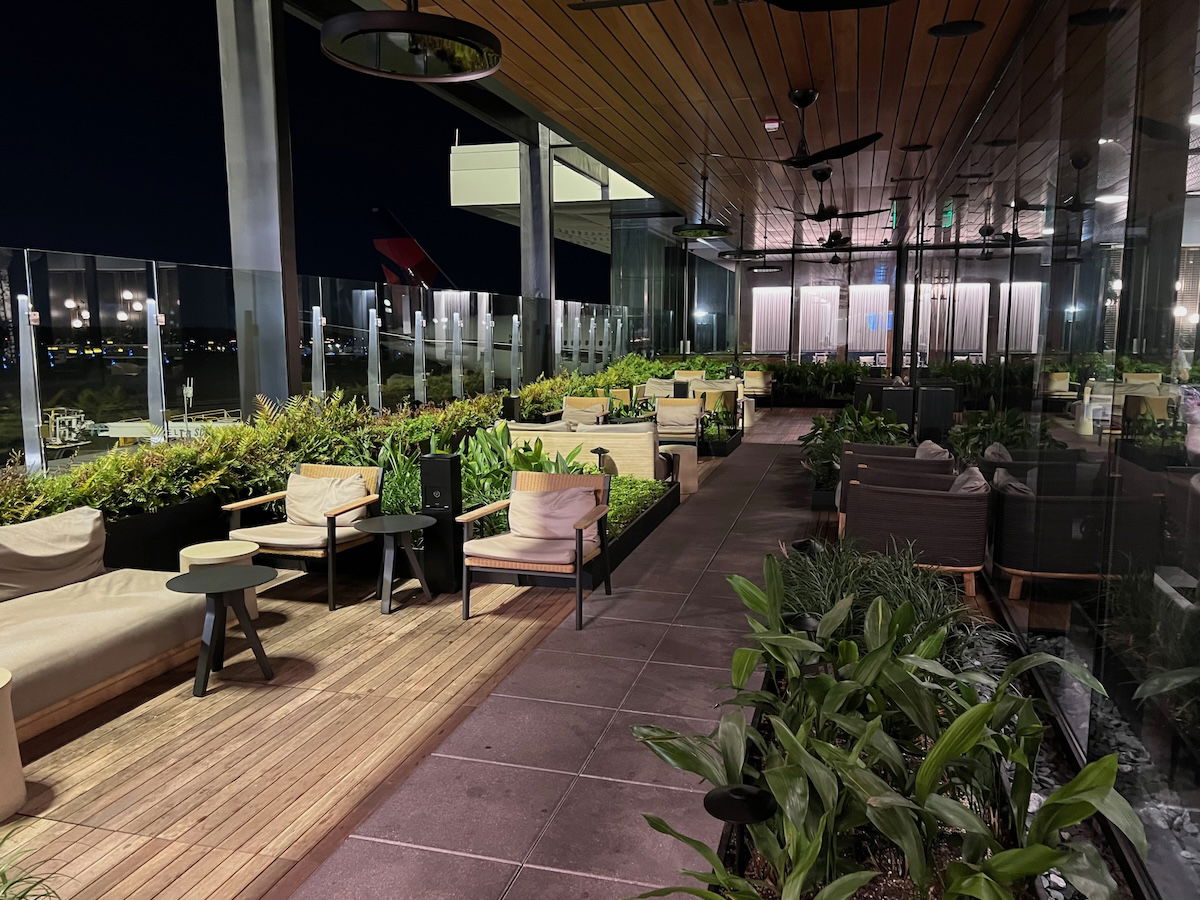
For frequent flyers navigating congested terminals, lounge access remains one of the most compelling reasons to maintain a premium card portfolio. Traditional airport waiting areas have become increasingly crowded and expensive, making network lounges a valuable oasis. Premium cards frequently grant access to expansive proprietary networks—such as American Express Centurion Lounges, Capital One Lounges, and Chase Sapphire Lounges—alongside traditional Priority Pass memberships. For frequent travelers who would otherwise purchase day passes or buy food and beverages in the terminal, the cumulative savings and comfort can easily validate the cost of card ownership.
Leveraging Travel Rewards and Elite Status
Another primary driver for premium card adoption is the accelerated accumulation of transferable points and immediate qualification for hotel or airline elite status. Unlike standard cash-back products, premium travel cards allow users to transfer accumulated points to a variety of airline and hotel partners, where strategic redemptions for business-class international flights or luxury hotel stays can yield values exceeding two to three cents per point. Furthermore, cards that bundle mid-to-high tier hotel elite status (such as automatic Gold or Diamond tiers) provide tangible perks like complimentary breakfast, room upgrades, and late checkout, which can offset an annual fee within a single weekend getaway.

The Counterargument: Credit Card Fatigue and Lounge Overcrowding
As the market for luxury financial products has matured, a growing segment of consumers and financial commentators have begun pushing back against the proliferation of high-fee cards. This skepticism is driven largely by two emerging phenomena: consumer exhaustion and the diminishing returns of overcrowded airport infrastructure.
The Rise of Credit Card Fatigue
The term "credit card fatigue" has entered the financial lexicon to describe the mental exhaustion consumers experience when attempting to track dozens of micro-credits, expiration dates, and category spending rules. When cardholders must split a single hotel bill across three different credit cards to maximize quarterly credits, the experience shifts from an exclusive luxury perk to a burdensome administrative task. Industry experts note that what began as a rewarding hobby for travel enthusiasts has increasingly begun to resemble coupon-clipping, leading a notable percentage of consumers to downgrade their wallets in favor of simpler, flat-rate financial products.
The Paradox of Lounge Overcrowding
Perhaps the most significant structural challenge facing premium travel cards is the severe overcrowding of airport lounges. Originally designed as exclusive sanctuaries for elite business travelers, lounges have seen a massive surge in foot traffic driven directly by the millions of consumers holding premium credit cards.
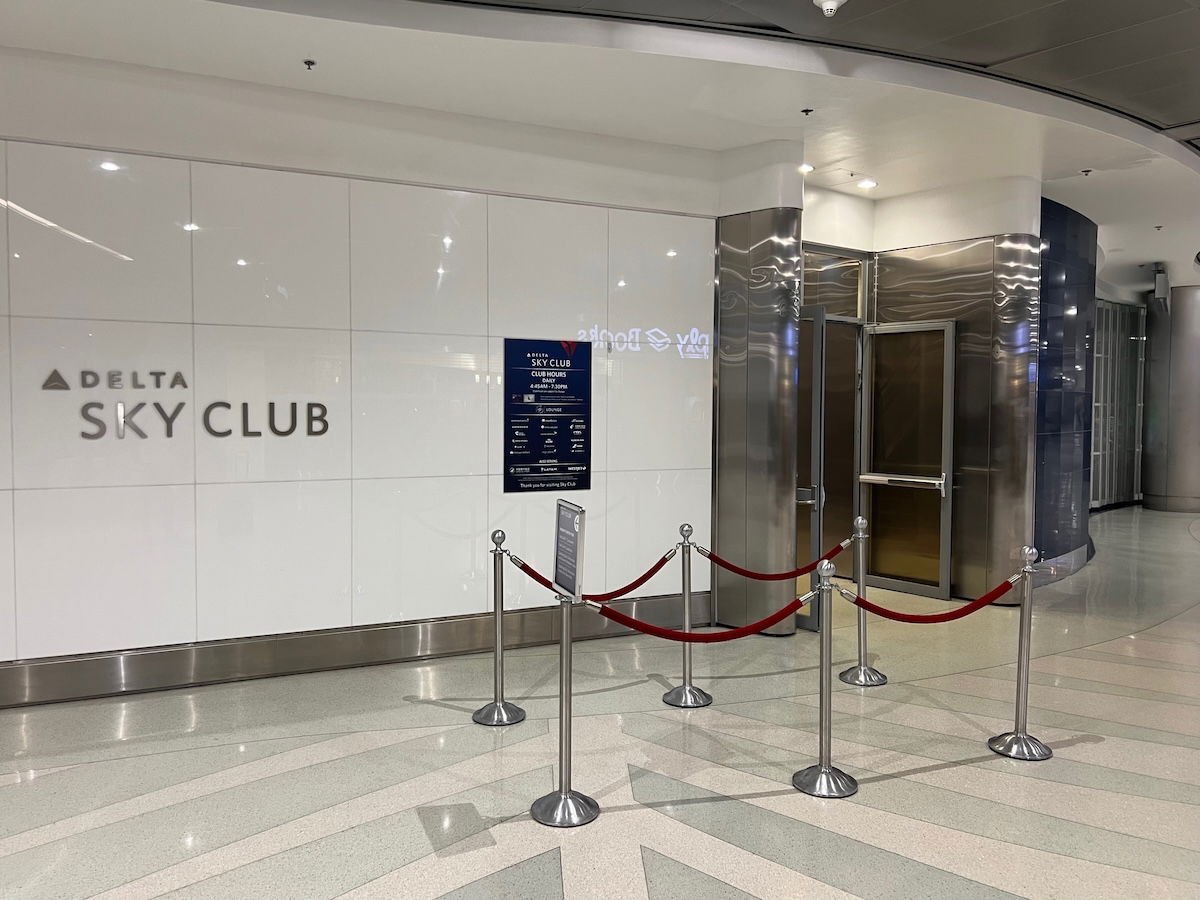
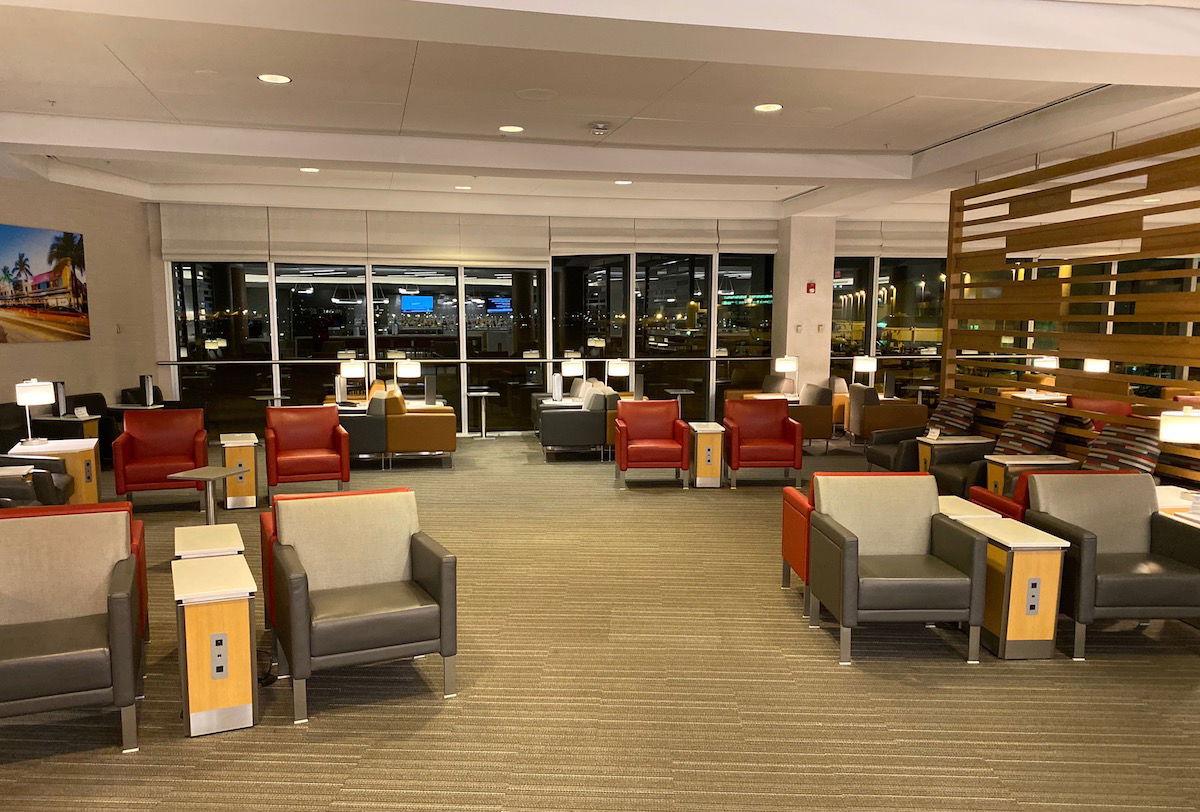
This dynamic has created a distinct irony: terminals that once offered a quiet respite from crowded gates are now frequently subject to long entry queues and packed seating areas, as travelers attempt to maximize their annual fees by consuming complimentary food and beverages. For many seasoned travelers, the true luxury has inverted—shifting away from crowded lounge buffets toward quiet, uncrowded gate areas paired with a simple terminal sandwich.
Comparative Financial Analysis of Market-Leading Premium Cards
To understand how these principles apply in practice, examining the fee structures and primary value drivers of the industry’s most popular offerings provides clear context.
Capital One Venture X Rewards Credit Card
With an annual fee of $395, the Capital One Venture X is widely regarded by industry analysts as one of the most straightforward premium cards on the market. The card’s structure is anchored by a $300 annual travel credit applicable through the Capital One Travel portal, paired with 10,000 anniversary bonus miles valued conservatively between $100 and $170. Combined, these two features frequently cover the card’s entire annual cost before factoring in everyday spending multipliers (such as a flat 2x miles per dollar on all purchases), Priority Pass membership, Capital One Lounge access, and robust primary rental car and cell phone protections.
Chase Sapphire Reserve
Commanding a $795 annual fee, the Chase Sapphire Reserve is exceptionally popular among younger demographics due to its robust ecosystem and flexible redemption options. The card offsets its cost through a combination of a $300 annual travel credit, a $300 annual dining credit, and a $500 annual hotel credit booked through designated channels. Additionally, cardholders earn elevated point multipliers on travel and dining, enjoy a Priority Pass membership, and gain unlimited access to the rapidly expanding network of Chase Sapphire Lounges, alongside the ability to transfer points to high-value partners like the World of Hyatt program.
American Express Platinum Card
As one of the earliest pioneers of the luxury card market, the American Express Platinum Card carries a substantial annual fee accompanied by an extensive roster of lifestyle and travel credits. While polarizing due to its complex coupon-book structure, the card can deliver immense value for dedicated users through up to $600 in annual hotel credits, up to $400 in Resy dining credits, airline fee reimbursements, and Uber cash allocations. It also provides the industry’s most comprehensive airport lounge collection, encompassing Centurion Lounges, Priority Pass, and selective access to Delta Sky Clubs, though it offers minimal rewards on non-airfare everyday spending.
Co-Branded Alternatives: Airline and Hotel Flagships
Beyond bank-branded ecosystems, co-branded luxury cards cater directly to brand loyalists. The Citi / AAdvantage Executive World Elite Mastercard, priced at $695 annually, provides a full American Airlines Admirals Club membership for the primary cardholder, with the added flexibility of adding up to three authorized users for a nominal aggregate fee of $175—granting lounge access to traveling companions as well. Similarly, the Hilton Honors American Express Aspire Card, with a $550 annual fee, bundles automatic top-tier Hilton Diamond status, an annual free night award redeemable at luxury properties, and multi-hundred-dollar resort and airline statement credits that can easily surpass the upfront cost for frequent hotel guests.
Alternatives for Consumers Seeking Simplicity
For consumers who conclude that high annual fee cards no longer align with their lifestyle, the credit card market offers lucrative alternatives that require significantly less administrative overhead. Many of the most rewarding cards for everyday spending carry modest annual fees or no fees at all.
Products such as the American Express Gold Card, the Capital One Venture Rewards Credit Card, the Chase Sapphire Preferred Card, and the Citi Double Cash Card allow consumers to accumulate highly valuable transferable points or straightforward cash-back rewards without the pressure of tracking fragmented monthly statement credits or navigating crowded lounge networks.
Frequently Asked Questions
Are high annual fee credit cards worth the investment?
For frequent travelers who organically utilize annual credits, value airport lounge access, and strategically redeem reward points, premium cards can yield a net positive financial return. Conversely, they offer little value for infrequent travelers or individuals unwilling to track expiration dates and perk structures.
How can a consumer accurately calculate a card’s net cost?
To determine true value, start with the annual fee and subtract only the face value of credits you are entirely confident you will use through normal, unforced spending. Next, assign a realistic dollar value to remaining perks such as lounge access, elite status, and travel protections, ignoring advertised retail values that exceed your personal utility.
Why do banking institutions structure luxury cards around micro-credits?
Statement credits serve multiple financial purposes for issuers. They are frequently subsidized or co-funded by merchant partners seeking customer acquisition, and they generate engagement within proprietary travel booking platforms. Additionally, structured expiration schedules rely on natural consumer forgetfulness, helping offset the cost of heavy cardholder usage.
Who should explicitly avoid premium credit cards?
Consumers who experience fatigue from tracking financial minutiae, find airport lounges overcrowded or unappealing, prefer low-effort cash back over points redemption, or travel infrequently should generally bypass high-fee cards in favor of no-annual-fee alternatives.
Conclusion
The market for premium credit cards reflects a broader consumer trend toward experiential luxury and optimized personal finance. While cards featuring annual fees exceeding $300—and in some cases approaching $800—can provide extraordinary financial returns for disciplined travelers, they require a deliberate commitment of time and attention.
As issuer incentives evolve and airport infrastructure continues to adapt to surging passenger volumes, consumers must carefully weigh the tangible financial benefits of statement credits and lounge access against the cognitive overhead of card management. Ultimately, the decision to hold a luxury card hinges on individual travel frequency, brand loyalty, and a realistic assessment of whether the card serves as an effortless travel companion or a complex administrative burden.


 Gabriela Annisa

 Lukman Taruna Persada Ramadan

 Tatiana Tantri Indah Sari

 Anjar Salim


 Dwi Wanna
