
 Gabriela Annisa
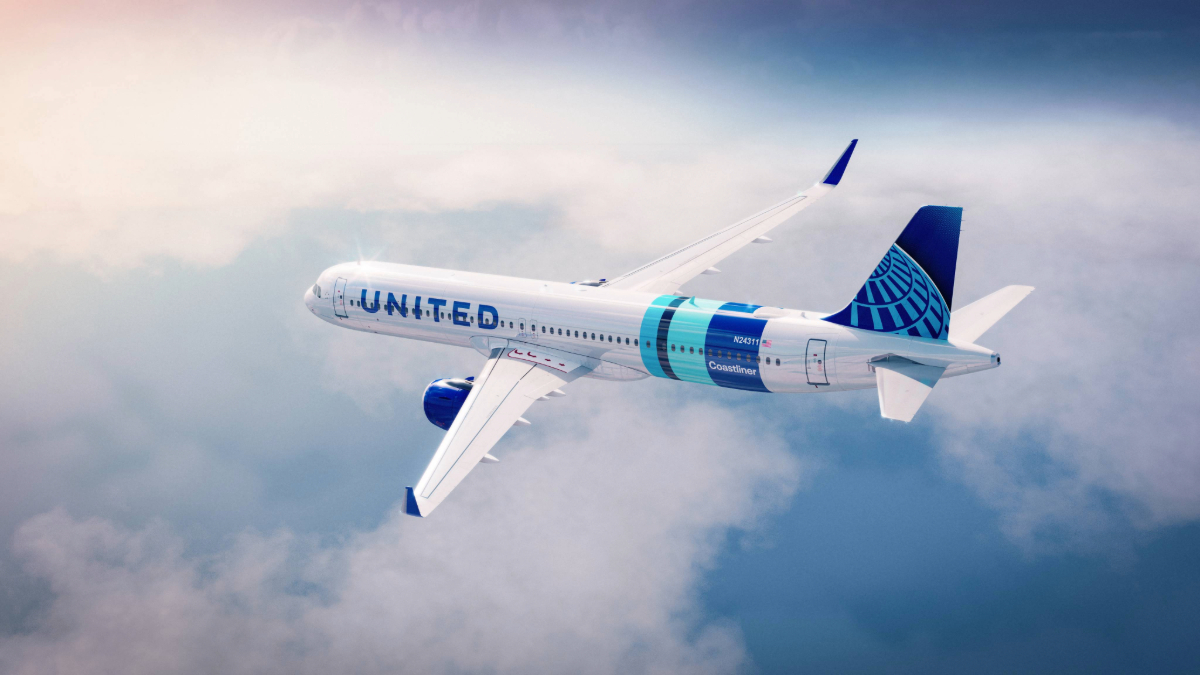
The landscape of transatlantic aviation is undergoing a structural transformation as major U.S. network carriers, specifically United Airlines and American Airlines, recalibrate their international portfolios to prioritize long-range, narrow-body operations. This shift, facilitated by the arrival of the Airbus A321XLR, signals a departure from the traditional reliance on massive wide-body fleets for secondary European markets. As these carriers pivot toward a model defined by frequency and premium cabin density, the industry is closely monitoring whether this gamble on high-end consumer demand will pay dividends in a volatile global economic environment.
The Evolution of the Transatlantic Network
For decades, the standard playbook for connecting the United States to Europe involved deploying wide-body aircraft—Boeing 777s, 787s, and Airbus A350s—to high-traffic hubs like London Heathrow, Frankfurt, and Paris Charles de Gaulle. This strategy focused on bulk capacity, moving large numbers of passengers across the Atlantic to consolidate traffic at major gateways. However, the post-pandemic recovery has highlighted a shift in traveler behavior, characterized by a persistent appetite for "bleisure" travel and a robust demand for premium cabin experiences.
United and American Airlines have recently unveiled aggressive expansion plans that leverage the specific capabilities of the Airbus A321XLR. Unlike its predecessors, the A321XLR offers the range of a wide-body with the operating economics of a single-aisle aircraft. This allows carriers to open "point-to-point" routes that bypass congested major hubs, connecting mid-sized U.S. cities directly to secondary European destinations that were previously deemed unprofitable for larger aircraft.
Chronology of the A321XLR Integration
The path to this strategic shift began long before the first commercial delivery of the A321XLR. The aviation industry’s interest in "middle-of-the-market" aircraft—a gap left by the discontinuation of the Boeing 757—created a vacuum that Airbus was eager to fill.
- 2019 Paris Air Show: Airbus officially launches the A321XLR, promising a range of up to 4,700 nautical miles, effectively allowing for flights between cities like New York and Rome or Boston and Lisbon with lower fuel burn.
- 2021-2022: As global travel demand rebounds from the pandemic, U.S. carriers accelerate their orders for narrow-body, long-range jets, viewing them as essential tools to test new routes without the massive financial exposure of wide-body aircraft.
- Late 2024: The first A321XLR units begin entering service with launch customers, signaling the start of a new era in fleet diversification.
- 2025 and Beyond: United and American Airlines move toward integrating these aircraft into their schedules, with a focus on trans-Atlantic frequencies that offer business travelers more flexibility and leisure travelers more direct access.
Supporting Data and Market Performance
The financial health of these airlines remains intrinsically linked to the performance of the broader aviation sector. According to the Skift Travel 200 (ST200) index, which aggregates the financial performance of nearly 200 travel companies, the airline sector has faced significant pressure due to rising labor costs, fluctuating jet fuel prices, and the complexities of aircraft delivery delays.
Market analysis indicates that the profitability of these new narrow-body routes is heavily weighted toward premium cabin sales. In a standard wide-body configuration, airlines rely on a mix of economy, premium economy, and business class to fill 250 to 300 seats. In the A321XLR, the seat count is significantly lower, often hovering between 160 and 190. To achieve similar margins, airlines must secure higher yields per seat, primarily through a higher percentage of lie-flat business class suites.
Data from the ST200 index underscores the importance of this high-yield strategy. As network carriers compete with low-cost carriers (LCCs) on price-sensitive routes, the "premium-heavy" narrow-body strategy provides a defensive moat. By offering a superior hard product in a smaller cabin, United and American are betting that the premium segment of the market will remain resilient, even if the economy class segment faces downward pressure from discount competitors.
Official Perspectives and Industry Reactions
While neither United nor American has publicly detailed the exact margins of their upcoming XLR routes, executive commentary during quarterly earnings calls has been consistently optimistic regarding premium demand. United Airlines executives have frequently highlighted the "Polaris" business class product as a key driver of international revenue, noting that even during periods of economic uncertainty, the corporate and luxury travel segments have shown sustained strength.
Conversely, some industry analysts have expressed caution. The primary concern is "premium fatigue." If the economy becomes sluggish, the reliance on high-paying business travelers could leave these point-to-point routes vulnerable. If an A321XLR is flying to a secondary city and the front-of-cabin seats go unsold, the lower total seat count of the aircraft makes it difficult to compensate for the lost revenue through volume, unlike a larger wide-body jet that can rely on economy-class filler traffic.
Broader Impact and Implications
The shift toward the A321XLR has profound implications for airport infrastructure and airline network planning. Smaller airports in the U.S. and Europe, which previously had to rely on connecting flights via major hubs to get passengers across the Atlantic, are now becoming viable international ports of entry. This decentralization of air travel could lead to a long-term reduction in the dominance of "mega-hubs," as passengers opt for the convenience of direct flights.
Furthermore, the environmental impact of this shift cannot be ignored. The A321XLR is significantly more fuel-efficient per seat than the aging wide-body fleets it is replacing. As carriers face increasing pressure to meet sustainability targets and reduce carbon emissions, the adoption of these narrow-body jets serves a dual purpose: improving financial margins and meeting corporate ESG (Environmental, Social, and Governance) goals.
Strategic Risk Analysis
The success of this strategy hinges on three critical factors:
- Revenue Management: The ability of airline algorithms to accurately predict and price premium demand on new, unproven routes.
- Operational Reliability: The A321XLR is a complex machine with new systems. Any unforeseen maintenance issues could disrupt schedules, and because these routes lack the frequency of hub-to-hub flights, a single cancellation could have a disproportionate impact on passenger satisfaction.
- Competitive Response: If United and American successfully prove that these secondary markets are profitable, legacy European carriers and low-cost long-haul airlines may move to defend their turf, potentially leading to capacity gluts and price wars.
The Future of Transatlantic Connectivity
As the aviation industry moves through the remainder of the decade, the integration of the A321XLR will serve as a bellwether for the health of the transatlantic market. The strategy represents a fundamental reimagining of what an "international route" looks like. It is no longer just about moving masses of people between major capital cities; it is about precision, premium service, and the agility to tap into niche demand.
Investors and stakeholders should continue to monitor the ST200 airline index for signs of margin expansion or contraction as these aircraft are deployed. If the premium-demand-led model proves sustainable, we can expect a continued decline in the importance of the traditional hub-and-spoke model, leading to a more fractured, but potentially more convenient, transatlantic travel experience.
For the average traveler, this means more direct options from regional airports, but potentially at a higher cost if the airline’s strategy to prioritize premium travelers succeeds. For the airlines, the stakes are high: they are betting that the modern traveler is willing to pay a premium for the convenience of a direct flight, regardless of the size of the aircraft. Whether this bet is the future of the industry or a temporary adjustment to changing market conditions will become clear as the flight schedules for the next three years take shape.
In conclusion, the transatlantic expansion led by United and American is not merely a fleet update; it is a strategic repositioning. By leaning into the capabilities of the A321XLR, these carriers are betting on their ability to command premium pricing in a competitive market. As the sector continues to navigate the complexities of global economic recovery and evolving passenger preferences, the performance of these narrow-body routes will be a primary indicator of the industry’s long-term profitability and strategic direction. The industry is watching, and the results of this shift will dictate the fleet procurement and route planning strategies of major global carriers for years to come.

 Anjar Salim
 Chandra Hamzah
 Susilo Edi Turonggo
 Tatiana Tantri Indah Sari
 Walid Sujud Trenggono
