
 Tatiana Tantri Indah Sari
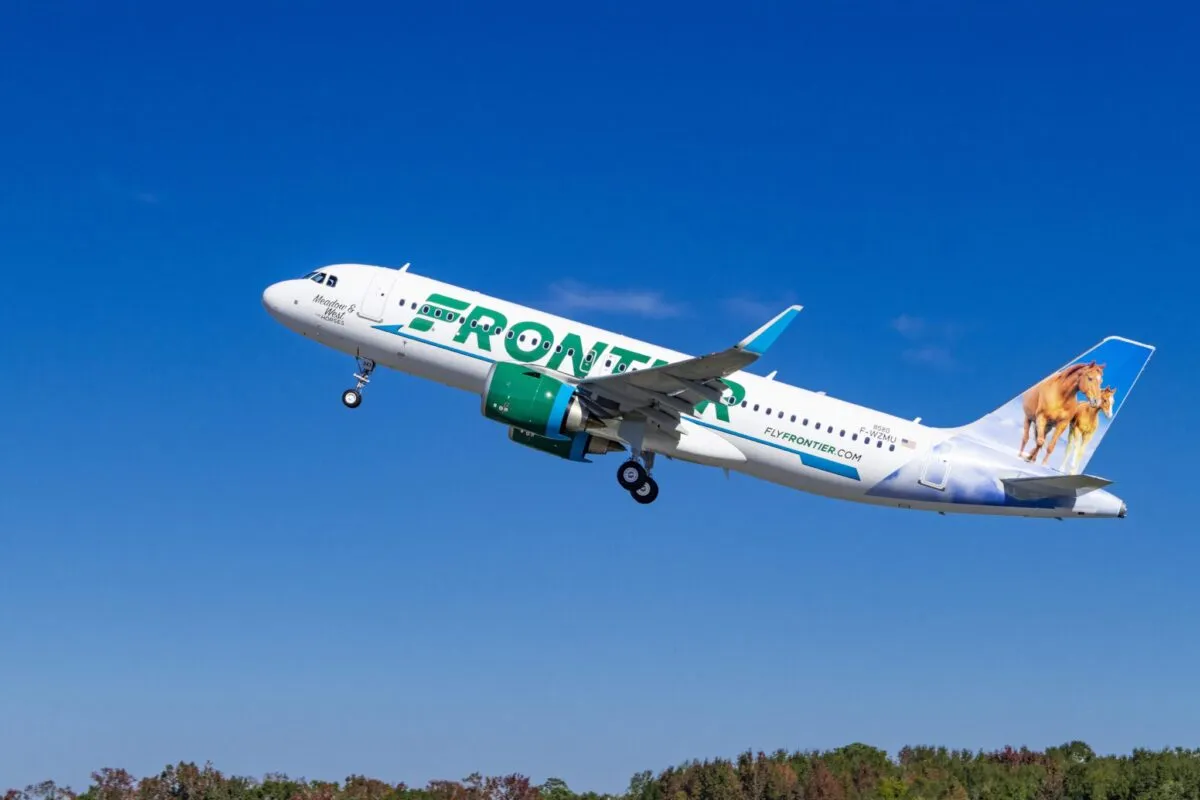
The commercial aviation sector is once again grappling with severe economic headwinds as jet fuel prices climb to levels not seen in recent years, placing an unprecedented squeeze on the airline industry. While legacy carriers and major network airlines possess the pricing power, diverse revenue streams, and corporate travel demand necessary to absorb these escalating operational expenses, ultra-low-cost carriers (ULCCs) are facing an existential crisis. Bound by a business model entirely dependent on rock-bottom fares to stimulate demand among price-sensitive leisure travelers, these budget airlines find themselves caught between soaring commodity costs and an inability to pass those expenses on to consumers. Compounding the crisis, lobbying efforts directed at federal lawmakers in Washington, D.C., have thus far yielded no appetite for legislative relief or targeted intervention.
The Anatomy of the ULCC Fuel Crisis
Jet fuel represents one of the most volatile and significant variable expenses for any commercial airline, typically accounting for between 20% and 30% of total operating costs depending on market fluctuations. For legacy carriers such as Delta Air Lines, United Airlines, and American Airlines, fuel spikes are routinely mitigated through a combination of sophisticated hedging strategies, premium cabin yields, robust international networks, and lucrative business-class bookings.
Ultra-low-cost carriers, however, operate under a fundamentally different economic paradigm. Airlines such as Allegiant Air, Frontier Airlines, Avelo Airlines, and Breeze Airways—all represented by the trade group Association of Value Airlines (AVA)—rely on unbundled pricing structures. They market base fares that are often remarkably inexpensive, enticing travelers to add on ancillary services such as seat selection, carry-on bags, and priority boarding. Because their core consumer base is extraordinarily price-elastic, even a modest increase in the base ticket price can trigger a precipitous drop in booking volumes. Consequently, when jet fuel prices surge, ULCCs cannot simply raise ticket prices across the board to match the rate of inflation or commodity increases without destroying their own demand model.
Industry lobbying efforts have ramped up significantly in response to this margin compression. Jonathon Freye, the executive director of the Association of Value Airlines, revealed in recent discussions that the trade organization has actively reached out to multiple congressional offices and key committees over the past several weeks. The goal was to initiate a dialogue regarding potential economic relief measures, emergency stabilization funds, or temporary tax suspensions aimed at alleviating the crushing burden of fuel expenses. To date, however, those overtures have been met with silence or indifference, signaling a distinct lack of legislative urgency on Capitol Hill to bail out the budget airline sector.
The House Transportation and Infrastructure Committee, which holds primary jurisdiction over domestic civil aviation policy, did not immediately respond to requests for comment regarding whether lawmakers are considering any form of economic assistance for regional and ultra-low-cost operators. The reluctance in Washington stems from a broader political and economic anxiety surrounding the persistent cost-of-living crisis. With inflation remaining a top concern for American voters, federal lawmakers are acutely sensitive to the optics of appearing to subsidize or rescue private aviation entities—particularly at a time when everyday consumers are struggling with high prices at the grocery store, the fuel pump, and across all modes of transportation.
A Timeline of Escalating Pressures
To understand the current vulnerability of the ultra-low-cost sector, it is necessary to examine the chronological sequence of events that has defined the post-pandemic aviation landscape.
During the initial recovery phase following the COVID-19 pandemic in 2021 and 2022, domestic leisure travel experienced an unprecedented boom, often referred to as "revenge travel." ULCCs capitalized on this surge, expanding routes into secondary and tertiary airports, adding capacity, and reporting robust load factors. However, this period also marked the beginning of extreme volatility in global energy markets, driven by geopolitical instability, supply chain bottlenecks, and shifting production quotas among major oil-producing nations.
By mid-2022, jet fuel prices shattered previous records, forcing all airlines to adjust their financial forecasts. While major carriers successfully tested the boundaries of consumer willingness to pay higher fares during the peak summer travel seasons, budget carriers began to see their operating margins erode. Unlike larger competitors, many ULCCs traditionally maintain minimal fuel-hedging portfolios—either due to the prohibitive costs of purchasing hedging contracts during periods of high market volatility or as a deliberate strategic choice to keep upfront capital expenditures low.
As the market moved into 2023 and 2024, the macroeconomic environment shifted further against the budget model. Inflationary pressures began to eat into the disposable income of middle- and lower-income households—the exact demographic that forms the backbone of the ULCC customer base. At the same time, labor costs rose sharply across the industry following a wave of new collective bargaining agreements for pilots, flight attendants, and ground operations personnel.
When jet fuel prices began another upward trajectory in late 2023 and early 2024, they did so against a backdrop of already compressed margins. By the time the Association of Value Airlines initiated its emergency outreach to congressional offices in recent weeks, the cumulative effect of high fuel, rising labor expenses, and softer ancillary yield growth had pushed several regional and ultra-low-cost operators into precarious financial territory. The legislative paralysis in Washington arrived precisely when these airlines were exhausting their internal financial buffers.
Economic Data and Market Realities
A quantitative analysis of the airline sector underscores the vast disparity in how fuel shocks impact different business models. According to historical data from the International Air Transport Association (IATA) and the U.S. Bureau of Transportation Statistics, jet fuel prices account for a disproportionately large share of operating expenses for airlines with shorter stage lengths and high-density, single-class seating configurations.
Ultra-low-cost carriers typically operate point-to-point networks using uniform aircraft fleets—predominantly Airbus A320 family jets or Boeing 737 variants—to maximize maintenance and crew efficiency. However, because many of their routes are short-to-medium haul, their aircraft spend a higher percentage of their operating hours in the climb and descent phases of flight, which consume significantly more fuel per mile than high-altitude cruising. When fuel prices per gallon spike by even 20% to 30%, the compounding effect on short-stage operations is mathematically severe.
Furthermore, financial disclosures from publicly traded ultra-low-cost carriers over recent quarters illustrate the toll of these market dynamics. While revenue figures have remained relatively stable due to high passenger volume, net income margins have contracted sharply. Several carriers have been forced to scale back network expansion plans, defer aircraft delivery schedules with manufacturers, and cancel underperforming routes that are no longer economically viable under high-fuel regimes.
Jonathon Freye captured the overarching sentiment of the industry in his statements to media and lawmakers, emphasizing that the affordability of transportation is a shared national priority. "There’s clearly a sort of concern about the affordability of transportation, and I think for a lot of our customers and the big carriers, too," Freye noted. Yet, this very concern for consumer affordability is what complicates the political calculus in Washington. Lawmakers are caught between wanting to ensure a competitive aviation market—where budget carriers keep legacy pricing in check—and avoiding policies that could be framed as government bailouts for private corporations during an inflationary cycle.
The Broader Implications for the U.S. Aviation Market
The ongoing distress within the ultra-low-cost carrier segment carries profound implications for the broader American economy, the competitiveness of the airline industry, and the traveling public.
First and foremost, the contraction or potential failure of budget carriers would severely diminish market competition. Economic studies consistently demonstrate the "Southwest effect"—or more broadly, the "ULCC effect"—wherein the entry of a low-cost carrier into a specific market forces incumbent legacy airlines to dramatically lower their fares on that route. If high fuel prices and a lack of federal support force budget airlines to permanently reduce capacity, exit secondary markets, or consolidate, consumers across the United States could experience a significant resurgence in monopolistic or oligopolistic pricing by major network airlines.
Secondary and tertiary airports would also bear the brunt of any retrenchment by carriers like Allegiant, Avelo, and Breeze. Many smaller municipalities have invested heavily in terminal expansions, parking infrastructure, and marketing incentives to attract low-cost service, viewing it as an essential economic lifeline that connects local populations to major economic and tourism hubs. A reduction in service to these regional airports would have immediate negative ramifications for local tourism economies and regional business connectivity.
Moreover, the financial strain on ULCCs may accelerate industry consolidation. Throughout the history of U.S. deregulation, periods of high fuel prices and economic stress have frequently triggered mergers, acquisitions, or bankruptcies. While antitrust regulators under the current administration have maintained a highly skeptical stance toward airline mega-mergers—as evidenced by recent high-profile legal challenges to airline partnerships and proposed combinations—financial distress could eventually force regulators to weigh the risk of carrier failures against the complexities of market consolidation.
As Capitol Hill remains noncommittal and energy markets continue to exhibit heightened volatility, the path forward for ultra-low-cost carriers remains fraught with uncertainty. Without the cushion of heavy corporate travel revenues, extensive international route networks, or comprehensive fuel-hedging programs, budget airlines must rely on internal cost-cutting, nimble schedule adjustments, and hope for a stabilization in global commodity prices. For millions of American travelers accustomed to flying for a fraction of traditional airfares, the coming months will test the resilience of the low-cost model and determine whether affordable air travel remains a viable fixture of the modern transportation landscape.

 Anjar Salim
 Dwi Wanna
 Chandra Hamzah
 Gabriela Annisa
 Susilo Edi Turonggo
