
 Gabriela Annisa
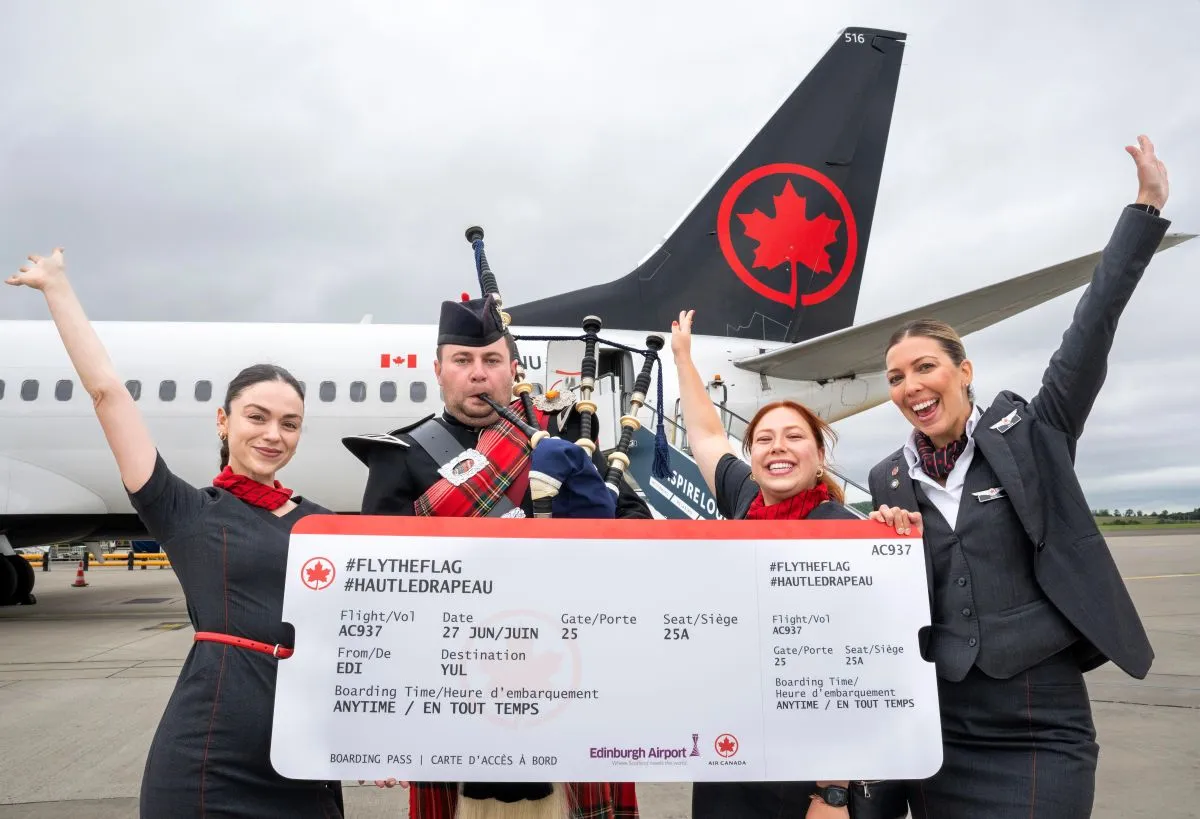
Air Canada stands at a pivotal juncture as it navigates the complex interplay of post-pandemic travel demand, a shifting global economic landscape, and the internal operational mandates facing its incoming leadership. As the carrier looks toward the next phase of its growth, analysts are increasingly focused on whether the airline can leverage its robust North American network to offset the systemic volatility inherent in long-haul international markets. Simultaneously, the global aviation industry is closely monitoring the People’s Republic of China, where the "Big Three" carriers—Air China, China Southern Airlines, and China Eastern Airlines—have reported significant financial headwinds during the second quarter of the current fiscal year. These two narratives, while geographically distinct, highlight the broader structural challenges currently defining the commercial aviation sector in 2024.
The Air Canada Transition: Opportunities and Operational Hurdles
Air Canada has spent the last several years aggressively restoring its network capacity, which was decimated during the COVID-19 pandemic. Under the guidance of current leadership, the airline has prioritized the expansion of its hub-and-spoke model, particularly at Toronto Pearson, Vancouver, and Montreal-Trudeau. However, the path forward is not without significant friction. The airline is currently balancing the need to reinvest in its fleet and customer experience against the backdrop of rising labor costs, inflationary pressures on fuel, and the logistical complexities of maintaining a reliable global schedule.
Industry experts point to the "Anko" transition—referring to the strategic hand-off as the airline evolves its executive structure—as a defining moment for the company. The opportunity for Air Canada lies in its unique geographical position as a gateway between Asia and the Americas, as well as its strength in the transatlantic corridor. By utilizing its fleet of Boeing 787 Dreamliners and Airbus A321XLRs, the airline is well-positioned to serve secondary city pairs that larger competitors might overlook.
Yet, the challenges remain acute. Air Canada’s operational reliability has been under the microscope following a series of high-profile delays and cancellations that characterized the recovery period. Addressing these "pain points" is essential for long-term brand equity. Furthermore, the airline must contend with a competitive Canadian landscape where ultra-low-cost carriers (ULCCs) are increasingly attempting to capture price-sensitive domestic traffic, potentially pressuring yields on short-haul routes that were historically profitable for the national flag carrier.
A Chronology of Post-Pandemic Aviation Recovery
To understand the current volatility, one must review the timeline of the industry’s recovery since 2020.
- 2020-2021: The Survival Phase. Global aviation ground to a halt. Air Canada, like its peers, pivoted to cargo-only operations, utilizing passenger aircraft to maintain cash flow while passenger revenue plummeted by over 90%.
- 2022: The Rebound and Operational Bottlenecks. As borders reopened, the surge in "revenge travel" caught the industry off-guard. Staffing shortages in ground handling, security, and air traffic control led to a summer of systemic delays.
- 2023: Stability and Premium Demand. Airlines saw a return to profitability, driven largely by high yields in premium cabins. Business travel began a slow, if uneven, recovery.
- 2024: The Normalization and Sector Divergence. The current year has been defined by a cooling of the initial post-pandemic demand surge. Airlines are now focusing on efficiency, cost-cutting, and navigating macroeconomic headwinds, such as the slowdown in the Chinese economy and persistent inflation in North America.
The Chinese Aviation Crisis: Why the Big Three Struggled
The second quarter of 2024 served as a sobering reminder of the difficulties facing the Chinese aviation market. Air China, China Southern, and China Eastern, which collectively represent the backbone of China’s air travel, reported financial results that fell short of market expectations. Several factors contributed to this underperformance.
First, the expected surge in international outbound travel from China has been slower than anticipated. During the pre-pandemic era, Chinese travelers were the primary engine of global tourism growth. Their slow return to international travel—partially due to visa processing delays and the lingering effects of a domestic economic slowdown—has left the Big Three with significant excess capacity on long-haul routes.
Second, the domestic market has become hyper-competitive. In an effort to keep aircraft in the air, carriers have engaged in aggressive price wars, which have severely compressed yields. Even as volume has returned to near 2019 levels, the revenue per available seat kilometer (RASK) has remained depressed.
Third, the Chinese aviation sector is heavily exposed to fluctuations in the renminbi and rising jet fuel costs. Because a significant portion of their operational costs—such as aircraft leasing and fuel—are denominated in U.S. dollars, the depreciation of the local currency has exacerbated the financial burden on these airlines. Analysts at Skift and other industry observers note that until these carriers can improve their load factors on international routes and rationalize domestic capacity, the path to a sustained return on invested capital (ROIC) remains obstructed.
Comparative Financial Metrics: The Skift Travel 200
The Skift Travel 200 (ST200) index provides a comprehensive look at how these varied pressures impact the broader travel sector. The index, which tracks nearly 200 travel companies with a combined market capitalization exceeding $1 trillion, reveals a bifurcated market.
Network carriers, particularly those in North America, have shown resilience due to the strength of their loyalty programs and premium cabin offerings. However, as the ST200 data indicates, the overall airline sector has experienced a "reversion to the mean" following the explosive growth of 2022 and 2023. Investors are now scrutinizing balance sheets for debt reduction progress, a critical metric for airlines that took on massive leverage during the pandemic.
When evaluating Air Canada against its international peers, analysts look specifically at debt-to-EBITDA ratios and the pace of fleet modernization. While the airline has made significant strides in repairing its balance sheet, the market is waiting for evidence that it can maintain margins in the face of the aforementioned labor and fuel pressures.
Official Responses and Industry Sentiment
While the airlines themselves rarely comment on speculative market analysis, recent investor relations disclosures from the carriers provide insight into their strategic posture. Air Canada’s leadership has consistently emphasized "disciplined capacity growth" and a focus on premium service as the primary levers for maintaining profitability. The message is clear: rather than chasing volume at the expense of yield, the carrier is pivoting toward a strategy that prioritizes high-margin corporate and international premium passengers.
In China, the response from the Big Three has been more subdued, focusing on government-backed initiatives to stimulate domestic consumption and the slow, steady restoration of international flight corridors. Industry analysts suggest that the Chinese carriers are currently in a state of "strategic patience," waiting for a broader macroeconomic rebound in China to stimulate the discretionary spending required to sustain long-haul international growth.
Broader Implications for the Global Aviation Industry
The challenges faced by Air Canada and the Chinese Big Three are indicative of a larger trend in global aviation: the end of the "easy growth" era. For the past three years, the industry was buoyed by pent-up demand and a willingness among consumers to pay a premium for travel regardless of the cost. As the market enters a period of stabilization, the focus is shifting back to the fundamentals of airline economics.
The implications are twofold. First, airlines must become more adept at yield management. With consumer spending potentially tightening, the ability to segment passengers and maximize revenue per seat will distinguish the winners from the losers in the next decade. Second, the industry must prepare for a more fragmented global landscape. Geopolitical tensions, fluctuating currency values, and inconsistent regulatory environments across different regions mean that a "one-size-fits-all" strategy is no longer viable.
For Air Canada, the immediate future will be defined by its ability to integrate new fleet technology while managing labor relations and maintaining service quality. For the Chinese carriers, the hurdle is more fundamental: they must navigate a domestic market that is structurally oversupplied while waiting for the international traveler to return in sufficient numbers to restore profitability.
In conclusion, while both entities operate in vastly different environments, they are bound by the same reality: the aviation industry has moved past the recovery phase and is now entering a period of profound structural adjustment. Whether it is through the strategic refinement of a national flag carrier in Canada or the macro-economic stabilization of the Chinese aviation giants, the coming quarters will be critical in determining which airlines are best positioned to thrive in an increasingly complex global economy. The data provided by the Skift Travel 200 will remain an essential tool for investors and stakeholders as they monitor how these individual companies navigate these systemic shifts.

 Anjar Salim
 Dwi Wanna
 Chandra Hamzah
 Tatiana Tantri Indah Sari
 Walid Sujud Trenggono
