
 Tatiana Tantri Indah Sari
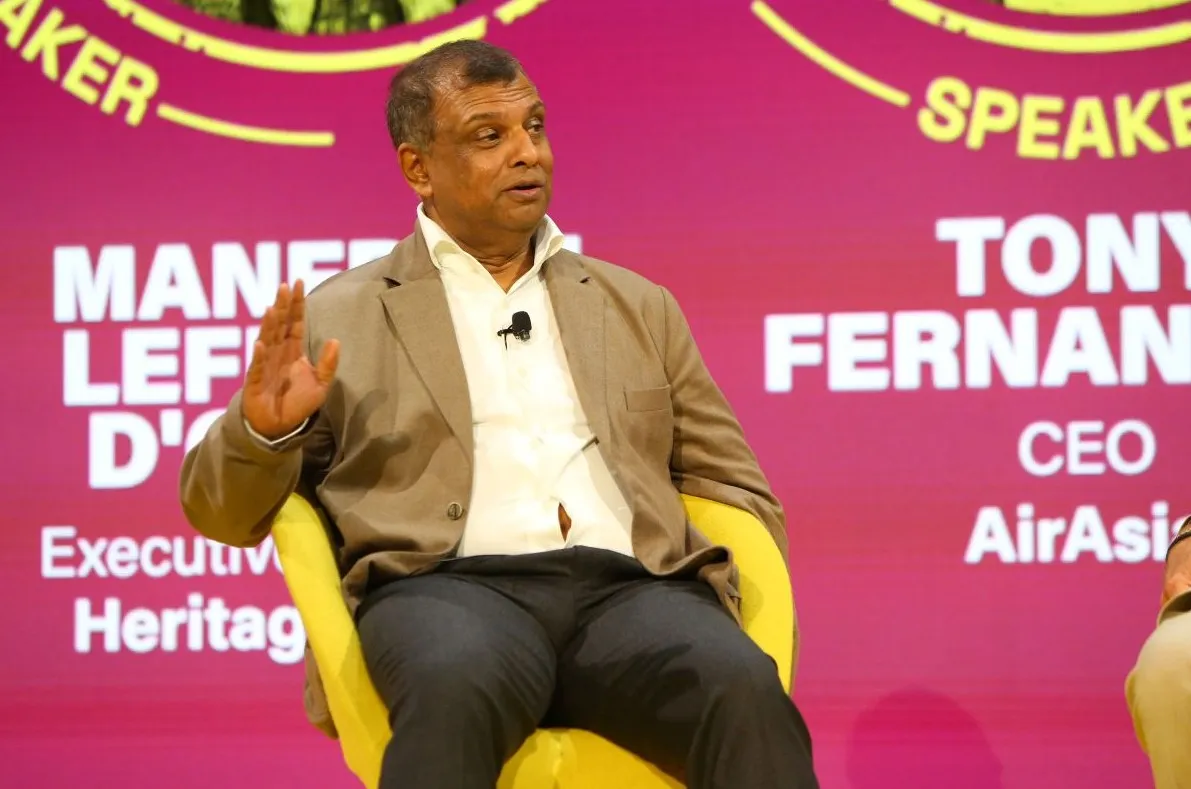
AirAsia co-founder Tony Fernandes has categorically dismissed recent media reports suggesting that the Malaysian government has held formal discussions regarding the potential reallocation of the low-cost carrier’s domestic flight capacity to competing airlines. Speaking passionately to a gathering of journalists, analysts, and investors in Bangkok during a regional tour of AirAsia’s Southeast Asian operating hubs, Fernandes characterized the rumors as misinformation that fundamentally misunderstands the complexities of modern commercial aviation economics.
The controversy emerged amid mounting speculation regarding AirAsia’s operational footprint in Malaysia, fueling intense scrutiny over the airline group’s competitive positioning and broader financial health. However, Fernandes pushed back aggressively against the narrative that rival carriers could effortlessly step into the market void should AirAsia scale back operations, emphasizing that the airline’s hyper-efficient business model and distinct cost structures are entirely unique and impossible to replicate overnight.
Anatomy of the Rumors and the Bangkok Press Conference
The speculation surrounding AirAsia’s domestic capacity originated from unverified reports suggesting that Malaysian transport regulators were actively evaluating contingency plans to maintain route connectivity in the event of capacity reductions by the budget aviation giant. These rumors immediately triggered concern among industry watchers, who questioned whether AirAsia was facing severe structural distress.
Addressing these concerns directly in the Thai capital, Fernandes sought to draw a sharp distinction between prudent capacity management and systemic vulnerability. He underscored that commercial aviation is not a zero-sum game where routes and passengers can be transferred like commodities between competing operators.
"We are a unique brand," Fernandes told the audience in Bangkok. "You can’t just step in and take over our operations. The underlying infrastructure, the crew training, the ancillary revenue streams, and, most importantly, our cost structure cannot simply be duplicated by a competitor."
Fernandes reiterated that AirAsia remains deeply committed to its foundational Malaysian market, even as the group undertakes necessary operational adjustments to navigate a uniquely hostile macroeconomic environment defined by volatile commodity markets and geopolitical instability.
The Geopolitical Catalyst: Soaring Jet Fuel Costs and Regional Conflict
At the heart of AirAsia’s recent strategic adjustments is an unprecedented surge in global jet fuel prices, exacerbated heavily by the geopolitical fallout from the ongoing conflict involving Iran and broader tensions across the Middle East. Jet fuel traditionally represents the single largest variable expenditure for commercial airlines, frequently accounting for between 30% and 40% of total operating costs.
The outbreak of hostilities in the Middle East has sent shockwaves through international energy markets, creating sudden supply chain bottlenecks and driving crude oil benchmarks significantly higher. For a low-cost carrier whose entire value proposition relies on maintaining razor-thin margins to offer passengers ultra-competitive fares, the spike in fuel expenses poses an acute financial challenge.
In response to these soaring overhead costs, Fernandes confirmed that AirAsia has proactively engaged in aggressive capacity rationalization. Rather than waiting for financial distress to force its hand, management has systematically reviewed its route network, trimming underperforming or marginal routes and accelerating the return of leased aircraft to lessors. These decisive measures are explicitly designed to preserve institutional cash reserves and maintain balance sheet resilience until energy markets stabilize.
Despite these tactical contractions on secondary routes, Fernandes emphasized that AirAsia is actively fortifying its core portfolio. The airline is channeling resources into major domestic trunk routes and high-demand regional corridors where consumer demand remains exceptionally robust, ensuring that its most profitable pillars continue to generate steady cash flow.
Decoding the Low-Cost Business Model: Why Rivals Cannot Easily Absorb Capacity
The suggestion that rival airlines could seamlessly absorb AirAsia’s domestic capacity exposes a fundamental misunderstanding of low-cost carrier (LCC) economics, according to aviation analysts. Unlike legacy network carriers, which rely on complex hub-and-spoke models, premium cabins, and global alliance partnerships, LCCs like AirAsia operate on a strict point-to-point philosophy designed to maximize asset utilization.
To successfully absorb AirAsia’s market share, a competing airline would need to match several stringent operational criteria:
- Fleet Uniformity: AirAsia operates an all-Airbus A320 and A321 family fleet, which drastically reduces maintenance costs, spare parts inventory expenses, and pilot training overhead. Competitors operating mixed fleets would struggle to match these economies of scale.
- High Aircraft Daily Utilization: AirAsia’s business model requires its aircraft to spend minimal time on the ground between flights, turning planes around in record time to generate revenue-flying hours. Replicating this turnaround efficiency demands specialized ground operations and corporate culture.
- Ancillary Revenue Integration: A significant portion of AirAsia’s profitability stems from non-ticket revenue, including baggage fees, seat selection, onboard dining, and digital travel services through its super-app ecosystem. Competitors lacking integrated digital platforms cannot easily replicate this financial cushion.
- Labor Productivity: The cost-per-available-seat-kilometer (CASK) achieved by AirAsia is among the lowest in the global aviation industry. Rival carriers, particularly those burdened by legacy labor agreements or higher structural overheads, would incur substantial operating losses if they attempted to match AirAsia’s low-fare offerings on identical routes without the corresponding cost efficiencies.
Fernandes’s critique highlights the reality that capacity in aviation is not merely a physical allocation of seats, but the ultimate output of a deeply integrated operational ecosystem. Removing one player does not mean another can simply fill the physical airspace without severely impacting ticket pricing for consumers.
Chronology of Events and Market Scrutiny
The unfolding situation surrounding AirAsia reflects a turbulent multi-year timeline defined by recovery, macroeconomic shocks, and strategic restructuring:
- 2020–2022 (The Pandemic Era): Like all global airlines, AirAsia faced near-total grounding of its fleet due to COVID-19 travel restrictions, forcing management into extensive debt restructuring and the creation of Capital A Berhad as an overarching holding company for its aviation and digital ventures.
- 2023 (The Post-Pandemic Rebound): Passenger demand surged dramatically across Southeast Asia as borders reopened, allowing AirAsia to gradually reactivate parked aircraft and restore a significant portion of its pre-pandemic international and domestic networks.
- Early 2024 (Macroeconomic Pressures Begin to Mount): Inflationary pressures, currency fluctuations against the U.S. dollar (in which aircraft leases and fuel are denominated), and rising interest rates begin to squeeze airline margins across the Asia-Pacific region.
- Mid-2024 (Geopolitical Escalation): The expansion of conflict involving Iran sends global crude oil prices soaring, directly triggering an immediate and sharp escalation in jet fuel refining margins and spot prices.
- Late 2024 (Strategic Retrenchment and Rumors): AirAsia initiates proactive route rationalization and fleet adjustments to preserve cash. Simultaneously, rumors circulate in domestic media regarding government discussions on capacity reallocation, prompting intense public scrutiny.
- Present Day: Tony Fernandes delivers his definitive rebuttal in Bangkok, clarifying the airline’s strategic posture, denouncing misinformation, and reaffirming AirAsia’s unyielding commitment to the Malaysian domestic market.
Broader Economic and Regulatory Implications
The friction between government oversight, market competition, and airline financial health carries significant implications for the broader Southeast Asian aviation landscape. As governments across the region strive to protect consumer interests and ensure affordable travel options, they must balance regulatory interventions with an understanding of private-sector commercial realities.
For Malaysia, AirAsia remains a critical pillar of national connectivity, linking major urban centers with remote domestic destinations that might otherwise be economically unviable for higher-cost carriers. Any disruption to AirAsia’s operational network would not only impact tourism and business travel but could also exert upward pressure on domestic airfares, directly harming consumers.
Furthermore, Fernandes’s public comments signal a clear message to investors and competitors alike: AirAsia is navigating current macroeconomic headwinds from a position of strategic autonomy. By pruning non-essential routes and defending its core strongholds, the airline aims to insulate itself from prolonged energy price shocks without relinquishing its hard-fought market dominance.
As the airline industry continues to adapt to a volatile global landscape characterized by persistent geopolitical risks, the resilience of ultra-low-cost carriers will remain under close observation. For now, Fernandes has made it unequivocally clear that AirAsia intends to dictate its own operational destiny, dismissing outside speculation and doubling down on the foundational efficiencies that built its empire.

 Walid Sujud Trenggono
 Budi Mulyono
 Lukman Taruna Persada Ramadan
 Anjar Salim
