Chandra Hamzah
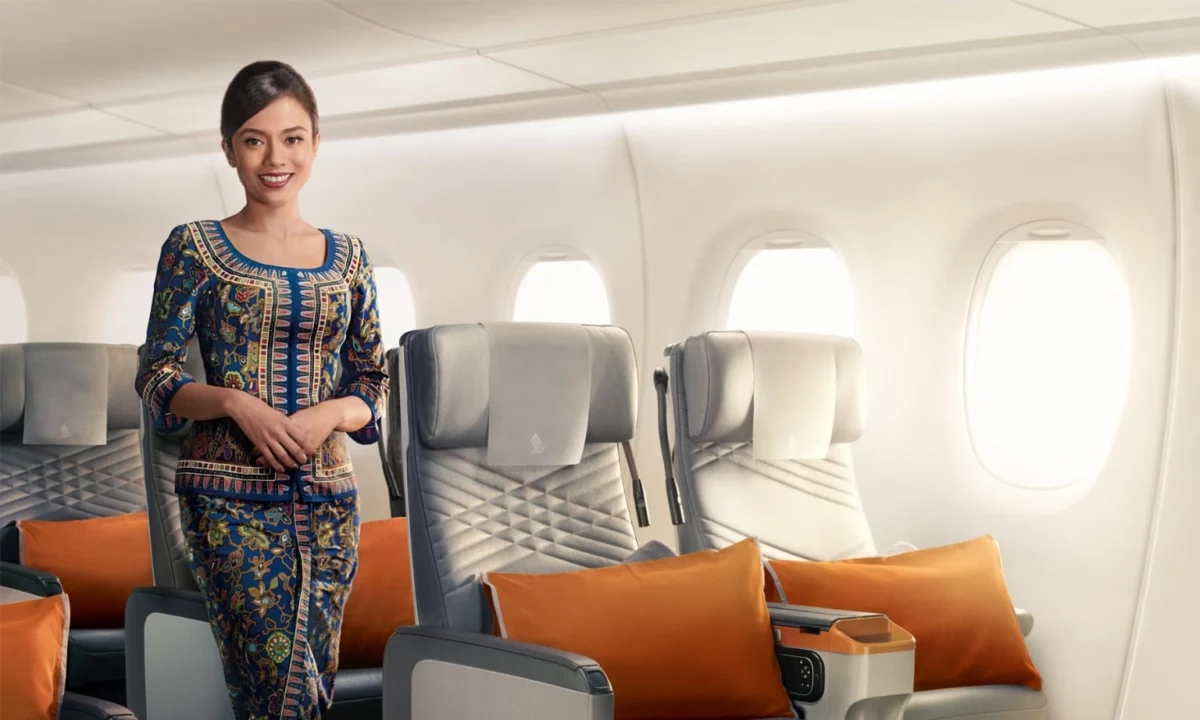
The landscape of international travel for Australians is undergoing a significant transformation as thousands of holidaymakers, particularly those heading to European cruise destinations, shift their loyalty toward Asian airlines. While long-standing reliance on Gulf carriers has defined the Australian outbound market for decades, a combination of record-low airfares and a diversification of travel preferences has led to a surge in demand for carriers operating out of China, Malaysia, and Vietnam.
This shift is not merely anecdotal; it is reflected in robust booking data from the June to September peak travel period. According to Flight Centre Travel Group, there has been a triple-digit percentage increase in demand for several Asian carriers compared to the previous year. China Eastern Airlines has seen a staggering 278 per cent surge in bookings, while China Airlines and Malaysia Airlines have experienced growth of 118 per cent and 103 per cent, respectively.
A Shifting Market Dynamic
Industry analysts suggest that the primary driver of this trend is a blend of economic necessity and a heightened awareness of alternative routing. With the "Euro Summer" remaining a bucket-list goal for many Australians, the cost of airfare has become the deciding factor. John Kavanagh, Global Leisure CEO at Flight Centre Travel Group, noted that while these carriers have long been a viable, albeit secondary, option, they have recently entered the mainstream consciousness for Australian travelers.
"What I do think has happened is that there is a large number of people who are considering alternate ways to get to Europe, many for the first time ever," Kavanagh said. He added that the current pricing environment is characterized by fares that are "simply too good to pass up."
Current market offerings support this assessment. Travelers can find premium economy return flights from Melbourne to Paris with Vietnam Airlines for approximately $3,458, while return fares from Brisbane to Madrid on China Southern have been spotted for as low as $1,200. These price points, which some industry observers suggest are aggressive enough to appear as pricing errors, have prompted a rush to secure bookings well in advance of the northern summer.
The Role of Cruise Tourism
The rise of the "fly-cruise" model is a significant contributor to these trends. Data from the Cruise Lines International Association (CLIA) reveals that 286,000 Australians ventured outside of the domestic, New Zealand, and South Pacific markets for cruises in the most recent reporting period—an increase of 17 per cent.
For these passengers, the flight is a necessary precursor to the cruise, and the total cost of the holiday package is highly sensitive to airfare fluctuations. As cruise lines expand their offerings in the Mediterranean and Northern Europe, the demand for affordable, reliable air connectivity has reached an all-time high. Projections for 2025 indicate that Australian passenger volume in the Mediterranean alone is expected to reach 92,000, up from 82,000 in 2024, placing further pressure on travelers to find cost-effective transit routes.
Chronology of Market Shifts
The aviation market in Australia has been in a state of flux since the post-pandemic reopening of borders. The timeline of this shift can be viewed through several distinct phases:
- 2022–2023 (The Recovery Phase): As international travel resumed, demand significantly outstripped supply. Major carriers, particularly those in the Middle East, enjoyed high load factors and premium pricing due to the pent-up demand for travel.
- Late 2023–Early 2024 (Geopolitical Volatility): Escalating tensions in the Middle East led to regional instability, causing a temporary dip in confidence regarding transit through major hubs like Dubai and Doha. While Department of Foreign Affairs and Trade (DFAT) warnings regarding the region have since been adjusted, the initial hesitation prompted many travelers to look toward alternative transit hubs in Singapore, Kuala Lumpur, and mainland China.
- Mid-2024 (The Price War): Asian carriers, having ramped up their capacity, began utilizing aggressive pricing strategies to capture market share. This coincided with an increased focus on onboard product improvements, such as the introduction of high-speed satellite connectivity and revamped culinary offerings.
Enhanced Onboard Experiences
The pivot toward Asian carriers is also being supported by significant investments in passenger experience. Recognizing that long-haul travel requires more than just a competitive fare, these airlines are upgrading their service portfolios.

Vietjet, for instance, has integrated Starlink’s high-speed in-flight internet across its fleet, including the A320 and A330 aircraft servicing Australian routes, addressing a common pain point for modern travelers. Similarly, Singapore Airlines has announced a comprehensive overhaul of its culinary program, with over 100 new and refreshed dishes debuting this November. These updates range from elevated business class offerings, such as Maine lobster poached in champagne sauce, to specialized dessert menus across all cabins, signaling a move to capture the "premium-leisure" market that has traditionally favored European or Gulf-based legacy carriers.
Data Analysis: Airline Market Share
The most recent data from the Australian Bureau of Statistics, reflecting figures from June 2026, provides a snapshot of the competitive landscape. While the data includes both Australian residents and overseas visitors, it serves as a reliable barometer for general market share.
Qantas and Jetstar remain the dominant players, collectively holding 31.5 per cent of the international passenger market. However, the movement among international carriers is telling. Emirates, which historically held a dominant position in the Australian long-haul market, saw its share of international passengers to and from Australia drop from 6.6 per cent in June 2025 to 3.5 per cent in June 2026.
While the exact causal link between geopolitical tension and this drop remains complex—as it also involves capacity allocation and global fleet movements—the decline underscores the volatility inherent in the current international aviation market. Meanwhile, carriers such as China Southern, Malaysia Airlines, and Singapore Airlines continue to solidify their positions, with Singapore Airlines currently capturing 9.5 per cent of the total international market share.
Broader Implications for Australian Travelers
The implications of this trend are twofold. For the consumer, the increased competition is a windfall, offering more price points and service levels for long-haul travel. However, it also requires a more nuanced approach to booking. Travelers must weigh the benefits of a cheaper fare against the nuances of layover durations, visa requirements for transit, and the varying levels of service consistency among different carriers.
For the aviation industry, the trend represents a fundamental rebalancing. The "hub-and-spoke" model, which has relied heavily on the Middle East as the primary gateway between Australia and Europe, is now sharing the load with a more diverse array of Asian hubs.
Expert Perspectives and Future Outlook
Industry experts caution against assuming that this shift represents a permanent abandonment of Middle Eastern carriers. According to John Kavanagh, the recovery of routes through hubs like Dubai and Doha has been robust, and they remain the preferred choice for a large segment of the market. "Emirates and Qatar are still the most popular option for our customers," Kavanagh stated. "It’s not a case of people being hesitant to fly through the Middle East anymore; it’s a case of people exploring the full range of options available to them."
Looking forward, the competitive landscape is likely to intensify. As Asian airlines continue to expand their fleets and invest in the "soft product" of the passenger experience—such as improved dining and technology—the gap in perceived quality between them and the traditional "Big Three" Middle Eastern carriers is narrowing.
For the average Australian traveler planning a trip to Europe in the coming year, the advice from industry professionals is consistent: the market is currently a buyer’s market, but one that requires diligence. Monitoring fare fluctuations, booking well in advance, and remaining open to non-traditional transit hubs are the best strategies to secure both value and convenience. As the aviation industry continues to navigate the complexities of global demand and geopolitical shifts, the Australian consumer remains the primary beneficiary of this newfound competition in the skies.

 Lukman Taruna Persada Ramadan
 Tatiana Tantri Indah Sari
 Anjar Salim
 Budi Mulyono